Last Updated
October 18, 2026
Read Time
Share
Should you only pay for a vehicle in cash or is it okay to use financing to get a reliable car? The value of a car drops like a rock as soon as it’s driven off the lot, so it makes sense to pay in cash if you are able. However, it just isn’t possible to pay for a reliable vehicle in cash for many Americans. We created our 20/3/8 car buying rule to help keep your financial life on-track when taking out a car loan.
What is the 20/3/8 rule?
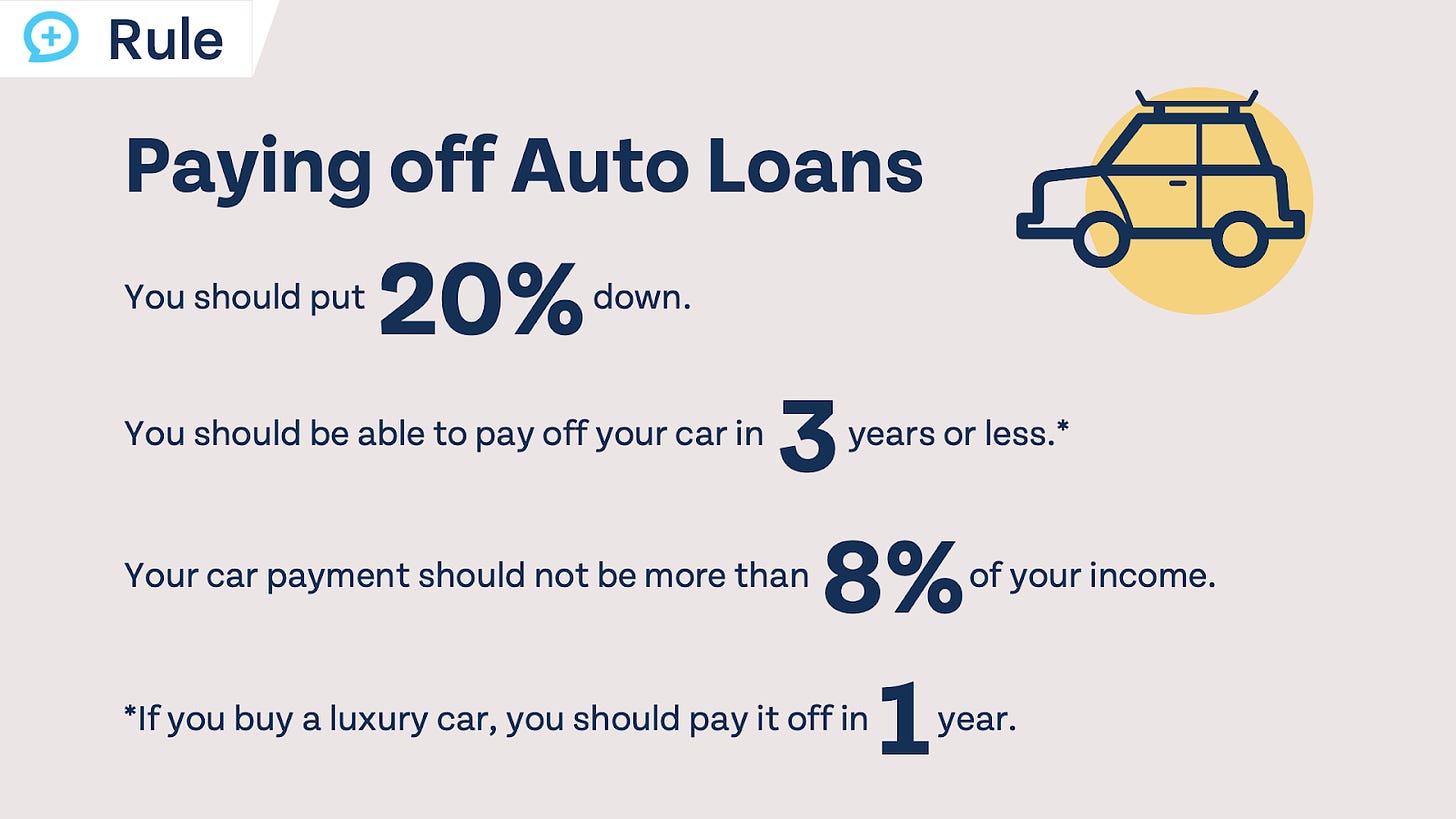
The 20/3/8 rule is a framework for determining how much car you can comfortably afford without negatively impacting other areas of your financial life. To follow the rule, you must put at least 20% down, pay your loan off in 3 years or less, and keep total monthly car payments below 8% of your gross income. Learn more about our 20/3/8 car-buying rule here, and use our free calculator to see how much car you can afford.
Should you pay cash or finance?
Copy link to this section: Should you pay cash or finance?
Copied the URL to your clipboard!
Copy link to this section: Should you pay cash or finance?
Copied the URL to your clipboard!
Just because you can take out an auto loan doesn’t mean you should. The 20/3/8 rule is a framework for using financing to purchase a vehicle, but if you can pay for your car in full, you should consider doing so. If you check the following boxes, chances are you should be paying for your car in cash.
- You are at Step 8 or 9 of the Financial Order of Operations (prepaid future expenses or paying off low-interest debt).
- You are investing 25% or more for your retirement (or you are already retired).
- Your have the ability to pay for a vehicle in full from your savings or cashflow.
We recognize not everyone is at a stage of life where they have the ability to pay for a reliable vehicle in full, and that’s okay. Dependable transportation is often a requirement for making money in the US, which means a car is a necessity. Rather than purchasing the cheapest vehicle money can buy, we believe it makes more financial sense to use an auto loan to get yourself in a reliable car.
How much car can you afford?
Copy link to this section: How much car can you afford?
Copied the URL to your clipboard!
Copy link to this section: How much car can you afford?
Copied the URL to your clipboard!
Now that you know our car buying guidelines, what does that look like for you specifically? The table below shows how much car loan you can afford at different incomes. If your monthly household income is $7,500 ($90,000 per year), you would be able to take on a car loan of $20,000 (with a purchase price of $25,000) while staying within our guidelines. However, you could put down $10,000 and buy a $30,000 car; or maybe you want a $40,000 car, in which case you would put down $20,000.
| Monthly gross income | Max car payment (8%) | Max loan | Max car price (20% down) |
|---|---|---|---|
| $2,500 | $200 | $6,700 | $8,300 |
| $5,000 | $400 | $13,300 | $16,700 |
| $7,500 | $600 | $20,000 | $25,000 |
| $10,000 | $800 | $26,700 | $33,400 |
| $12,500 | $1,000 | $33,400 | $41,700 |
This table assumes your loan is paid off over 36 months and your interest rate is 5%. If you don’t see your income on the table above, don’t worry! We created a car affordability calculator where you can see exactly how much car you can afford using our Money Guy guidelines.
New vs. used vehicles
Copy link to this section: New vs. used vehicles
Copied the URL to your clipboard!
Copy link to this section: New vs. used vehicles
Copied the URL to your clipboard!
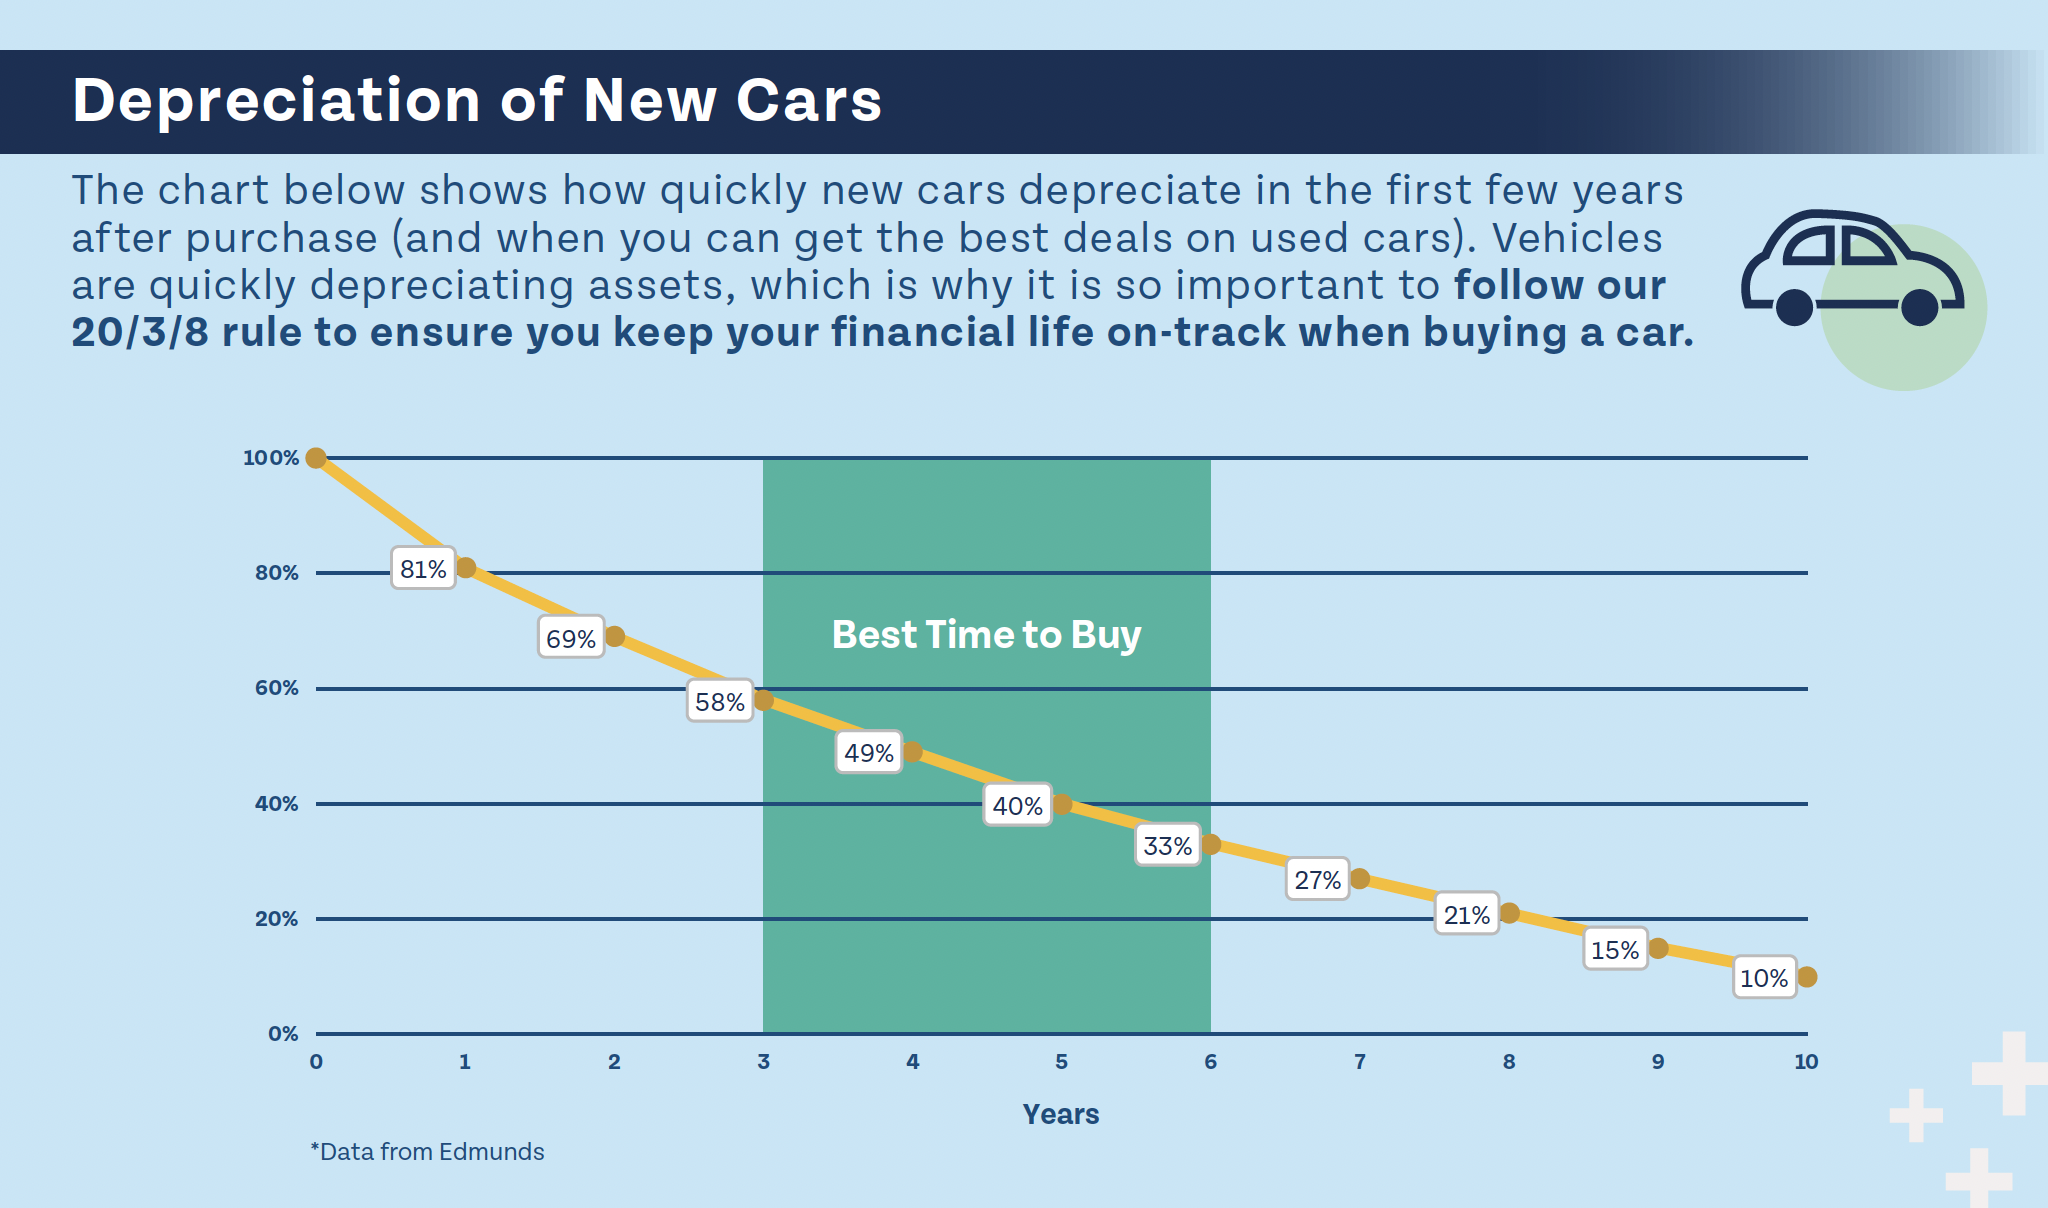
In general, it makes more financial sense to buy a used vehicle rather than a new one. A car loses about 10% of its value the first month of ownership, and depreciation is highest in the first few years after purchasing a vehicle. Therefore, it’s better to let someone else take that depreciation hit and buy a used car that’s at least a couple years old. Look for used cars at least 3-5 years that have lower mileage.
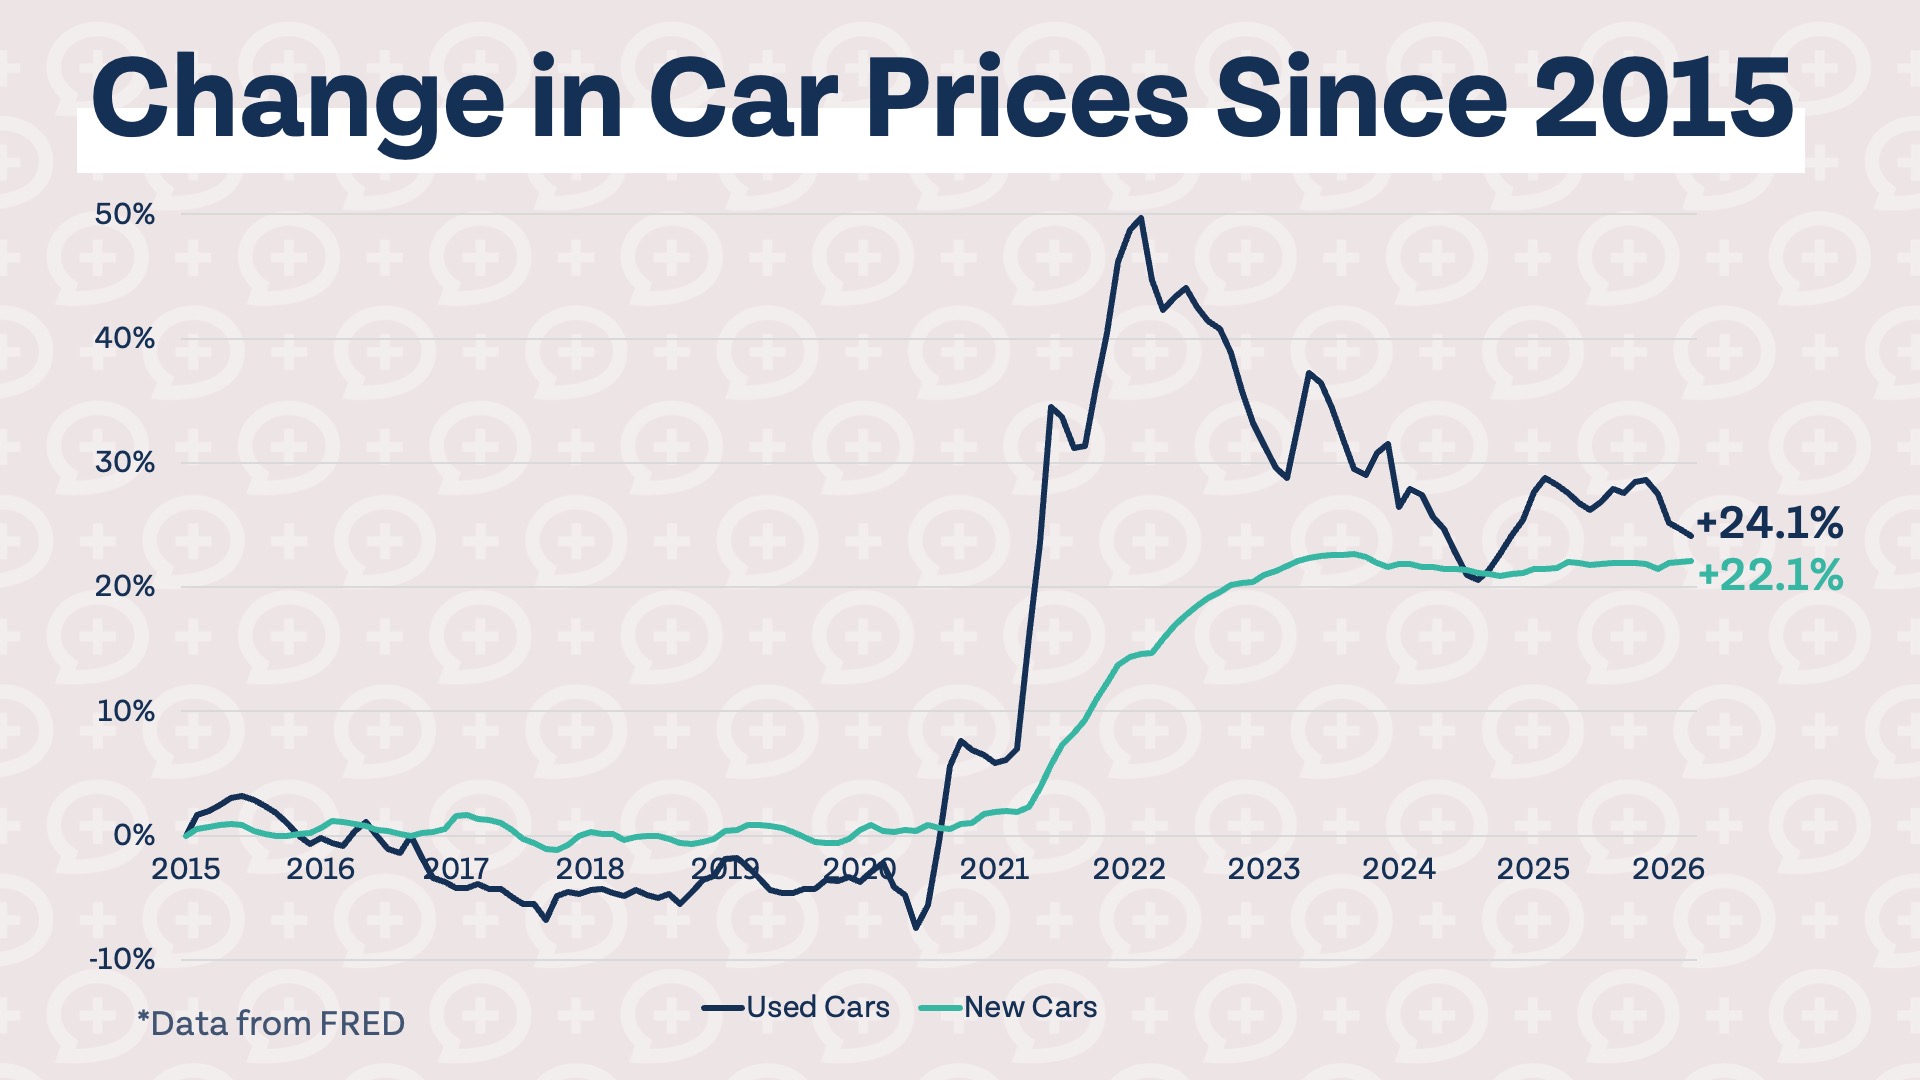
When does it make financial sense to buy a new car? Well, it did a few years ago. As you can see on the chart below, for a brief period of time the price of used cars skyrocketed while new cars rose substantially slower. If you were buying a car in late 2021 or 2022, a new vehicle, if you could find one for MSRP, may have been cheaper than used. Used and new car prices are back in sync now, and it makes more financial sense to buy a used vehicle.
Share image


The chart below shows how quickly new cars depreciate after purchasing, and more importantly, when that depreciation begins to slow and when is the optimal time to purchase a used vehicle. Around years 3 to 6 is the sweet spot. The car is still fairly new with many of the latest features, but still old enough that you are likely saving 40% to 60% or more compared to the cost of a comparable new vehicle.
Share image


How to get the best car loan rate
Copy link to this section: How to get the best car loan rate
Copied the URL to your clipboard!
Copy link to this section: How to get the best car loan rate
Copied the URL to your clipboard!
With a little due diligence and shopping around, you should be able to get a competitive rate on your car loan. The rate on your loan is extremely important. It impacts how much car you can afford, your monthly payment, and the financial burden your vehicle has on your life.
The table below shows current auto loan rates based on your credit score. Aim to get a rate that is at least close to average for your credit, if not lower than average.
| Credit score | Average APR, new car | Average APR, used car |
|---|---|---|
| Superprime (781-850) | 4.41% | 6.29% |
| Prime (661-780) | 6.15% | 8.81% |
| Nonprime (601-660) | 9.71% | 13.93% |
| Subprime (501-600) | 13.52% | 19.10% |
| Deep subprime (300-500) | 16.11% | 21.62% |
Updated October 2026, data from Experian
Where exactly can you find an auto loan with a competitive rate?
1. Credit unions
Credit unions can be a great place for many banking needs, including auto loans. They are known for offering some of the lowest rates on the market and if you have a relationship with a credit union, they should be your first stop when you are shopping around for an auto loan. Even if you don’t have an existing relationship with a credit union, it’s still probably worth getting quotes from at least a couple institutions. Becoming a member of a credit union is usually as simple as depositing a nominal amount of money in a savings account that represents your “share” of the credit union (since they are owned by members).
2. Your local or online bank
If you have a longstanding relationship with a local or online bank, it is worth at least getting an auto loan quote to see what their rates are like. The rate may not be the most competitive, especially if you bank with a traditional brick-and-mortar establishment, but banks may offer competitive rates to get new customers in the door or to keep their most loyal customers happy.
3. Car dealerships
Car dealerships are last on this list because you should get rate quotes from credit unions and banks before talking to the dealership about financing options they offer. Many dealers are able to match or beat rates you get from outside sources, so make sure you bring preapproval letters of the offers you have from other financiers. Dealers often offer promotions that credit unions and banks do not, especially on new vehicles, such as 0% interest for a certain period of time. Even if a dealer isn’t able to give you a better interest rate, they may give you a better deal for financing with them (or one of their preferred lenders).
Check out the full article on how to get the best rate on a car loan.
How to buy a car step-by-step
Copy link to this section: How to buy a car step-by-step
Copied the URL to your clipboard!
Copy link to this section: How to buy a car step-by-step
Copied the URL to your clipboard!
Use this step-by-step breakdown to ensure you are purchasing a car the smart way and aren’t leaving any money on the table.
1. Know your budget
Before you start shopping for a car, you need to know and understand your budget for a car. Your goal in setting a budget shouldn’t be to determine the maximum amount you can spend on a car, but the amount you need to spend to get a reliable vehicle that meets your needs.
Use our car affordability calculator to determine how much car you can afford, based on your income, down payment, and any other car payments you may have.
2. Do your research
Now that you have a budget for your new (to you) car, it’s time to do some research into reliable vehicles that fit within that budget. You may already have some cars in mind. If so, check reliability scores on a website like CarEdge. They factor in average purchase price, expected resale value, and maintenance, repair, and insurance costs. Makers with many highly rated models include Toyota, Honda, Subaru, and Mazda. At the bottom of the list, brands you may want to avoid if you are looking for a good value, include Jeep, Dodge, Chevrolet, and Chrysler.
3. Negotiate with the dealer
Don’t visit a dealer in-person to negotiate a deal on a car. Instead contact dealers by email or phone. At this point you should already know what make and model you are looking for. Find 3-5 dealerships near you (or that are able to deliver to you) that have a car that meets your specifications and pit them against each other.
Be direct with the dealerships, let them know exactly what you are looking for, and that you will be purchasing a car. Get the final out-the-door price in writing before making any decisions.
4. Consider financing even if you can pay cash
As we mentioned above, not everyone should finance a car. If you have the ability to pay for a car in cash, it may still be better for you to finance it. Hear us out: car dealers often offer better deals to those who finance, as dealerships these days can make more money on the loan than they do on the actual car. Because of this, it may make more sense for you to take out a car loan, even when you don’t need to, and pay it off immediately (or as soon as the terms state you can pay it off with no penalty).
If you plan to pay for your car in cash, see if you can save money by using dealer financing and paying your loan off as soon as the terms allow. The savings offered to you on the car may very well dwarf the amount of interest you pay over what should be a very short-lived auto loan.
Total cost of ownership
Copy link to this section: Total cost of ownership
Copied the URL to your clipboard!
Copy link to this section: Total cost of ownership
Copied the URL to your clipboard!
It’s important to look at the full cost of owning a vehicle over time when shopping for a car and not just the sticker price. More reliable vehicles may have a higher upfront cost, but could be significantly cheaper than less reliable vehicles over time when you account for how much you will be expected to spend on maintenance, repairs, and fuel.
Use a website like CarEdge, which we have no affiliation with but just love to use, to compare the total cost of ownership of different vehicles. This ensures you are making apples-to-apples comparisons when you are purchasing a vehicle and not just looking at the sticker price.
Luxury cars and where a car fits in the FOO
Copy link to this section: Luxury cars and where a car fits in the FOO
Copied the URL to your clipboard!
Copy link to this section: Luxury cars and where a car fits in the FOO
Copied the URL to your clipboard!
Not all cars depreciate at the same rate, and luxury vehicles tend to depreciate much faster due to the higher initial cost. If you are buying a luxury vehicle, which includes manufacturers like BMW, Mercedes, Tesla, and more, you should pay for your vehicle same as cash, meaning in less than a year. We’d also like for you to be at Step 8 of the Financial Order of Operations before purchasing a luxury car.
It’s essential to keep the sum of your monthly car payments to no more than 8% of your gross income. This ensures you have room left to spend on housing, other debt, investing, and living expenses. The average monthly payment for a new car is $765, which means the average American with a new car loan is spending nearly 15% of their income on their car loan. With the average loan term for new cars at nearly 6 years, it’s not hard to see why many Americans have trouble saving for the future.
Leasing vs. buying
Copy link to this section: Leasing vs. buying
Copied the URL to your clipboard!
Copy link to this section: Leasing vs. buying
Copied the URL to your clipboard!
Leasing a car instead of purchasing usually doesn’t make financial sense because the cost of the lease is almost always higher than the cost of ownership. However, if you are at Step 8 of the Financial Order of Operations or later, you may wish to lease a vehicle if you plan on upgrading cars frequently and want to avoid the hassle factor of selling a vehicle every couple of years.
It’s important to keep in mind that the decision to lease a car is not usually a smart financial decision on paper, but rather a decision you make when you like the pros of leasing a vehicle – flexibility, always having the latest and greatest features, not having to resell it, and warranty coverage.
Trade-ins and being underwater
Copy link to this section: Trade-ins and being underwater
Copied the URL to your clipboard!
Copy link to this section: Trade-ins and being underwater
Copied the URL to your clipboard!
It’s very important to pay off your car in 3 years or less, and not just because doing so keeps you in the good graces of the 20/3/8 rule. Many cars lose around 20% of their value in the first year alone, and 15% per year more until the 4-5 year mark. If you stretch out your car loan, you could easily end up underwater on your vehicle (owing more than it is worth). Unforeseen events like accidents could also cause you to end up owing tens of thousands of dollars on an asset that is now worth next to nothing.
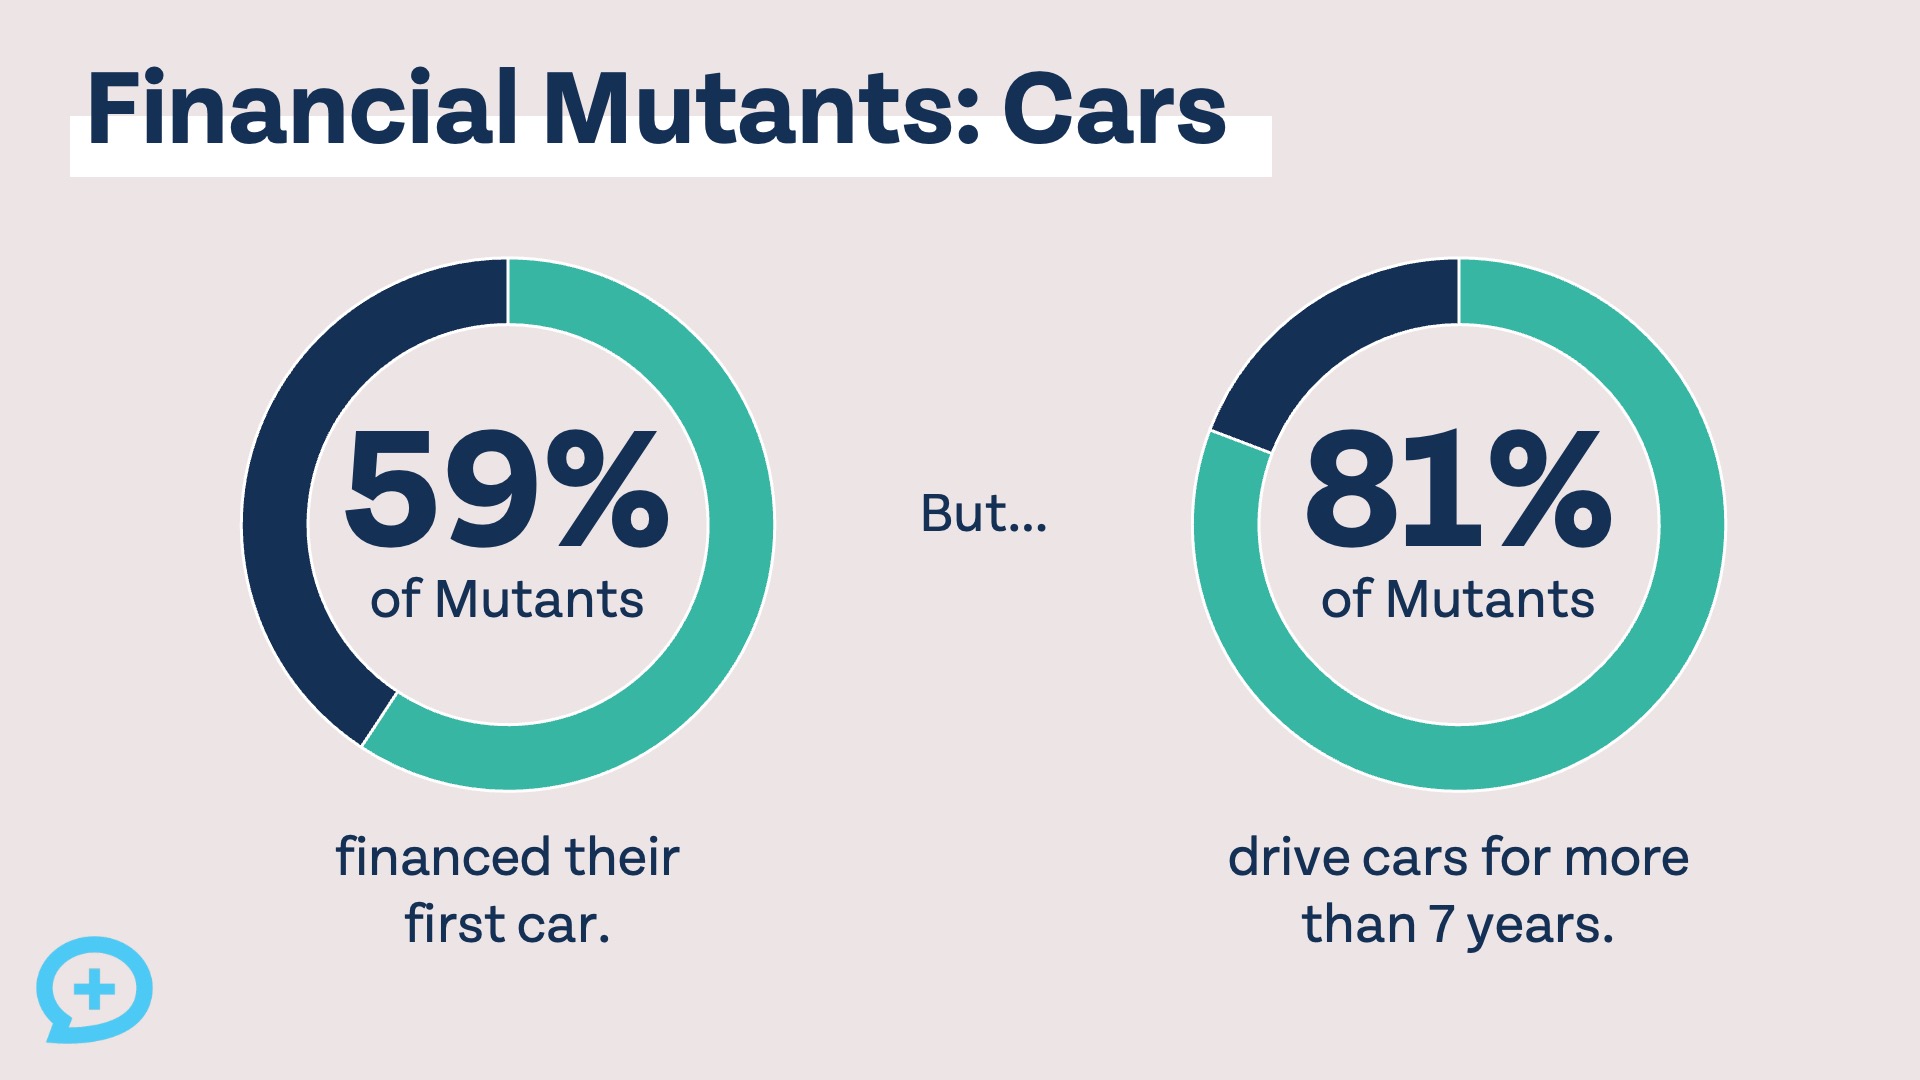
When you buy a car, you need to make sure you are in it for the long haul. Even after your car is paid off, it’s generally good practice to drive it until the wheels fall off. In our annual survey show, we’ve found that, while the majority of Financial Mutants finance their first vehicle, 81% spend 7+ years with the same car.
Share image


How do you buy a car in 2026?
Copy link to this section: How do you buy a car in 2026?
Copied the URL to your clipboard!
Copy link to this section: How do you buy a car in 2026?
Copied the URL to your clipboard!
If you have been waiting to buy a car, you probably feel pretty good right now! Prices for used cars have dropped significantly from their peak around the beginning of 2022, and the cost of a new cars has been relatively flat over the last several years. The following chart shows the change in car prices since 2015, using data from the Federal Reserve.
Share image
Buying a car is a huge financial decision, often second only to buying a house. If you make a bad car buying decision, it could impact your finances for years or even decades. Investing for retirement is exponentially more important than driving an expensive, nice car. No matter what stage of your financial life you find yourself in, you should always be investing more than you are spending on a car.
Needless to say, we really want to help you get this one right. That’s why we created our brand new Car Buying Checklist and additional online resources including a car affordability calculator. Take advantage of these resources to find a car that meets your needs and fits within your budget!
FAQs
Copy link to this section: FAQs
Copied the URL to your clipboard!
Copy link to this section: FAQs
Copied the URL to your clipboard!
Is auto loan interest now tax-free?
With the Working Families Tax Cuts, signed into law in 2025, individuals may deduct auto loan interest paid up to $10,000 per year from 2025 to 2028. The vehicle must be used for personal use and other stipulations apply. The maximum annual deduction is $10,000, available to both itemizers and non-itemizers, and phases out for single taxpayers with MAGI over $100,000, or for married filing jointly taxpayers, $200,000. One very important caveat is final assembly of the vehicle must be done in the United States to qualify.
How much car can I afford on a $25,000 salary?
If you make $25,000 per year, you can afford a $6,848 car, assuming an auto loan term of 3 years, interest rate of 6%, 20% down, and no other car payments. Check out our car affordability calculator to see exactly how much car you can afford based on your exact income and auto loan terms.
How much car can I afford on a $50,000 salary?
If you make $50,000 per year, you can afford a $13,696 car, assuming an auto loan term of 3 years, interest rate of 6%, 20% down, and no other car payments. Check out our car affordability calculator to see exactly how much car you can afford based on your exact income and auto loan terms.
How much car can I afford on a $100,000 salary?
If you make $100,000 per year, you can afford a $27,393 car, assuming an auto loan term of 3 years, interest rate of 6%, 20% down, and no other car payments. Check out our car affordability calculator to see exactly how much car you can afford based on your exact income and auto loan terms.
Is it better to buy new or used?
Financially, it is almost always better to buy a used car than a new car. New vehicles depreciate the most in the first 3-5 years of ownership, so you want to avoid that depreciation if possible by buying a used car.
There’s nothing wrong with buying a new car if you can afford to do so, but keep in mind that it is usually not the financially optimal decision and the best thing to do is shop for a reliable vehicle that’s around 3-5 years old.
Should I lease or buy?
The cost of leasing a car is almost always higher than the cost of purchasing a vehicle. You should only consider leasing a car when the pros – flexibility, always having the latest and greatest features, not having to resell it, and warranty coverage – outweigh the added cost of leasing.
Is 20% down required?
Car down payments are often suggestions instead of requirements if you meet the lender requirements and have a good credit score. However, just because you can put $0 down, doesn’t mean you should. We recommend putting down at least 20% when you purchase a vehicle with financing, which helps soften the depreciation blow in that first year and can ensure you are never underwater on your auto loan.
What credit score do I need for a good rate?
To get the best auto loan rates, you typically need a superprime credit score above 780. However, you can usually still qualify for good rates in the 700s and higher 600s. If your credit score is below 600, what’s known as subprime and deep subprime, you will only be eligible for really high rates (if you qualify at all with certain lenders).
Is now a good time to buy a car?
Car prices have been steady for the last few years, and unlike other inflation indicators, cars have not risen significantly in price. Now is not a bad time to buy a car if you are in the market for a vehicle. We can’t predict the future of car prices, but we can say that it is a much better time to be buying a car now than it was several years ago.
How do I get out of an underwater car loan?
If you are underwater on your car loan, it means you owe more money on the car than it’s worth. To get out of an underwater auto loan, you need to accelerate your repayment and put any extra cashflow towards paying off your car as quickly as possible. An underwater car loan is a ticking time bomb, and if your car were to become inoperable and worthless (due to an accident or mechanical failure), you would still be responsible for the balance of the loan. It may be a good idea to consider full coverage on your vehicle if you are underwater on the loan.