-
▼
-
▼
Private equity is becoming more accessible to everyday investors, and it could eventually show up inside your 401(k) and target-date funds. But how does private equity actually work, and does it deserve a place in your investment portfolio? We respond to Tony Robbins’ claim that private equity has beaten the stock market for 39 straight years and break down what that headline leaves out, including survivorship bias, a low interest rate era, and the wide gap between top and bottom performing managers. We also cover private equity vs. the stock market, illiquidity, leverage, the “2 and 20” fee structure, lack of transparency, diversification, and why new retail access with minimums as low as $2,500 changes the conversation. Plus, we explain where alternative investments could fit within the Financial Order of Operations, why low-cost index funds remain the foundation for most investors, and what to research before putting retirement money into private markets.
Then we answer your live questions. We cover what to teach a workshop of 25 to 35-year-olds about money, with a focus on the Wealth Multiplier, whether Roth 457(b) contributions are better than traditional for a firefighter in the 12% bracket with a pension starting at 54, and whether a couple at 30 with two and a half times their income saved can drop their savings rate from 25% to 15%. Plus, our From the Wings segment weighs in on the 3.6% Social Security increase, AI agents accessing bank accounts, and billionaires gifting shares through Trump accounts. Watch the full episode now, and preorder the Millionaire Mission paperback to get the preorder perks before our November 10th launch!
Do You Actually Need Private Equity to Build Wealth? (0:00)
Bo: Here’s a question. Do you actually need private equity to be successful?
Brian: Brian, I am so excited to talk about this because I feel like we get asked this question a lot, obviously, in the world in which we live and the people with whom we interact. It seems like private equity has been historically and continues to be sort of this hot topic idea of, oh well, this must be what wealthy people do. This must be the secret sauce that if you want to get into the upper crust, the upper echelon of society, you have to be a private equity investor.
What Tony Robbins Claimed About Private Equity (0:36)
Brian: Well, and look, this has been part of the zeitgeist recently, in the last month, because if you want to find a persuasive personality to kind of make something happen, there’s not a bigger name than Tony Robbins. And he was on a podcast recently and he definitively said you pretty much are not going to be successful going forward unless you have a private equity investment. But of course, you need to understand Tony is on the front row of a private equity investment, so you have to kind of realize his thumb’s on the scale to a degree. But it’s still, we ought to at least kind of look at what he said and then give some thoughts.
Bo: Yeah, he said that private equity and private credit have now become a big part of the holy grail of investing, like the thing that you need to be doing. And the reason why this is pertinent for sort of everyday investors is that it sounds like now there’s going to be access to these types of vehicles even inside of your 401k. So, is it legitimate? Is it something you ought to know about? Is it something you ought to participate in? So, here’s what Tony said in this episode of Modern Wisdom with Chris Williamson.
Tony Robbins: In the last 39 years, private equity has outproduced every stock market in the world for 39 straight years. Average private equity, now in this book, we interviewed 13 of the best in the world, right? Average has averaged 15.7% returns. The S&P 500 of those 39 years is 9%. 74% better per year compounded for 39 years. So if you put a million bucks in the S&P, you’re pretty happy right now. You got just under 29 million, 28.7 million. If you put it in basic private equity, it’s $293 million. The same money, same time, 10 times the return. So now the question is how the hell do you get access? Because there’s a big difference between the big boys and the average boy.
Bo: Yeah. So there’s a question, how do you get access? There’s a big difference. Because it lays out a compelling story, Brian, right? Oh, this is amazing. If you would have done this, you’d be better than the S&P. Instead of having $20 million, you’d have $70 million. So, or $200 million. So, certainly private equity must be the answer.
Brian: Well, and look, we’re about to give you some, what if you’ve never heard what is private equity? We give you some definition information, but then I want to go through the pros and cons. But there is something I just want to put a pin in. Tony said 39 straight years. I think that’s a little misstatement because it’s not really 39 straight years. That means every year it outperformed. We’re going to show you there are some chinks in that, that it’s not completely true. Now look, he’s using a lot of the same data we were able to backtrack and back test, and he’s pulling data that, yes, if you pull that time frame, 39 years, average performance, now there’s a big assumption there. ROI is different than time-weighted return, first of all, so cash flows and other things. The other thing that I think you’ve got to think about is that this was a low interest rate period of time, a lot of inefficiencies. I can’t wait to show you all the rest of the answers. So, make sure you stick around so we can actually see if 39 straight years is as legit as Tony made it out.
What Is Private Equity? (3:58)
Bo: But before we get there, let’s talk about, in a nutshell, what is private equity? And generally, investing in private equity, participating in that type of investment, means you’re investing and getting access into something that the general public cannot. A real easy way to think about this is, right now if you wanted to go buy shares of SpaceX, you could go do it. It is publicly traded. It’s out there. You could go buy shares right now. If, however, you wanted to invest in SpaceX a year, two years, three years ago, it was not publicly traded. It was not available to the general public. You would have only been able to get access to that company through some type of private equity investing. And so, it’s different than normal index stock market investing. And this is a loose analogy that we use. We say that investing in private equity is a little bit like horse racing. If you are unfamiliar, you have no idea which horses are likely going to do the best. But if you’re someone who maybe understands the breed, understands the sport, understands the stable, understands the jockeys, perhaps you have some sort of affinity for identifying which of the horses have the highest likelihood of performing well versus the ones that do not perform well. But you have to kind of be in the know to understand that. It’s different from when we tell the average everyday investor to go out and buy a low-cost index fund and you don’t need to know any more than that.
Brian: Well, look, and I want to make sure we’re clear. We’re not against private equity. I think about all the business groups we’re members of, you know, EO and so forth. I mean, a good number of people I was in a group with were bought out by private equity companies. So, that was their exit. We have a lot of clients that actually have companies that were bought out by private equity. We have clients that actually are using private equity to build wealth. So, we’re not against private equity. But there is a big thing that’s about to happen that I want to make sure our audience is very aware of, and this is what Tony’s kind of helping push, is that in the past you had to be an accredited investor. Meaning that a lot of the safeguards to the general public to make sure you’re not a crook and other things were suspended for accredited investors because they assumed you have a high enough net worth, high enough income that you were more advanced. You were exactly an accredited investor, somebody who has enough sophistication. You don’t need the government to protect you. But now we’re about to bring these types of investments down to the general public with as low, as small, an investment as $2,500. That is a big threshold, a big material change that’s about to happen. So let’s transition into pros and cons so I can tell you how this will now change as we bring this into the retail investor.
The Pros and Cons of Private Equity (6:29)
Bo: So when we think about the pros, the benefits of private equity, one was exactly what Tony had laid out. It does have the potential for higher returns. Again, according to Cambridge Associates, private equity has delivered higher long-term returns than public equity markets, particularly when measured over several full market cycles. We’re going to talk about that in a moment, but in general, when you think about people you’ve heard about having success in private equity investments, you hear about these large, multiple, outsized return variations. There’s also, it diversifies your portfolio.
Brian: Look, if you’re buying music catalogs and other things that are, you know, companies that are not out there in the public sphere, yes, these are diversifiers because these types of companies might act in a different way that’s not correlated with the 500 biggest companies in the United States. That’s a pretty cool thing to put in the brochure.
Bo: And then another thing is it gets you private access to exclusive companies. Exactly what it says. It’s private. It’s not available to everyone. You get to own, participate, and be a part of something that other people don’t get to. So naturally, there is some exclusivity associated with it.
Brian: Yeah. And so that’s what, you know, because think about this, the sexy sizzle of you can buy into music catalogs, you can buy into professional sporting franchises, you can buy into companies that are not available because they’re all privately owned. This has some sexy sizzle and, exactly, sounds cool.
Bo: That’s right. Sounds super cool.
Brian: Okay. So that’s why these things are very easy to sell, because you get to do rich people stuff. And I think as people build wealth, they want to do rich people stuff. So now let’s give the cons. The first thing is low liquidity. Look, one of the things that I know a lot of wealth management firms have used these, because, and in a previous firm I worked at, we did a lot of private deals because we love the low liquidity because if you want to protect your relationship, put a lot of your clients in something that they have to hold for seven to 10 years. So it is one of those things, even if you sell your company to a private equity firm, you are locking yourself in till the next cycle that they either recapitalize, sell, or do whatever they’re going to do.
Bo: These are low liquidity events. And this is not like the S&P 500 where you can come in and out as fast and as often as you want because it’s very liquid. These things, you’re kind of locked in. In addition to that, they’re often very expensive. There are usually excessive fees and costs to them. A very common metric is what’s known as a 2 and 20 fee structure, where they’ll take a 2% annual management fee and then 20% of the profits. And as you can imagine, that can become very, very expensive over a long period of time. Now, the managers will tell you, “No, no, we’re making so much money. It’s okay. We’re going to participate in that with you.” But for the ones that don’t make money, for the ones that don’t perform outsized, they become very, very, very expensive.
Brian: Well, that’s why I want to be clear. 2 and 20. You were packaging this, like I said, the sexy sizzle. You were packaging that you had access, as an advisor, to companies, portfolios, and other things that other people couldn’t get into. So you were catching a huge premium for how exclusive you were and how good. That’s why it’s shooting fish in a barrel, because you have access to something that the general public doesn’t, and that’s what the brochure has. If we bring this thing down to retail investors and we’re still strapping in for 2 and 20, are you really getting the premium that in the past that exclusive product or the manager who had access to these types of things provided? I start to think it falls apart to a degree, and especially when you think about the packaging of leverage and interest rates and other things. This starts to feel like more of a product that selling more of could be profitable for the people selling it, versus, I don’t know if I think the market matches what is being put together.
Bo: And then another piece of private equity, oftentimes there’s a giant lack of transparency. You don’t actually know exactly what you’re investing in, or even if you know what you’re investing in, you don’t know exactly how it’s doing. A lot of private equity firms and the companies they own can disguise losses. They can inflate or adjust valuations. And investors often don’t know that. They don’t know, okay, when am I going to get my money out? When am I going to get my return of principal? When am I going to know what’s the next thing happening in this? You kind of just put your money in, close your eyes, hold on, and hope for a positive outcome. So when you think about all the cons, even though it sounds super cool to have these higher returns and this diversity and this exclusive access, in reality, private equity is fairly complicated, both in terms of how it operates as well as how you do it well as a normal everyday investor. So let’s talk about should you invest in private equity, and we’re going to get into the performance of this.
Does Private Equity Really Beat the S&P 500? (11:21)
Brian: The first thing, look, here’s the reality. When you use the quotes of 39 years of best performance, a lot of times people are using Cambridge results for private equity and so forth. A lot of these numbers, I want people to realize, have survivorship bias, you know, because the companies that have been around the longest, yes, are the most successful. Those are the numbers you want. It’s kind of like, you think about now, Berkshire Hathaway is a public company, but we all want to invest like Warren Buffett. Well, there are a lot of private equity companies. You want to invest like these best-performing funds. And that’s why there’s a huge spread, and even Tony said it at the end, between the top-performing versus the lowest-performing. And the survivorship bias in the long term is toward those top-performing funds. And this is what I want to draw attention to. Tony said they beat for 39 straight years. That word “straight” is doing a lot of lifting. It’s probably wrong, because if you look at what has happened over the last 10 years, you’re like, “Wait a minute. I must not understand the key here.” Because if you look at Cambridge, that’s the private equity index versus the S&P 500. That green line is the S&P. That green looks like it’s actually doing better over the last year, the last three years, over the last five years. Tony said 39 straight years. So obviously he cherry-picked the data to show. And now realize 39 years is doing a lot of heavy lifting, because go ahead and open it up to the 39. You know, if you go beyond, yes, now you look at this and here’s the blue, it did so well. But ask yourself, past performance, what does the SEC always tell us? Past performance is not indicative of future performance. We are at all-time high interest rates on deals right now. Do you think comparing interest rates at these high levels of what’s going on is the same as where it was when we were at a zero interest rate environment, where everybody was using leverage to make deals work and to kind of grease the skids? I would tell you, I don’t know, I would be more nervous about what this is going forward than just saying, hey, the last 39 years it was the best performing.
Bo: Well, and I think maybe even the more telling statistic is if you look at the gap between top-performing managers in the top quartile and bottom-performing managers when you look at private equity returns, that gap is about 19% from the top quartile of managers to the bottom quartile. When you compare that to actively managed mutual funds, so people that are buying inside of public markets and trading public market equities, the gap between the top quartile and bottom quartile of active managers is something like 2.9%. So it’s a much wider margin. Yes, the ones who are good and are successful at private equity tend to do very, very well in that. But I would not say that by and large that’s all private equity investors. And so the question that you have to ask yourself is, all right, how do I know if I should be investing in private equity? How do I know if that is a reasonable asset class for me to begin allocating to?
Should You Invest in Private Equity? (14:36)
Brian: Yeah. So, let’s talk about this. So, like I said, we’re not against private equity. I just think that there’s a time and place. Just like we tell you, hey, if you’re going to go into doing real estate investing, we love real estate investing, too. We typically want you to have your financial foundation underneath you first. That’s why this is a step eight activity. That’s why we say wait until after step seven, meaning you’ve saved and invested 25% of your gross income before you’re adding private equity. This is kind of like the cherry and whipped cream on top of your sundae of portfolio building. This is not where you need to start your journey.
Bo: And then this is kind of my hobby horse when it comes to private equity. I want you to do your research. I get so frustrated when people come and say, okay, but I’m ready to start investing. I want to go invest in private equity. I’m like, okay, great. What are you thinking? Like, I just told you, I don’t want to go invest in private equity. I’m like, “No, no, no. If you know someone, maybe you have a relative, a friend, a colleague who has some sort of insight into this startup they’re doing or this thing and you want to support them and you have capital, you can do that.” Those types of private equity investments make all the sense in the world because there’s some familiarity with it. If you’re just trying to go out there and you’re painting with a broad brush, I just want to go pick some private equity investments that are going to do well, I worry that you’ve already lost the plot. Because if you’re going to deploy your money and you’re going to saddle yourself with lack of transparency, lack of liquidity, excessive fees, you need to have some sort of deeper familiarity and understanding with where exactly you’re deploying your capital. So I would argue before you do this, actually do your research. Do you understand, if you’re going to be participating in a private equity fund with some sort of general partner, do you understand how they performed? How much money do they have in it? What’s their team experience? What’s their track record? Why do you believe that this investment is the one that makes sense for you to put your capital into? And is the opportunity cost worth it? Do I genuinely believe that by locking my capital up over in this thing, it’s going to outperform what I could do if I was just over here buying low-cost index funds with full transparency and full liquidity?
Brian: Well, and I’ll kind of close it out with, I think everybody comes out in this new modern world where, you know, you’re red, you’re blue, you’re this. We like binary things where you’re on this side or this side. And it’s always either/or. And I’m here to tell you the real world, the Realsville that I live in, not the brochure, it’s more of an and. It’s not an either/or. And I don’t like how Tony pitted private equity versus the S&P 500. The reality is both are tools in your wealth-building journey. Don’t sleep on the fact that when you’re getting your employer’s free money in step number two of the Financial Order of Operations, or funding your Roth IRA, or fully funding and maxing out your employer 401k, the S&P, the total market indexes, those things are going to crush it for you. But yeah, when you get to step eight, more mature, just like you might add real estate investing, you can consider private equity. It’s not either/or, it’s and.
Bo: And that’s why I need you to make sure this makes sense for you. Just because you can, just because they lower the threshold to $2,500 and let it go into your 401k, doesn’t mean you should. Make sure it fits in at the right time in the right place for your wealth management journey. And one of the best ways to figure that out is, do you know where you are in the Financial Order of Operations? Have you actually walked through understanding what step you’re on? If you don’t have your free copy, you can go to moneyguy.com/resources and download your free copy to make sure, before you get distracted or before you take your eye off the ball on one of these other sexy type investments, you make sure that you have the basics covered. If you can do it that way, we believe that that is indeed a better way to do money.
Wrapping Up the Private Equity Discussion (18:16)
Bo: Brian, I love that we get to sit here. I love that we get to respond to Tony Robbins. We get to answer the things that he says that maybe aren’t exactly spot-on. But more than that, I love that we can sit here and we can answer your questions every…
Brian: We stuck the landing. Six minutes, by the way. Yeah, that’s what, in pre-show prep, after the first pre-show prep, they were like, “Hey, can y’all do this in the next six or seven minutes so we don’t get bogged down in it?” And here we are 18 minutes, close to 19 minutes later.
Bo: You know how he said like, “I want to add a little bit to the pros and cons.” As soon as he did that, I was like, “All right, well, six minutes gone. That’s all right.” That’s fine.
Brian: I’m sorry.
Bo: Hey, that’s fine. There’s no time limit here.
Brian: There’s no time limit. I’m not designed for short-form content.
Bo: But here’s the thing. Our folks do love that not only do we get to wax eloquently about the things that we’re passionate about, we also get to weigh in on your questions. We get to speak to the things that you guys are genuinely curious about. So, if you have a question you want our take on, you want to ask us something about your financial life or just about finances in general, make sure that you get them in the chat right now. We have the team out in the wings collecting those questions and our goal is, with the time that we have left, to load you guys up.
Rebie: I thought you did great.
Brian: Well, and by the way, Tony Robbins, look, if he wants to come on the show, we’d love to have Tony come on at some point. So, Tony, come on.
Bo: I hope you make sense. Hey, because he’s written other investment books that were actually pretty good. This one just felt a little self-serving. And look, I get it, but I just want to make sure we shot our audience straight so you knew what to do with your next dollar.
Rebie: He has sat in so many rooms with billionaires. You think you could come on and do an episode of like Making a Billionaire? That would be pretty cool. Just get some insights.
Brian: I think that’d be nice. I love it. Probably have to wait for the next book. It’s not going to be the holy grail book. Billionaire Mission.
Rebie: All right. Green Ivy 314 has a question. Are you ready?
Bo: Did you just break something?
Rebie: I don’t, there’s stuff all under my feet, cords. And I just, I have big long legs and they don’t go with cords. Keep going. I’m sorry.
Bo: It all looks okay from here. I think you’re doing good.
Q&A: What Should You Teach 25 to 35-Year-Olds About Money? (20:29)
Rebie: All right. Question says,
Brian: Goes black.
Rebie: That would be my luck, I’ll unplug it with my feet. “I’ve become the money lady at work and yearly I have a workshop for my coworkers, 25 to 35 age group. What’s going on in the financial world that I can include this year? Any other suggestions? If you had the ear of every 25 to 35-year-old in your company, what would you say?”
Bo: Well, here, I think as a financial educator, Green Ivy, I’d like to give you a cautionary warning. So often in the personal finance space, there becomes this idea of, oh, I’ve said that thing before. I need to find something different. I need to say something. I talked about this last year. Well, now I need to go talk about private equity. I need to go talk about Bitcoin a couple of years ago. I need to go talk about NFTs or I need to… There is nothing wrong with talking about the same stuff that you talked about last year because oftentimes we need to be reminded because we have very, very short memories both as human beings and as investors. So if I were talking to an entire group of 25 to 35-year-olds, 24 to 35-year-olds, the number one thing that I would do is I would drive home the idea and concept of the Wealth Multiplier. If you don’t have a free copy, go to moneyguy.com/resources. Feel free to use our resource. Feel free to even pull up our website and use our tool there and show these 24 to 35-year-olds that every dollar that they can walk away from, every dollar they can sacrifice, every dollar they can defer for the future has the unbelievable opportunity to turn into massive wealth for them later in life, because they need to hear that. They need to hear it at 24 and at 25 and at 26 and at 27 and so on and so on and so on. So if I were trying to get one thing across to them, it would be to grasp that idea, because then if you can grasp that idea, then you get to start talking about X’s and O’s. Now let me talk about Roth IRAs. Let me talk about employer match. Let me talk about high interest debt. Then the Financial Order of Operations can be the thing where you fill in all the other pieces. But you have to start, in my opinion, with the discipline piece.
Brian: Yeah. Yeah, I was going to say, look, because the way, money lady, Green Ivy, I love that. Because I like Green Ivy the money lady. She presented it in a way that she’s looking for a current event, kind of a headline with some sizzle to it so she can get people to show up. That’s great if you want to find something that’s clickable to put on the banner or the email subject line to get as many people to sign up. But be careful, because behavior is more valuable than current events. I mean, I feel like the majority of what we’re trying to do with our audience is help them to see that they can get distracted with the fear, the greed that the news media and everybody’s putting out there, when really you need to be kind of zooming out and looking at what are you going to do with your next dollar. With your employer match, are you maxing out? Are you paying down the high interest debt? Are you building up the emergency reserves, so in case on a Tuesday things don’t work out like they’re supposed to with a layoff or some other crazy thing that comes to your life? And then how does all the tax-free stuff like Roth IRAs, health savings accounts, and then maxing out the employer plan, those are the things that I think are powerful, if you want to then sprinkle into the presentation some of the behavioral stuff to protect people. Like, I always find most people are new to investing, the first time the stock market gets beat up, all the behavioral goodwill that we’ve built up by showing the FOO and so forth goes out the window because they freak out, you know, because the Wealth Multiplier doesn’t work unless you keep the money invested for the 20-plus years. So, I always tell people, we did it, we’ve done several episodes. We even have one in the works because I’ve been working with the writers on shaping it with a case study on the best and worst investors, and you find out that everybody’s going to go through a market downturn. And if you can see, we showed, if you go through like the dot… we’ve done content where we show a slide of the headlines that are so scary, but then if you, you know, stayed invested, yes, you lost, you know, 25, 30%, but if you stayed the course, you made it all back and then some, because bull markets are so much bigger than bear markets. That’s what I think it’s okay to sprinkle some of those things in, because you can inoculate your people to not be so emotional, because your emotions go against the discipline and the behaviors that create success over the long term.
Bo: Can I tell you one other thing that I would mention specifically to a group of 25 to… 24 to 35-year-olds? If they go to moneyguy.com/millionairemission, there is a brand new softback version of the book coming out. This is a great book to start with for someone who’s just now wanting to get excited, wanting to get introduced to personal finance, and they have this idea that one day I want to be a millionaire. One day I want to be financially independent. It’s a great tool and resource for young folks to catch that fire of making sound financial decisions. Brian, did you know that there are only two more weeks for people to pre-order that book and get our perks? Isn’t that crazy?
Brian: Yeah, I know. It is. And look, I do. By the way, I’m still reading the comments on Amazon. Please go out there and put a new comment in, because one of the most recent ones was some guy in England who said, “It’s too basic.” I’m like, “You’re not even in the United States. Don’t leave me a comment from, you know, another country.” What? It just breaks my heart. And then there’s another one that’s on there that’s a negative review because Amazon ripped up his package, and so he put a one star because the book showed up like a dog ate it. And I’m like, that’s not what reviews are for. That’s where you go to customer service and fix it. So, but I am reading the reviews and you guys are awesome, because this thing, you know, that’s why I love that I got another bite at the apple to even fine-tune it even more, to improve the case studies, tell a few more stories. You realize how rare it is for your publisher to be so impressed with the first series. They said, “Hey, as it’s coming out to paperback, we’re going to give you permission. Go do more to it. If you want to improve it,” and that made me so happy because the first book was good. But it was taken from me. You know, they’re like, “Brian, quit making changes. We have to go to press with it.” This one, I fully got to have a full relationship with it and say goodbye. And it just felt so much healthier. It really did.
Bo: So weird.
Brian: I know, it is weird.
Rebie: I’m getting a bunch of questions here.
Brian: I let it grow up completely.
Bo: You know, because this is your baby.
Brian: It’s just, this version got to fully develop, whereas the other one was kind of ripped from my arms at some point.
Bo: That’s even worse. Terrifying and tragic.
Brian: Let’s get out of my analogy. These analogies are horrible.
Rebie: I was going to say, this is the problem. Are you seeing that question that keeps coming through? “Hey, what are the pre-order perks? What are the pre-order perks? Are there pre-order perks?”
What Are the Millionaire Mission Preorder Perks? (27:16)
Rebie: You read my mind. There are. And so if you order today, between today and launch day, November 10th, you immediately get access to our private Discord channel in the Moneyverse and a special Mission Crew role. And then every pre-order gets a ticket to Brian’s Book Club, which, I am very excited and happy to announce, Brian’s Book Club is going to have an exclusive Q&A live stream with Brian and the gang, of course, and an exclusive ask me anything with Brian in the Moneyverse Discord. And yes, if you are in the Moneyverse, you know that there’s been a lot of speculation over what Brian’s username is, but he has agreed to hang up his hat as a lurker and reveal his username and actually chat with us in an ask me anything. So, if you want to know when those are going to happen, they will be happening after the book is released, obviously, and you will be the first to know if you get in that Discord channel and on the pre-order list. To do that, go to moneyguy.com/millionairemission to order from your favorite retailer and to learn how to cash in on those pre-order perks.
Brian: And then one last thing, and then I want to get to more questions, is that if you noticed on a lot of the sites, they haven’t set the full price. There’s an asterisk usually on most of them. So I think, you know, usually with paperbacks, the price comes down pretty quickly. So, I think you’re going to see, please go ahead and do the pre-order, because if you notice in the asterisk, it says they’re going to charge you the actual price that they settle on at the release date. So, I don’t think that listed price is actually what everybody’s going to pay. So, read through. I know we’re all financial mutants, and that’s why I want to make sure you go read the asterisks. I’m doing the heavy lift for you so you can make sure you get the best deal possible.
Bo: Are you going to be in the ask anything with Brian? Like, will you be there with him while he’s doing it?
Rebie: Me and Marketing Mutant will be there. I’m just, so you know, because our community is like, “Hey Brian, tell us the things that are happening by the end of the year that we’re not supposed to know about,” or “Hey, tell us about, you know, what…” I mean, I want to make sure, because if we fully leave him unattended, he…
Brian: Whenever we don’t tell y’all something, it literally bothers me. I’m like, they need to know. We need to tell them. We want them to know. Say what the thing is. I had a client meeting yesterday and I love these clients, but I told them something I shouldn’t have, and now every meeting they’re like, “So when is that happening?” And I’m like, gosh, I should have never told them, because I do want to do it. But it’s just, Rebie is going to beat me up because we have so many other things on the plate that I want to make this thing happen, but we’ve got to get through two.
Rebie: Maybe someday I’ll be the girl who doesn’t want to beat you guys. Say no. I always have to play that role in these conversations. All right, let’s get back to some financial questions. That was good stuff though. Trey is up next.
Q&A: Roth vs. Traditional 457(b) with a Pension (29:56)
Rebie: Are you ready?
Brian: Mhm.
Rebie: “Firefighter, 38, in the 12% tax bracket.”
Brian: Okay.
Rebie: “Pension starts at 54 and will fill lower tax brackets in retirement. Does this make Roth 457(b) contributions better than traditional today?”
Bo: Almost certainly. Again, we can’t give you full financial advice, but you’re in this amazing spot. You know, firefighters, what’s interesting with a lot of firefighters, my father was also a firefighter, they do this thing where a lot of their shifts are like 24 hours on, 48 hours off. So they do this thing where, in that 48 hours that they’re off, they begin finding what’s their next career going to be or what’s their side hustle going to be or what’s their side gig going to be, and it creates this really interesting opportunity where you have access to this 457 where you can start saving. But even if you do have some sort of side gig or some other thing that you’re doing, you actually have this other means and mechanism that you can begin saving on that side. It’s a really interesting thing. But if you look at where you are from an income tax standpoint, you’re already in the 12% bracket and you’re not filling that up. I would argue that following our rule of thumb, where if you add your marginal federal rate and marginal state rate and the combined of those is below 25%, there’s a really, really good chance that Roth is going to be a wonderful option for you. So, doing Roth 457 contributions may very well indeed be more valuable than doing traditional contributions, but you want to make sure you review the plan because there are some unique things when you contribute to a Roth 457 as opposed to a normal 457 in terms of when you can access and what portions of the dollars you can access. So long as you make sure that you understand that when you get to age 54, 55 and the pension starts, you will be sitting pretty, and hopefully you can let those dollars even continue to grow above and beyond that point.
Brian: So give some clarification on that, in the fact that, because normal 457s, the great thing is they don’t have early withdrawal penalties.
Bo: That’s right.
Brian: And, you know, firefighters, since they do retire typically well below like 65, is there any issue with it being Roth versus traditional and early access?
Bo: Yeah. When it comes to Roth 457 contributions, those earnings and stuff have to be in there until you get to 59 and a half. You don’t get to pull those early in the same way that you do traditional. So there’s a chance that when you look at pots of money inside of your plan, they’ll be bifurcated. You won’t have access to all of it early. But if you have the pension starting, hopefully your pension will satisfy your living needs and you can let those Roth dollars continue to grow well into retirement.
Brian: Does it allow you to make withdrawals, and then do you have to prorate it, or can you take out your basis, your contributions?
Bo: That’s a great question, Brian. So, these are, by the way, this is why it depends, because you have to go read the plan documents.
Brian: Exactly. And that’s what, look, and I’m not, that’s why I tell you things can get, even on a great opportunity like this where it’s pretty much a no-brainer, go do the Roth. You just need to begin with the end in mind, is that even something that seems so valuable, you have to think about how you’re going to use this money and then the complexities that will come, and actually go do the homework of reading those documents.
Rebie: Love it. Next question.
Bo: I mean, you know, that’s the problem with a live show. We get into the details and it gets very hairy very quickly. I’m trying to remember, because again, there’s just a lot, you know, we were hanging out with Jasmine last week and there’s a lot of tax stuff up here, but some of it, ah, some of it doesn’t stick. Even we have to kind of revamp and refamiliarize ourselves on specific esoteric rules. I don’t remember them all all the time.
Brian: Yeah, and by the way, I want the person who caught the comment that Bo made. I didn’t even catch it in real time and I thought it was great. You were talking about code section ID-10-T.
Bo: No, tell me. I made a reference to code section ID-10-T in the tax code and there were a handful of folks in the comments.
Q&A: Should Your Forever Home Count Toward Your Net Worth? (33:38)
Brian: His brain works. Do you see this? This is why God really does have favorites, because I mean, he should not be able to do all this and make jokes that go that layer deeper that I didn’t even catch in real time. So well played.
Bo: Oh, thanks, buddy.
Rebie: Megan’s question is up next. Okay. It says, “If we’re building our forever home, then we will never sell. Do we have to include it on our net worth? It seems misleading.” So, talk about how you include homes on your net worth statement.
Brian: And what, Megan, we get in trouble for this one, because we have shared, and nobody likes this, because you know what putting your personal residence at full fair market value does? Especially after we go through a period where housing and real estate went up 50% in a three-year period. Everybody just loves how frothy that makes their net worth look. The problem is that when you’re looking at what you’re going to actually live off of during retirement, this might give you a false sense of what you have. So Bo and I, we did this before 2020, by the way. We’ve been saying this for years and taking arrows from people, but I think it holds. This is once again why we say what we do. We do it more as an accounting concept of it is the lower of cost or market, and cost, by the way, includes your improvements. So whatever you paid for the house plus whatever you put into the house, that’s what you put it on your net worth statement for. People hate that. But I think what it does is it lets you see, when you do your annual net worth statement, what do you really have for retirement. Now look, if you ever relocate or move and downsize, that money shows up on your net worth statement once that transaction happens, but we like being more conservative with what shows up on that net worth statement. So you actually know, am I legitimately a seven-figure retiree, or am I a person that’s counting on this runup in my personal residence that I’m sleeping in at night?
Bo: Yeah, I want to tell you, Megan, oh yeah, yeah, if you want to leave your personal residence off because it’s a use asset, you don’t have to include it on your net worth statement. Because again, you don’t plan on selling it. That’s fine. But if there’s debt, that’s the thing that I worry about. If you have a big mortgage on this, let’s say that you’re building your dream home and it’s $2 million and you have $1.8 million of debt on it and you’re like, “Oh, it’s my forever home. I’m just going to ignore that.” I would want to know, when I look at my balance sheet, if I’ve got a $1.8 million matzo ball right there, because one of the things that I need to be doing is paying down that debt, getting that off my balance sheet by the time I get to financial independence. So, I think, my opinion, you should still include it. I love the idea, just like Brian said, of including it at cost plus improvements. Not because you’re going to be misleading, not because you’re going to inflate the value of the home, but because then you’re going to have a realistic idea of what behaviors am I executing to impact my net worth. And the two things that should be happening: I’m saving, saving, saving, so my liquid investments are going up, and I’m also continuing to pay down my debt, so my liabilities are going down. If both of those things are happening, my net worth should be growing. And I think if you don’t get crazy with the valuation of the home, it’s not going to be misleading.
From the Wings: Financial News or Noise? (36:45)
Rebie: All right, grab your thumbs up, thumbs down paddles because we’re going to play From the Wings. I’m going to read a few headlines that are going on right now in the financial world and Brian and Bo are going to give us thumbs up, this is news and we should pay attention to it, or thumbs down, this is noise and we should move on with our life. So, are you ready for the first headline? From the Wall Street Journal, “Inflation jump will push Social Security benefits up 3.6%.” All right. You both said this is news. Why?
Brian: I mean, if you’re close to retirement, you want to build that into your assumptions because a lot of pensions don’t have cost of living adjustments, but Social Security does. So, if it’s part of what your cash flow is built off of, it makes sense. Now, if you’re somebody who’s watching this and you’re 25 years old, it probably doesn’t mean as much to you.
Bo: Yeah, I was going to say the same thing. Most people that are depending on, what was the stat, 60% of Americans cite Social Security as their primary source of retirement income, or 60% of retirees, not Americans. And so, that’s a really interesting thing. This is a pretty significant bump for a lot of people, especially as we’ve seen cost of goods and all that stuff increasing. So, I think it is newsworthy because I think it affects a lot of Americans. One thing that I would do, and I’d encourage you guys to do personally if you’re doing your own projections, we always try to model Social Security at a very slow growth rate. So like, we might model it at a 1%, 1.5% increase so that when we see these closer to historic inflation rates, it actually bolsters the plan a little bit. Just that little nugget for free.
Rebie: News from CBS News: “AI agents are roaming around consumers’ bank accounts and banks aren’t happy about it.” Well, I mean, oh, we got some disagreement. Bo says it’s news. Brian says it’s noise. Why?
Bo: That sounds terrifying. That sounds bad to me. I don’t know if it’s true or what. That’s why it sounds bad.
Brian: No, here’s the qualifier. People are choosing to use agents to get into accounts. Whereas that headline makes it seem like there’s these AI bots lurking around, like, “Hey, come over here, kid. Let me get into your account.” That’s just not the way this is going on. A lot of people are using agents, whether it’s Claude, Grok bots, and other things, and they’re giving their user ID and password. And yes, the banks don’t like it, but that headline makes it seem like it’s an after-school special with these nefarious “I Am Robot” robots out there trying to get into your bank accounts.
Bo: I think it’s newsworthy only because cybersecurity has already been this very difficult thing. And in my opinion, you write this in pencil, it’s only going to get worse and worse and worse and harder and harder and harder to make sure we’re protected. Now that we even have, like, perhaps there are nefarious agents out there doing something, and maybe there’s an AI agent that gets access to something, not even because you intended for it to, but because of some unintended consequence. I do think that we all as consumers have to be even more diligent in terms of how we’re securing our accounts, how we’re making sure we stay updated on transactions that are happening in our accounts, how we’re adding multifactor authentication, all these different things. Now, I just think this is an example, even though it sounds like, you know, it makes it sound like Terminator or Maximum, you remember Maximum Overdrive? You remember that movie? Do you remember that movie? You don’t remember that one. Even though it’s making it sound like Maximum Overdrive, I think that we as consumers, as financial users, have to stay super diligent to keep ourselves and our stuff protected. By the way, go freeze your credit, too.
Brian: I will tell you, the phishing things are getting better and better. We had one come through the office, internal chain, today. Really, really good. Guys, if you’re not hovering over to see who’s sending these emails, and at some point, I’m sure they’re going to figure out easy ways to mask that as well. Just be very careful. That’s why probably a good defense is also just going out there and locking your stuff down. Whether it’s multifactor, whether it’s freezing your credit, be on offense for your defense so that you know that the crooks, even if they get your stuff, can’t do much with it.
Rebie: Well said. All right. “Musk plans to gift SpaceX shares to kids through Trump accounts.” That’s from Bloomberg.
Brian: Oh, yeah.
Rebie: All right. You both said it’s news.
Brian: Well, look, this is not just an Elon Musk thing. Now, look, I’m curious to see when Elon does this because, look, Elon makes big, big announcements, splashy announcements, but there is precedent for this already. I mean, if y’all don’t know, if y’all saw Michael Dell and his wife put, was it, $6.5 billion, and they put it out there to go into these Trump accounts to be administered through the Trump accounts. This is a pretty exciting thing. It’s one thing because these billionaires are all coming out and now saying that they want to pay it forward. And man oh man, we’ve been talking about the Wealth Multiplier, you know, for babies, and the fact that, you know, every dollar is worth $647 for a brand new baby. And for these billionaires to now be coming out and saying, “Hey, we’re going to go start giving money to the next generation directly.” Do you know how awesome that is? I mean, you think about what could happen. I don’t care what you think about President Trump, what you think about Elon Musk or any of these other billionaires that are doing it. This is a good thing for the long term if we start setting this stuff up, because that’s one of the things I’ve often felt like, if you looked at what we put into Social Security. And look, I’m the guy that, when President Bush back in 2000 said we ought to privatize a small portion of Social Security for the younger generation, I was, you have no idea, younger version of me in 2000 was like, please, please, please, please, please. Here we are 25, 26 years in the future and you back test what would have happened and you go, man, somebody is finally doing the experiment to show, why do we waste so much money and not build for the younger generation to let them see the power of compounding interest? This is exciting. I’m sorry to grandstand.
Rebie: No, no. I hope it, it’s news not because I think, like, I hope he does it. Logistically, I wonder, I want to know how it’ll play out. Like, who counts as a kid? Is it just babies, or like, you know, I got three kids in my household that would love some SpaceX. You know what I mean?
Bo: Yeah. I mean, there’s going to be, like, with the Michael Dell thing, it was under 10.
Brian: I think so. Something like that.
Rebie: But I was curious, how much is one share of SpaceX?
Bo: I think right now it’s like 150 bucks a share, isn’t it?
Rebie: Yeah. Right around there. But it’s like a lottery ticket. It’s not about what it’s worth today. It’s about what it could be worth. You know what I mean?
Brian: Yeah, I mean, 88 times over… $149.69. I just nailed it within 31 cents. Come on.
Bo: But I think it’s awesome. I think it’d be a wonderful thing. And what a great conversation starter to have with your kids. Maybe $150 isn’t going to change their financial life, but it allows them to understand. Hey, like, if I was reading my little boy, his name is Stone, if I was reading Stone a book about rockets and spaceships and astronauts, do you know how cool it would be for me to tell Stone, “Hey, by the way, bud, you own a rocket company”? And like, think about, just because I’m beginning to introduce that idea to my 11-year-old, that we’re going to start buying stocks of companies, and I’m trying to ask her to think about what companies would you like to be an owner of. These are really fun conversations to get to have at a very early age. And the earlier our kids get that, the more valuable it can be over the long term.
Brian: I think about my daughter when she started working and we opened up those custodial Roth IRAs. I thought it was fun when those statements come in monthly and you review and you say, “Look, you made $35 this month.” And you say, “How many hours would you have had to work to get $35?” And then I could see the light bulb go off in her head. It’s like, “Oh, wait. There’s another way for me to use my labor and time to go buy something that now will replace me having to use my labor and time.” That’s the powerful concept. We start that young enough and people start thinking about how you own things to replace you having to work through labor, it could be transformational for the next generation.
Bo: Yep.
Rebie: All right. Good stuff. And last but not least, “Gentle Giant Backpack declared winner of Alaska’s Fat Bear Week.” NBC News says, “Oh, the bear’s name is Backpack.” So, I believe we have a photo of Backpack and it says, “After a week of fierce competition, Backpack emerged victorious as Fat Bear Week champion, the heftiest bear of Alaska’s Katmai National Park and Preserve.” So, he’s the big, big winner.
Brian: It’s a lot of picnic baskets.
Bo: Would not want him. That’s pretty good doing that.
Rebie: That’s pretty good.
Brian: Hide your picnic baskets from Backpack.
Rebie: Did you see how much our content writer Will just started laughing?
Bo: You have to be of a certain age to catch that though. Little Yogi Bear reference.
Brian: That’s exactly right.
Bo: That’s… You know what? News.
Brian: No, no, that’s feel-good. I mean, that’s not on the front page, obviously.
Bo: But I mean, it’s probably more valuable to know that, and to catch a Yogi Bear reference, than some of the headlines that we all… I’ve done some traveling here in the past couple, you know, past couple years. Got to go to some cool places. Have seen in the last two years two bears in real life, and my whole life I’m waiting for it, and I just think it’s the coolest, coolest thing in the world. I think they’re magnificent creatures. I think they’re awesome. Terrifying, but awesome.
Brian: Yeah. I will say I was on an Alaskan cruise and we went for one of the bear experiences. Did you see?
Rebie: Yeah, we had, we had a bear, less polar bears, right?
Brian: No, no, no. It looked like it was brown, like a grizzly, but it’s really a black bear just with brown-type fur. So it looked a lot like that, but it wasn’t as fat as that one. But I remember thinking, there’s not enough safety. I need more guardrail. I mean, because I couldn’t believe that we were watching and the guy, yes, had bear spray. But I was like, this shows how these animals must not really want to attack, because every day they’re bringing people to, because this was not like they were at a sanctuary. These were legitimate out-in-the-wild bears who were waiting by at this salmon factory or whatever to try to capture the fish. And I was like, this does not feel safe. But that shows the nature of the bears is not to come attack us.
Rebie: Did you say these bears were just hanging out by the salmon factory? Is that real for real?
Brian: No, I think, no, that’s where a lot of these fisheries are, where these bears come.
Rebie: Fishery makes more sense. I thought they just stand at the factory door.
Brian: What to imagine? I was like, swim upstream and, you know.
Bo: Okay. Yeah. So, the people are fishing for… Okay. So, everybody is gathering there. Look at that. Right. Right.
Q&A: Can We Save 15% Instead of 25% If We’re Ahead for Retirement? (47:48)
Brian: Nailed it.
Rebie: Okay. Well, that was From the Wings. Never disappoints, I’ll tell you that. I have a spicy question for you next. Are you ready?
Bo: Uh oh.
Rebie: It’s not a gotcha question because I know you’re going to be able to answer it, but it’s a good question. Are you ready?
Brian: Okay.
Rebie: Mr. Big Bad Bug 7 asked this question.
Bo: Why you just like this thing?
Rebie: Oh man. He says, “Wife and I are 30 and have two and a half times our annual income invested for retirement.”
Brian: Wow.
Rebie: “We started at 22.”
Bo: Let’s go.
Rebie: “The How Much Should You Save resource that we have at moneyguy.com shows 15% savings at 25 may replace 80 or 100% of our income. Can we move from step six to step seven while saving 15%?”
Bo: Well, I love what you’ve done, Mr. Big Bad Bug. You’ve assessed, okay, where am I? I know that you guys say that by the time I get to 30, I ought to have one times my annual income saved in liquid investments, but he has two and a half times. You’re smoking that. You’re at two and a half. And so then you said, “Okay, well, let me assess where I’m at on my path and trajectory. If I, based on what I have now, I’m assuming you did use our Know Your Number tool at some point to kind of navigate this, but based on where I am now, if I save 15%, I’ll be able to replace 100% of my income.” Man, does that mean two questions? One, can I drop my savings rate from 25 down to 15? And two, can I change where I save? Because if you’re asking to go from step six to step seven, what you’re really asking is, hey, instead of putting all my money into my 401k pre-tax employer-sponsored retirement account, can I now shift and begin putting more money into a taxable brokerage account that I might have access to? And I think the question they’ve really got to answer, Brian, is sort of, begin with the end in mind. What are they trying to accomplish? What do they want their future financial life to look like? When do they think they’re going to need these dollars? Because I would argue, yeah, you could do that. But is that the most advantageous strategy at this point? Or might there still be some significant benefits to saving inside of that 401k, inside that employer-sponsored plan, whether it be on the pre-tax side or even maybe on the Roth side, given your age.
Brian: Well, now look, a lot of you, if it’s how much should I save, I’d be curious what the age of retirement was, because he might have, because I’m wondering if, because yes, 15% potentially works. I don’t have our deliverable right in front of us, but if it’s 65 or 60, he might want the option to retire earlier. And that’s what, look, here’s what’s going on with Big Bad Bug. To have a two and a half times multiple at 30 years of age, he’s been saving more than 15%. There is probably 25% and beyond. And you’re essentially asking, Mr. Big Bad Bug, I’m trying to say that quickly, if you can take your foot off the accelerator. And before I’m willing to give you permission on that, you need to realize you are 30 years of age. You’re much closer to the starting line than you are to the finish line. But I don’t want to say no to you taking your foot off. Just gut check, because my gut is you need to probably keep doing it longer because you’re, like I said, closer to the starting line than the finish line. But I would ask you to ask yourself some serious questions. If you went down to 15%, where does the money go? I mean, is there something that actually is going to add tremendously to the value of your life? I think you’re going to probably look at it and realize no. I mean, so you’re just going to go consume more of the money, because realize there’s also a double-edged sword to this. If you increase what you spend at a younger age, what you require in the future also increases significantly, right? So that’s why you need to be careful. That’s why I’ve always practiced this thing called forced scarcity, especially until I got into my mid-40s, because I was on purpose trying to make sure my lifestyle stayed somewhat in check without giving up. I didn’t want to be a miser. I wanted to be a financial mutant. I didn’t want to give up vacations. I didn’t want to give up creating memories, but all on purpose was trying to keep my lifestyle in check. So, my appetites didn’t grow to a level that it was hard to replace it down the road. You know, because that’s the point I’ve realized, you know, when you’re younger, you don’t have it completely figured out on what creates happiness for you. It takes a little bit of time and experience to figure out what things are out there. You know, is it a bigger house? Is it a nicer car? Or is it going on nicer vacations? You have to figure that out. And it takes time and experience to figure out. And I don’t want you to go ahead and cut off your savings rate at a young age just so you can go spend more. It needs to be a little more deliberate than that.
Closing (52:46)
Rebie: Love it. That’s great. If you want to go check out that resource, How Much Should You Save, for yourself, go to moneyguy.com/resources. You can always use our free Know Your Number tool there to see what you might need to have in retirement based on your goals. And by the way, the calculation on that is typically an 80% replacement ratio, not 100%.
Bo: Well, that’s why I don’t know if he was using the Know Your Number tool or the How Much Should You Save resource.
Brian: How much should you save? See, I wonder if he misinterpreted and it’s really 80%. It would replace 80%.
Rebie: That’s possible, but I’m not positive either. But this has been great. You’ve asked some great questions. We love that you show up every Tuesday and we will be back Tuesday at 10:00 a.m. Central. Don’t forget to go pre-order Brian’s book if you haven’t yet. You only have two weeks left to get the perks and to help us support the mission of kind of showing the publishing world and the bookstores and all the things that this book should get out there. The message is important. That’s what the pre-orders are really helping us do. So, go to moneyguy.com/millionairemission if you want to be a part of that. We can’t wait for you to see it.
Brian: And by the way, if you’re a Barnes & Noble or a local bookstore, maybe you support the local bookstores, and you go in and you see that they don’t have my current version, or you just want to go talk to the manager and say, “Hey, are y’all going to have the most recent version of Millionaire Mission that’s coming out?” Go ask, because that’s actually how they drive those store sales, is they want to know how much interest the local community has. And that’s what made this thing a New York Times bestseller the first time around, was you guys. You know, I remember, my publisher, we were all at the airport on the book tour when we got the call from the publisher, and you know the excitement in your publisher’s voice, because it’s not supposed to happen on your first book. So you guys made it happen last time. I would ask you once again, because what this thing does is it’s getting the message out. You know, we really, nobody writes a book unless it’s like JK writing, you know, Harry Potter, but if you’re most people writing books, this is not what’s actually going to create all your wealth. This was more of just like, the heart of the podcast was a passion project to help educate people. The writing of the book is the exact same thing for me. You don’t make a gazillion dollars writing the book, but I think that it’s worth a gazillion dollars getting literacy into people’s hands at a very affordable price. And that’s why, you know, look, I could have kept this thing hardback for many years. Probably they would have run a whole new pressing, a printing of it. But I wanted it to be more approachable so you could give it as more gifts, get more people to hold this really great intro that I wanted for myself if I would have been the young version getting out there not knowing what to do with my next dollar. So, thank you, thank you, thank you. Thank you for the reviews. Thank you for all the support. We, guys, we really do believe in the abundance cycle. Y’all make it all possible and we love that we get to create this type of content. I’m your host Brian, joined by Mr. Bo. Money Guy team out.
Enjoy the Show?
Where You Can Watch and Listen:
Subscribe on these platforms or wherever you listen to podcasts! Turn on notifications to keep up with our new content, including:
- Episodes of The Money Guy Show every Friday
- Episodes of Making a Millionaire every other Monday
- Mini-shows every Wednesday
- Ask Money Guy Livestreams every Tuesday
- Tons of other fun content!
Free Resources

Free Resources
Financial Order of Operations®: Maximize Your Army of Dollar Bills!
Here are the 9 steps you’ve been waiting for Building wealth is simple when you know what to do and the order in which to...
Free Resources
Wealth Multiplier By Age
If you want to set yourself up for future success, find out how much you need to save every month to become a millionaire.
Free Resources
Car Buying Checklist
Here’s how you can buy a dependable car that won’t break the bank. Our free checklist walks you through the 20/3/8 rule and strategies to...
Articles

Articles
Where To Invest After You Max Out Your Retirement Accounts
If you have a higher income, maxing out your Roth IRA, HSA, and 401(k) might not seem that daunting - and it may not even...
Articles
How To Win With Money in Your 20s (and Set Yourself Up for Life)
The first decade of adulthood is one of the most important periods of your life. The course your life takes when you are younger can...
Articles
6 Financial Changes To Make in 2026
There is no need to wait until an arbitrary date on a calendar to make positive changes in your financial life, but if you are...
Financial FAQs
Courses & Tools

How about more sense and more money?
Check for blindspots and shift into the financial fast-lane. Join a community of like minded Financial Mutants as we accelerate our wealth building process and have fun while doing it.
Free Resources
Financial Order of Operations®: Maximize Your Army of Dollar Bills!
Here are the 9 steps you’ve been waiting for Building wealth is simple when you know what to do and the order in which to...
Free Resources
Wealth Multiplier By Age
If you want to set yourself up for future success, find out how much you need to save every month to become a millionaire.
Free Resources
Car Buying Checklist
Here’s how you can buy a dependable car that won’t break the bank. Our free checklist walks you through the 20/3/8 rule and strategies to...
Recent Episodes

It's like finding some change in the couch cushions.
Watch or listen every week to learn and apply financial strategies to grow your wealth and live your best life.
Episodes
The Truth About Starting a New Career in Your 30s
How much emergency fund do you need during a career change? Brad and Haylee have 3 kids and a $173K net worth. In this powerful...
Episodes
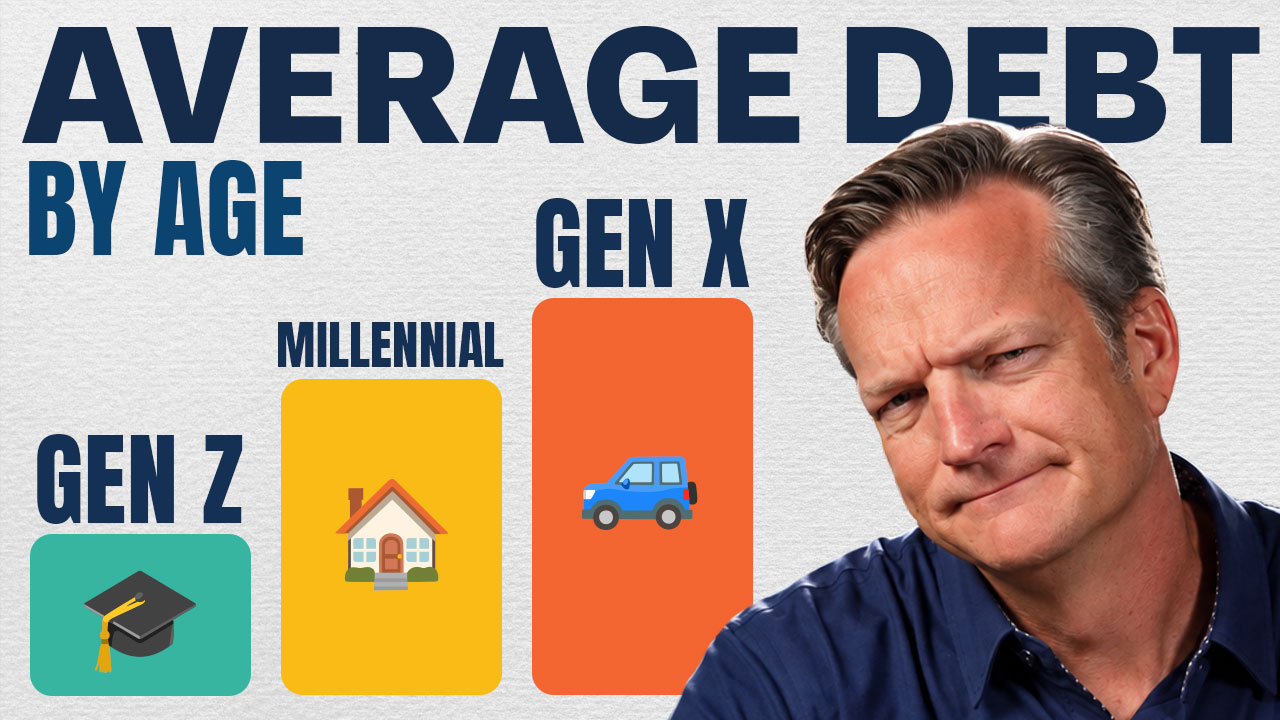
Average Debt By Age (How Do You Compare To Other Americans?)
Americans are carrying staggering amounts of debt by age, but how does your debt compare? In this episode, we break down the average debt for...
Episodes
This Tax Advice Could Land You In Jail ft. Jasmine DiLucci
Home office, vehicle write-offs, kids on payroll: which tax hacks are legit? In this livestream, we are joined by tax attorney Jasmine DeLucci to break...