-
▼
-
▼
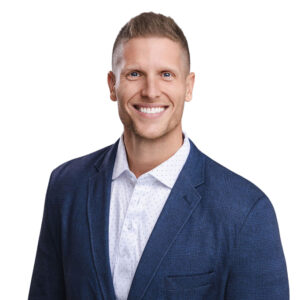
Can tax hacks you see online land you in jail? We sit down with Tax attorney, CPA, and Enrolled Agent Jasmine DiLucci to play “love it or hate it” with the tax hacks making the rounds on social media, from writing off your vehicle and claiming a home office to putting your kids on the payroll, moving to Puerto Rico, and claiming sovereign citizenship. We break down the difference between tax avoidance and tax evasion, why some of these strategies can work with the right facts and documentation, and which ones are red flags that could put you on the wrong side of the IRS. Whether you’re a business owner, a side hustler, or just trying to keep more of what you earn, this conversation can help you spot the hacks that aren’t worth the risk.
Then we answer your live questions, with Jasmine weighing in on teen babysitting income and what counts as earned income for a Roth IRA, moving from Michigan to Florida to avoid state taxes, starting an LLC to make Roth contributions after retiring early, and how to handle a big bonus when you’re in the top tax bracket. We also get into how to handle uncertainty around AI as a software engineer, how to find a good tax accountant or financial advisor, and whether selling custodial account holdings to take advantage of the kiddie tax is worth the hassle. Check out our free download 8 Questions to Ask Your Financial Advisor so you can know if a financial advisor is the right fit for you.
Enjoy the Show?
Where You Can Watch and Listen:
Subscribe on these platforms or wherever you listen to podcasts! Turn on notifications to keep up with our new content, including:
- Episodes of The Money Guy Show every Friday
- Episodes of Making a Millionaire every other Monday
- Mini-shows every Wednesday
- Ask Money Guy Livestreams every Tuesday
- Tons of other fun content!
Tax Advice That Could Land You in Jail with Jasmine DeLucci (0:06)
Brian: We got a special one of that tax advice that could land you in jail with a special guest. We got Jasmine DeLucci.
Bo: See you.
Brian: I blame you for that little slur.
Rebie: They’re both over here making fun of coming up with all kinds of different ways.
Brian: Jasmine, welcome to the show.
Jasmine: Thank you so much. Excited to be here.
Bo: I am so excited to have you on today because you’re a bit of a tax wizard. Like we watch. Oftentimes we collaborate, but we’re actually like fans of your content. We love watching, love diving into it, and it’s so, so good. So thank you for coming out today, being willing to go through some tax stuff with us because in our mind, in our opinion, there is so much tax stuff that lives out on the internet that I can’t be positive.
Bo: I’m not the wizard. That doesn’t sound like it’s great tax advice, but it’s very clickable.
Jasmine: Yeah. Oh yeah. There’s lots of great. I mean, you can hear tax advice from your hairdresser nowadays and your tax from your realtor. You can hear tax from, you know, everyone. So yeah. No, that’s crazy.
Brian: And so you are, for folks who aren’t familiar with you, right, you’re a practicing tax attorney, CPA, enrolled agent. You have a practice. You have a social media channel. You do all things taxes. And you have been doing that for your entire career. Well, I think I’m nerdy, but you were actually an enrolled agent, and like, as a teenager.
Jasmine: Yeah. So back in eighth grade, I told all my friends in the cafeteria, I was like, I’m going to be a tax attorney.
Bo: And so cool. They tell me, man, that popularity winning contest right there, obviously.
Jasmine: Yeah. You know. So dreams come true. That’s what I would say. They were wrong. But yeah, I got my enrolled agent license, which is, you don’t need, like, a high school degree. At the time, there was actually no age requirement, and so I just started taking it. Now there’s an age requirement. They added it.
Brian: Because of you. And they probably did.
Jasmine: I was thinking about it because it happened right after. And at the time when I took it, my dad went around being like, is there an age requirement? Is there an age requirement? So I think he made it kind of a big stir about it. And then yeah, they introduced one pretty soon.
Bo: That’s amazing. And I’ll tell you what I love about your content, Jasmine, is that I feel like, you know, it’s educational. It’s not trying to fluff things up just because you want to create an angle that makes it more clickable. You’re truly trying to educate the masses. And I love that because that’s kind of our abundance cycle foundation. So it’s creator to creator. We really do enjoy your content.
Jasmine: Thank you. Yeah, I mean, I just love learning and I love learning about tax. And so being able to share that has been just one of the best things ever.
Tax Avoidance vs. Tax Evasion (2:33)
Bo: Well, I’m super curious because obviously no one, maybe I shouldn’t say no one. Maybe that’s too broad of a brush to paint with, but most people don’t like paying taxes, and they certainly don’t want to pay more taxes than they have to. And we say all the time on the show that we have an entire tax system, an entire tax code that’s built around tax avoidance. If you understand how it works and the unique intricacies, you can avoid taxes. But if you try to evade taxes, that part’s illegal. And I just feel like a lot of what we see on the internet, and a lot of the stuff we come across, blends the lines of those two or it’s not quite as clear. Would you agree with that assessment?
Jasmine: Yeah. Well, I mean, in general, but people do taxes. They, to be honest, use their common sense. And, you know, sometimes taxes is in line with common sense and sometimes tax is not in line with common sense. You know, just goes back to like, let’s just look at the rule. And so it’s easy to just say whatever. And people will do that. And they say something that makes common sense. Someone listens, and then you’ve got, and then you have tax evaders, not tax evasion.
Bo: That’s exactly right. And it sounds like, right, because we’re asking the question, you know, we always say, Brian, what is it? Don’t mess with the IRS because, what you say, they have the guns.
Brian: They have the guns. I mean, that’s the thing. And then also, I think it’s important for people to understand what we’re going to kind of cover today: tax avoidance versus tax evasion. I had a tax partner, and I shared this with you, Jasmine, who said, everything’s deductible until you get caught. And I feel like that’s what a lot of people on social media are counting on, that there are so few audits out there. They are just counting. This stuff slips through the cracks. But that doesn’t mean that you’re on solid ground. So we ought to talk about it because we love tax avoidance. But we do need to keep people on the right side of the law so they don’t end up in jail.
The Tax Hack Game: Love It or Hate It (4:15)
Bo: Yeah. So we were thinking we’d play a little game. Right. And we’re going to talk about some different tax hacks that we’ve heard of that either we’ve seen on the internet or we’ve heard people communicate. And we want to ask you, all right, do you love this tax hack? Yep, it’s legitimate, you should do it. I kind of like it, but here’s what you need to know. Or absolutely no, I hate it, it’s going to land you in jail. And I think a lot of our people, because when you are hanging out at the barbecue and you hear your, you know, cousin Eddie say, hey, I got this great way to save money on taxes, I think you’re going to hear some of those right now. And I’m hoping you can maybe dispel the myths from the truth. Is that fair?
Jasmine: Yeah. Let’s do it.
Bo: Awesome. All right, Rebie, with that, are you going to throw to us the tax hacks that we ought to know and ought to be aware of?
Rebie: I certainly can. Are you ready?
Bo: Yes, ma’am.
Tax Hack One: Writing Off Your Vehicle (4:52)
Rebie: All right. The first one is: I drive a lot for work, so I’m going to write off the value of my vehicle. Do we like it? Love it or hate it?
Jasmine: Like it.
Brian: Okay.
Jasmine: Yeah. So it’s always like, like it, to me, is like with qualifiers. Because it depends. That’s what we always say, it depends. So, driving to and from your primary place of business is personal commuting and non-deductible. Right now. One way to successfully change that is if you are able to legally establish a home office, which people are a little too loose with sometimes. But if you legally are able to establish your principal place of business as your home, then driving to a secondary place of work, a client, whatever it is, is deductible, it’s business mileage, basically.
Brian: And then you would take that portion of your vehicle. If you have a home office, can you drive to the not-home office, and that part counts? That becomes business mileage.
Jasmine: Yeah, yeah, it would move from personal commuting, which it would have been had you not had the home office, to business mileage.
Brian: Got it. And then also you have to keep really good records because that’s what you… by the way, what’s a good app that people can use to track their mileage?
Jasmine: I like MileIQ, because the one in QuickBooks I thought it was going to be awesome, but it’s kind of spotty a little bit.
Brian: So to hear a good… by the way, that recommendation makes this collab worthwhile right there because you have to keep great records. And then what about the fact that the weight of the vehicle matters? Because every content creator says you’ve got to drive a G-Wagon so that it weighs enough.
Jasmine: It depends. So first, first and foremost, you need the business mileage, right? It doesn’t matter what the weight of the vehicle is if you just don’t use it for business or you just use it for personal commuting. Now, if we’ve met that threshold and we’ve got good records and we’ve got proof, okay, this is business use, then, okay, well, are we going to be deducting the actual mileage or are we going to deduct the actual expenses? If you’re on that actual expenses side, then the vehicle weight comes into play. It’s not a magic get-out-of-jail-free card. But it helps you get around those 280F auto luxury limitations. And so that’s the sizzle, the accelerated depreciation.
Brian: Yeah, that’s what everybody’s really trying to get to.
Jasmine: But that’s what you know, that’s the, it’s like thresholds, right? There are hurdles. The first hurdle to unlock all of the bonus. And then there’s also some impact on 179 and the 280F auto luxury limitation.
Brian: Can I ask a part B to this one? And I’m sorry, we didn’t talk about this, but we got Jasmine here.
Jasmine: Yeah. Let’s hit it.
Brian: So I have people all the time saying, hey, you know, I need a new car. Here’s what I’m going to do. I need to replace my spouse’s automobile or whatever. We’re going to go buy the big SUV. We’re going to buy it in November, end of the year. And what I’m going to do is I’m going to turn it into my work vehicle. I’m going to drive that this year for the next two months, and then I’m going to be able to deduct the entire cost of the automobile. And that’s going to be the thing that I do, because I drove it exclusively for work purposes for the whole time it was in service. Love that, hate that? Is that legitimate or should you be cautious if you’re going to try to perpetrate that strategy?
Jasmine: Are you saying because what you’re going to switch the use as of January 1st? The idea is, yeah, I might decide that’s not my work. Like, you have to do it at least two years, right?
Brian: Well, yeah, it would be the life of, not just two. You’d have a recapture that triggers if you, like, the five-year usually.
Jasmine: Okay. So you have to make it your primary automobile for five years, not just through the end of this year. And then you put it back into… there’s always, like, if this… you know, it depends. So it’s also like, is it in a corporation? Because if it’s in a corporation, really permanently, once you move it to personal use, like just taking a vehicle that’s depreciated out of a corporation is going to trigger a taxable event. So that’s one instance. But yeah, just switching from like, if you can’t just bonus depreciate the whole thing and then switch it January 1st, within the useful life, then it’s going to trigger recapture.
Brian: Yeah. So you didn’t actually save any money on taxes. It comes back. It’s depreciation recapture, what she’s referring to. And it can get big.
Bo: Awesome.
Rebie: All right. Cool. All right. So that one was a “like it.” All right. Tax hack number two.
Brian: Yeah, this is good. We’re going deep.
Tax Hack Two: The Home Office Deduction (8:45)
Rebie: The next one: I’m taking the home office deduction because I work from home sometimes. I took my laptop home. This is my home office now.
Brian: Oh, my office.
Jasmine: So you’re always in between. To me, I’m like, it depends how it plays, right? You have to meet the legal requirements of a home office. And so I think people think, you know, I work at home. Right? It’s like, if I sit at my kitchen table, if I meet the…
Brian: I’m not just putting a desk in your bedroom. Does that work?
Jasmine: No, no. I mean, to me, I would go back to the law. What’s the requirement? Well, it needs exclusive use. It’s not like laptop on my kitchen table, you know, because a kitchen inherently is not exclusive use for business. So then you need a dedicated space, exclusive use. You need regular use. So it really needs to be like a business. Even part of the definition of a business is that regular, continual, substantial, throughout the year. And then finally, you know, there are different requirements. It could be a separate structure. It could be that your clients actually come to your home. Both of those are more rare, or what most people end up doing is principal place of business, which is if you can show that you basically do all your admin and management work at home. Now, that’s where a lot of people are kind of fudging it because they’ve got a whole full-fledged office there in a regular white-collar job, and they magically just do all their admin at home. I do think I always look at things historically from a Congress standpoint. I know this is like, it’s like Tax Policy Center.
Brian: No, that’s not nerdy at all.
Jasmine: Okay. And, you know, home office actually used to be stricter. And then there was a court case that basically came to a result Congress didn’t like, and it denied the home office deduction. And they basically said, we don’t like that. We want this to actually be more flexible and easier to meet. And so then they introduced this admin and management. So when I look at that congressional history, I say, okay, have good support. I feel good about it if you’ve got good support for it. It’s not one of those areas where the IRS feels there’s very high abuse.
Brian: And so the way this works is I’ve set up a separate office and I do my stuff there. I do admin and operations there. That means I can deduct all of my mortgage and all of my utilities, all of my… That means I get it all tax-free, right? That’s the way it works.
Jasmine: No. Yeah. I mean, there are a couple of ways to calculate home office. One of the more advantageous ones is you prorate it. Right? So it’d be prorated based on that area of exclusive use.
Brian: Perfect. And that’s the big thing I always remind people: create some boundaries, so that way, because what always blows everything up, whether we’re talking about the cars or we’re talking about home office, is the personal use component. Because that’s what the IRS is really trying to figure out, is how much of this is really for exclusive business purposes versus how much is personal. And if you got, you know, all your kids’ toys, like your picture, you show the IRS in the audit and it has all the kids’ toys in there, that’s probably not going to help your case.
Jasmine: Yeah. Well, it’s always guilty until proven innocent, right? So people say, well, how can they prove that? Like it has the bed and the crib and that, you know, but it’s actually on you to prove that it doesn’t.
Tax Hack Three: Putting Your Kids on the Business Payroll (11:47)
Bo: Yeah. Love that. All right. Tax hack number three.
Rebie: Yep. Tax hack number three: I’m putting my kids on my business payroll so I can deduct their pay as a business expense. What do we think?
Brian: Have you seen how cute my kids are? I took a picture of him.
Bo: Well, that’s all I saw on social media is everybody, get your grandparents to pay your kids to be models.
Jasmine: Yeah, I see that all over the place. Love it? Like it or hate it? This is a very general sentence. So it’s like, I’m just going to keep going, like it, because it can make a lot of sense. But what you see on social media is, I’ve got a construction business and my newborn baby is a model, and it’s like, what construction business do you see out there that’s got a newborn baby as a model? Like maybe if you ran a food business and you own, like, Gerber food, makes sense.
Brian: Yeah.
Jasmine: So it’s always facts and circumstances. A lot of people just abuse it with ridiculous things. And businesses really don’t need newborns, right? Like they don’t need two-year-olds, like they don’t, you know. So if their idea…
Brian: Yeah.
Jasmine: So there’s really not an ordinary and necessary business use there. And that’s the whole thing, it’s always like, what’s the tax position we’re taking? That’s always the question, because people think there’s some magic like this and that. But it’s like the tax position here is that you’ve got an employee that’s providing valuable services in return for the money. And because we’ve got a related party transaction, we’re economically on both sides of the transaction. So we’ve got automatic high scrutiny. So then it goes, okay, well, let’s have really good substance. And so if there really is a genuine need and use for a child in your business, and based on their wages, you can do it. But don’t be ridiculous, and don’t run afoul of self-employment or payroll taxes.
Brian: I mean, because that’s the thing, I think a lot of, you know, all these things, because that’s 15.3%. Everybody seems to forget that if you’re hiring your kids, there’s still going to be some taxes for Social Security and Medicare coming from someplace. And it’s like a lot of people don’t think about that substance of.
Jasmine: Well, it just depends. I think there is that workaround where if they’re under 18, if the wages are coming out of a partnership or a sole proprietorship, you would avoid the payroll tax. But then that’s why people do all this funny business, legal gymnastics is what I call it, right, where they’re like, okay, have an S corp, and that saves me the most tax. But now that I need to hire my kid, I’m going to have this fake family management company so that I can have a sole proprietorship and then avoid payroll tax. So they do these weird things that, it’s like, everyone knows what people are doing. It’s literally advised online. The IRS can and does just collapse those and make it all, no matter how complicated you think the structure is, they’ll bring it all down and say, here’s the materiality, it doesn’t work.
Brian: And I don’t mind just sharing this as the old guy here at the table. From a parental standpoint, I’m always trying to connect the behavior with the money component, because what you want to do is get your kids to actually not only see money as a tool, but as a component of how to use the tool well in the future. That’s why I like when my daughter got her first job, a real job in fast food, opening up that custodial Roth and kind of explaining how money works and then letting her be part of it. I think that was better than if I’d just had her as a model when she was a baby, and then just has this magical account that grows. And then, by the way, be careful also with the fact that when that child turns 18, a lot of these accounts, they can just take it. And I’ve also experienced that: when your daughter gets to be 18 and you open this custodial Roth, and they want to open the Fidelity app and they see all these other accounts in their name. Well, it’s an education moment. So you have to think about these things. Don’t think about just the money and the taxes. Think about also how you’re going to let your child learn how to use money as part of this.
Jasmine: 100%.
Tax Hack Four: Moving to Puerto Rico (15:04)
Rebie: All right. Three more tax hacks for your consideration. Number four: I’m moving to Puerto Rico for the tax breaks.
Brian: Now, I’m assuming you do pretty good. Have you ever looked into moving?
Jasmine: I have never looked into it, but I’m not ashamed to say I’ve actually…
Bo: Oh, we’ve looked at, scrolled around Puerto Rico, saying, what is it? You know, because when you see how the rule works, you’re like, maybe I should look in Puerto Rico. But then, you know, for those that aren’t familiar, what’s great about Puerto Rico from a tax standpoint, and can we just move there and automatically we don’t have to pay any taxes anymore?
Jasmine: Yeah. I mean, it’s just under different rules. Basically, your tax rate just goes down very substantially if you’re a bona fide resident and meet certain requirements around where the sourcing of your income is. You know, as far as answering this, like, I kind of hate it. It doesn’t mean it’s not legal, that you can’t do it, but it’s just such a big change for people that I just like. Realistically, people just try to not do it, you know. They just keep not trying to divorce the economics from the tax. So like, how about if I just pretend like I’m not… just buy a place in Puerto Rico, does that count? And that doesn’t count. It doesn’t satisfy. And it’s kind of the same thing that people do with all the state tax stuff, right? Like you’re living in Nevada, but you’re really living in California, you know, and everyone’s seen this stuff before. It’s not new. It’s just what everyone tries to do. And so it’s like, even when you’re doing it legitimately, when the IRS or when the state authority comes in, they’re just assuming you’re not going to prove them otherwise.
Brian: Yeah, right. We got to hate it. I kind of hate it. You heard it here, Jasmine hates Puerto Rico.
Bo: She did not say that. Not what she said. She just said you need to actually move there.
Brian: Yeah. You actually realize it’s for economic development and incentives. That’s why it is one of the unique things. Because there’s a lot of things you can do in a state that give you state tax deductions. Very few things change federal taxes. Puerto Rico is unique in the fact that it impacts your federal taxation. That’s why people get so excited about it.
Jasmine: Yeah. But then who wants to actually move, once you think about kids and all the other stuff? Logistically, it just fell apart. Yeah, yeah.
Tax Hack Five: Writing Off a Vacation Because of Work Calls (17:05)
Rebie: All right. Tax hack number five: Don’t worry, I took a couple of work calls on vacation so I can write the whole thing off as a business.
Brian: I saw some videos on this just like last night. Hate it?
Jasmine: Yeah. Hate it. There are so many things wrong with it. And there are so many rules with, you know, in general when we have something that’s high abuse, which certainly travel is, there’s just a lot of rules, a lot of hurdles in place. But fundamentally, the location for sure needs to be necessary for the business. And so being like, well, I took work calls there. If you could have easily done it in your kitchen, the location itself wasn’t necessary for the business. It’s not ordinary and necessary.
Brian: And I’ve watched enough of your content, Jasmine. You’ve also shared when you get a group of investors together or people, you have an investment club, and you decide, we’re going to go to Paris to hold our annual meeting. Yeah, there are even issues with that, isn’t there?
Jasmine: Yeah, because if you all lived stateside and you went international, there’s another boundary you have to cross for the government to be okay with it. Yeah. But so all of these high abuse areas, almost all of them are in 274(d), which includes travel, you know, 274(d), 274, right there in the middle.
Brian: 274(d), got it.
Jasmine: And there are just hurdles in place. So for travel, sure, we have 162(a), ordinary and necessary business expenses. People love to be like, oh, like as if they just read some creative whatever. And then okay, next hurdle, 274(d) travel. We also got the Treasury regulations come in and say, okay, primary purpose business. So they’re also looking at total facts and circumstances, but they look at how much time and how much significance of the business activities versus personal. And then we keep going. There are more hurdles. And so the one you’re probably thinking about from my content is 274(h).
Brian: H. I was thinking D and an H.
Jasmine: Yeah. You get thrown by those. And it is for international specifically. There’s an additional hurdle, right? Because they’re like, you know, again, people would love to just go on their board of directors trip to Bora Bora. But if it’s as reasonable to have just done it in the US, then it’s not deductible.
Brian: Yeah. It’s so interesting. We’re joking about you being able to pull out these parts of the tax code. I would argue if you’re someone out there trying to carry out or execute these strategies, and you’ve never even heard these parts of the code, that should be a red flag to you. Holy cow, there’s something more to this than I probably should know. And I think a lot of people, they see it on TikTok, see it on Instagram, like, boom, I’m going to do that. Not recognizing it is involved. It is complicated. It is deep.
Jasmine: Yeah. A lot of times they literally just don’t look at it. They’re like, it’s a gray area. And I’m like, actually, it’s literally in the code. Not great at all.
Tax Hack Six: Claiming Sovereign Citizenship (19:40)
Rebie: All right. Last but not least: I claim sovereign citizenship so I don’t have to pay taxes.
Brian: This can land you in jail. This one will get you actually in jail.
Jasmine: In jail? I mean, it always goes back to, I mean, this is criminal, right? And I mean, a lot of other things are not, you know, are criminal as well. But of course, there’s always a materiality element. Realistically, the criminal division of the IRS is relatively small. They want to go after big things. Their rate of conviction is, I mean, it’s like they basically convict everybody. They go after cases that they win. So more likely to go to jail if it’s more money, for sure. But yeah, not legal.
Brian: So I think it’s interesting because we put sovereign citizens as one, you know. I think, is this the one I think Wesley Snipes might have fallen into, where somebody told him that the code section that if he… And we’ve also heard people writing letters to the IRS saying under this section, I’m exempt. That stuff doesn’t work. So be very careful. But also we could have expanded this to talk about when you watch content and it talks about, you know, turn yourself into a church, turn yourself into a foundation. All these things is, our headline said, this is how you end up in the orange jumpsuit and look like a Tennessee fan, is when you go this far with taking the tax avoidance to full-on tax evasion.
Jasmine: Yeah. People think, you know, I relied on an advisor, right? When you look at the requirements to rely on an advisor, it includes several things. First, you have to hire someone who’s actually qualified and competent. Right? So it’s like, I relied on a buffoon is not… I relied on a random tax guy. Again, it’s not an argument. So you’ve already missed those requirements. But so, I relied on someone qualified. I gave them all the information. And it’s also including that you actually do due diligence. Right? There’s a level of due diligence on your end required. And so, yeah, I mean, it’s just like whether it’s this or there’s so many other tax investments people do and they’re like, but someone said, like there’s a legal letter, and it’s like, the IRS doesn’t care about that guy. The IRS cares about you. You signed your return under penalty of perjury, and that’s a big deal. And that will get you in super hot water with the government.
Legitimate Ways to Save on Taxes (22:01)
Brian: And so it sounds like there’s all these different tax hacks that we hear about that are not legitimate. There are legitimate ways that you can actually save money on taxes. A lot of people go out there. You mentioned some, real estate is a great example. If you were legitimately operating in real estate, there are tax advantages to doing that. If you’re a small business owner, there are legitimate tax advantages there. If you’re saving through traditional ways, and retirement accounts are legitimate tax advantages to those things. This stuff that’s kind of way out there in the ether, super complicated, super complex, for most people it probably makes sense to avoid those, to not get themselves in a bad situation.
Jasmine: I agree 100%.
Bo: She says she loved that. She says she loved that. And I want to kind of, because I can’t wait to open this up for questions. But Jasmine, if somebody is, like, business structure or any of these things that they’re small business owners, I mean, tell everybody what your channel is because, as you can tell, I actually watch a lot of Jasmine’s content. This is fun to kind of get in the weeds to hear about the different sections of the IRS code. How do people know more about you?
Jasmine: Yeah. So at Tax Leverage on YouTube, and then at More Tax Leverage.
Brian: You thought Tax Leverage was not enough? We got more Tax Leverage.
Jasmine: More Tax Leverage. And then I also actually have a tax planning roadmap. So what I did was, because I mean, to me, I look at all this crazy advice and I think people think it’s more complex than it is and really just need someone to explain it in layman’s terms, just go step by step. So that’s what I ended up doing, just like a free roadmap for everyone. And it just goes through like, here are the levels that you should be at if you’re a business owner.
Brian: Love that. Yeah. Awesome. Well, one of the things we get to do is obviously we get to put together content that we think is interesting, but we also get to sit here every Tuesday at 10 a.m. when we get to answer live questions for you, our audience, because we really do believe there’s a better way to do money, there’s a better way to do taxes, and we want to load you up. So if you’re out there in the chat right now and you have a question, you want to get either our take on, or realistically, you want to get Jasmine’s take on, make sure that you get it in the chat right now because we want to load you up. Okay, answer the question. Do it. I’m excited. With that, creative director Rebie, I’m going to throw it over to you.
Bo: By the way, I think Jasmine thinks we’re crazy because, like, we’ve already filmed a react this morning and then now we’re… Bo, I’m seeing this thing. Looks like mission control. There is no way they would let me see this much data if there was, like, a blinder I could put right here. You probably like…
Rebie: This place is chaos. So welcome to our chaos. But we are excited, to be honest.
Brian: Let’s now see what crazy chaos she can create with a question.
Q&A: Teen Babysitting Income and a Roth IRA (24:27)
Rebie: I will kind of tame the chaos and get to some really good questions here. Like Melissa’s question. It says, “My teen daughter babysits and gets paid in cash and makes under $8,000 per year. She also invests in a Roth IRA. Does she need to file taxes? What evidence is needed for earned income for a Roth IRA?”
Bo: Good question. So I already love the start of Melissa’s question. She recognizes that in order to be able to contribute to an IRA, whether it be Roth or traditional, you have to have some sort of earned income. That has to be a thing. But her question is, okay, well, what counts if my daughter wants to fund a Roth and she does babysitting? What things have to be true for this to be legitimate?
Brian: I mean, it sounds like she has earned income, but it’s just not being reported. So she’s got to report the income.
Jasmine: Yeah. You want to report the income. It’s funny because people do that with their kids too. They’re like, I’m just not going to issue the W-2 and not do all these things. But then can I move it to the Roth? And I’m like, you’re kind of undercutting your own taxes. So same thing here. I mean, that’s honestly, to some extent, what should be happening is I would expect that to be a W-2 in those types of situations. Now, probably they’re trying to, what, 1099 contractor.
Brian: Well, you’d just Schedule C. I mean, it’s probably Schedule C as income for that, probably.
Jasmine: Yeah.
Brian: But you have to encourage your child, hey, you actually have to file a tax return. You have to report this. I know, look, I want to be careful, because I don’t want any tax evaders in my neighborhood to get arrested. But I know there’s a lot of young folks who babysit, and I don’t think they’re filing a tax return. And they’re probably also not funding a custodial Roth. But if you want to do one of these things, like saving in a Roth IRA, then you actually do have to file a tax return, whether you’re mowing yards or whether you are babysitting or whether you’re doing any other side jobs. You have to treat it like a legitimate business, report the income, and be able to take advantage of some of those other savings strategies.
Jasmine: Right. Especially at this level of $8,000 per year, I would think a Schedule C under your child’s Social Security number and then probably paying the self-employment taxes, being prepared. That’s the other part. Don’t be shocked to find out they might not owe that much in income taxes, but there’s going to be a bill for the self-employment taxes, the Medicare and Social Security.
Brian: That’s like making over $150 bucks a week in babysitting. That’s like, oh no, Melissa. And by the way, your daughter, how old was she? She said teen, teenage. Awesome. I mean, the wealth multiplier, because that’s the other thing, you know, it’s just how much the money will grow if you put that in that custodial Roth. Just don’t even try to beat the market, just buy an index fund. And, I mean, it’s going to be something big. Some good stuff.
Q&A: Moving from Michigan to Florida to Avoid State Taxes (27:09)
Rebie: All right. Next question is from Pat 0024. It says, “Father-in-law and mother-in-law bought a home in Florida to avoid taxes.”
Brian: Just outed his in-laws right off the bat.
Bo: That’s why their name is Pat 0024, it’s harder to trace that crime.
Rebie: So the rest of the question is, now they need to live in Florida for more than half the year, and he needs to work his job remote. They’re okay, like they’re getting there, he says. Is this worth it? He is within five years of retiring. So they moved from Michigan to Florida to avoid tax.
Brian: Okay. Why does it matter if they live in Florida versus live in Michigan?
Jasmine: Yeah. I mean, it’s just where are you a resident? Right? So you can kind of view it, I always use California as the example because they’re high tax. But if you’re a resident of California, then they’ll just tax you on wherever your income was. Right? You can go to another state, that income is still sourced to that state, but then the remainder, it’s still taxed in California.
Brian: Yeah. So it sounds like the in-laws are moving to Florida, because Florida is a state that has no state income tax. They’re moving there to avoid taxes. Is that legitimate? If they’re in Florida for over half the year and he’s working remotely, is that an okay thing to do? And it sounds like this is part of their preparation for retirement, getting ready to potentially move down there full time.
Jasmine: Yeah. There’s a lot of context. I mean, first of all, I would need to know the other state. Right? We don’t have the other state.
Rebie: I think it was Michigan.
Jasmine: Michigan. Bought a home in Florida. Okay. I mean, you literally have to just look at that because the thing is, Michigan doesn’t care what Florida’s law is. Florida doesn’t care what Michigan’s law is. So they can both still consider you a tax resident. And so you want to make sure, if you’re going to do it, first off, do it really well. So just being in Florida for more than six months isn’t necessarily enough to not be a resident of another state. You just literally have to go look at their laws to see what the rules are. Because a lot of people do that, they’ll be like, well, I spend more time elsewhere, but a lot of the states look at intent, and going back to intent, like in things like fraud or whatever it is, they can’t look at your intent by what you say. They go by actions. And so they’ll look at more than just, oh, you were there more than six months. They’ll look at things like driver’s license, which home do you own, do you still have the voting record…
Brian: All of the voting records. Yeah.
Jasmine: Where is your family? Do you still have a home back where you moved from?
Bo: So this question almost feels like they’re implying that they also still, they really love it.
Jasmine: And that’s what I was going to add. Because I remember when the firm I was working at, we did professional athletes. And you’d be shocked to know every state that an athlete plays in, a lot of them you have to file tax returns even though they live somewhere else, they still have to file in those states.
Brian: So I would encourage you, if your parents, make sure the actual work is truly occurring in Florida, because I imagine they’re going to change their employer. They’re going to tell them, hey, I’ve officially moved to Florida. I’ve, you know, gotten my tax return, my voting records. But then actually do the work in Florida, because when the IRS or Michigan, specifically Michigan, ask you, if they send you a notice, you’re going to have to show them that this was just, the only time I came to Michigan was a visit, grandkids and other things. Because if they find out you’re working there, they’re going to expect that they kept the strings and they got those taxes. So be legitimate. Do the work. Now, let’s face it, winters in Florida are going to be much better than winters in Michigan. So there probably is not only a tax strategy here. I could make a case for, I spend some time in Florida in the winter. It does feel like you’re getting a get-out-of-winter card.
Jasmine: That’s pretty sweet.
Bo: And look, when you have the conversation about tax evasion with your in-laws at Thanksgiving, let us know how that goes. Let us know how that went.
Rebie: Oh, man.
Q&A: Reimbursing Yourself from an ABLE Account (30:57)
Rebie: All right. Next question is from FOO Following Faith. Love that. Is there a limit on how far in the past you can reimburse yourself for expenses with an ABLE account?
Jasmine: Oh, gosh. Please, Brian, I don’t have this off the top of my head. I’m sorry.
Brian: Yeah, I’m trying to remember about reimbursing ABLE expenses, because one of the questions we get asked all the time, it’s not specific to ABLE, but it’s specific to health savings accounts. Health savings accounts are this great thing where you can fund them presently, and then even if you pay for your medical expenses out of pocket at some point in the future, you can reimburse yourself. And there’s not really a statute of limitations on that. So I can have medical expenses today, and I can reimburse myself when I’m 80 years old for medical expenses. It’s a wonderful way to get tax-free savings inside of a quadruple tax-advantaged account. So I’m wondering if that’s kind of the line, but let me… because I don’t know specifically for Faith. I just want to be honest with you. Do you know?
Jasmine: No, I don’t have this. But I do want to…
Brian: You need to go look it up. So that’s the disclaimer I will put out there.
Jasmine: The thing I will tell you, though, is like most things, it’s when you set something up that you start the clock for the access. And a lot of things, you think about health savings accounts, you think about 529s, because that’s what ABLE accounts use, the structure is very similar to a 529. It’s the tax year that’s the determining factor. Was the account open? So I’m thinking that probably, you’re probably not going to be able to open an account then go two years in the past.
Brian: Now maybe there’s some weird… because realize these accounts were set up because Congress, coming back to your point, you mentioned Congress earlier, they recognized that, hey, parents who have disabled children incur expenses that most people just don’t deal with. And there’s this horrible thing that happens where you don’t qualify for any government benefits once you have hardly any assets in your name. So let’s create something kind of like what we did with 529s, and they called them ABLE accounts. And they’re very powerful, up to $100,000. But I don’t think they let you go back in time. And I could be wrong on that, because like I said, they created already some special powers on these accounts. But you need to look at the fine print. And apologize, this is a live show, so we don’t get to see all the disclaimers.
Jasmine: And that’s what I will say about anybody who works in taxation. It can make you look silly if you’re answering questions without going and pulling the actual code sections and so forth.
Bo: I respect that, and so, as you should. I clearly did tons of research when I typed it into Google. And it is interesting, just now, one of the things that came up, it says, “Unlike HSAs, which allow you to reimburse yourself for years or decades in the past, ABLE accounts do not have IRS rules or a clear multiyear grace in the same way.” They just say… so it’s not entirely clear what the rules are, but it does sound like they tend to be more similar to 529 accounts than to HSAs in terms of reimbursing yourself for expenses incurred in the current year. Again, do the research, because it looks like there’s a bunch of different carve-outs and SSI comes into it. So it’s a complicated question. You want to make sure before you act on it. Like Jasmine said earlier, you actually look up the code sections and know what it is that you’re doing, and you do more than a quick Google search to answer that question. All right. Did the camera, because I’m not used to us sharing, I just spilled a drink all over me. So I didn’t know if the camera caught that stream. Let me know if you saw that. I struggled with the basic function.
Brian: If it didn’t, you would have never known.
Jasmine: Now they know. I didn’t even notice. It’s like admitting to tax fraud online. Like, you know, if you didn’t say it on air, nobody would have known.
Bo: Oh, everybody saw. What the team was telling me, great. So the audience saw it. So I just wanted to, I’m not losing functionality over here, I just…
Rebie: Oh, that’s hilarious.
Q&A: Starting an LLC to Make Roth Contributions After Retiring Early (34:33)
Rebie: All right, next question is from October 2025 Vet, I believe is the username. He says, “I retired early at 52 around October of 2025. So I’m wondering, is it worth starting an LLC to pay myself to make annual Roth contributions, or is it too much trouble than it’s worth because of the tax obligation?”
Brian: Why the LLC?
Jasmine: So I mean, starting a business is what he’s asking.
Bo: I know, I know where this question is coming from, because again, we talk about how much we love Roth IRAs and how valuable they are. Well, some people are like, hey, I’m retired, and I know in order to be able to do Roth contributions, I have to have some earned income. Well, I’m retired, I’ve got money. Should I pay myself so that then I can contribute to a Roth? Is that a sound tax planning strategy?
Jasmine: Not if you don’t do the economics right. So it’s like, I always think it’s a great idea to start a business. Sure. But an actual legitimate business, right? Yeah. So I mean, if the goal is, no, I’m retired and I’m not running a business, then you just don’t even have the economics to do that.
Brian: Well, and also you have to pay. I mean, why would you do an LLC? You could just do a Schedule C on your tax return, but then you have to pay 15.3%, you know, self-employment tax on it. So you’ve already put yourself in a spot where you’ve got to make greater than 15.3% for this thing to even make sense. So it all falls apart right there.
Bo: I’ve got a much better idea that I think is probably a lot easier. If you are retired and you have any sort of part-time work at Walmart, okay, you can do that. Or if your desire is to create more Roth assets, you could just do direct Roth conversions. If you’re in a lower tax bracket, convert pre-tax 401(k)s, pre-tax, you know, TSP, whatever the thing is that you have access to, that may be a better way, even for retired folks that don’t have any earned income, to create Roth assets inside their portfolio without having to, like, start a business and pay yourself and do all that complicated stuff.
Brian: So I want Jasmine to see that there are people who retire early, because we had an earlier off-camera conversation, and Jasmine believes no one should ever retire. Or you. You don’t believe people actually retire.
Jasmine: My advice would be to not retire.
Brian: I love that. All right, have we exhausted that? Is there anything else to say?
Q&A: Bonus Commission in the 37% Tax Bracket (37:02)
Rebie: Okay, great, great, great. Kelly Bomb Gartner is up next. “What if we receive a bonus commission November 1st? Do we need to pay extra tax to get us in the correct tax bracket, 37% on that commission, by the end of the year, or wait until taxes are due in April?”
Bo: You remember when you were due to take tests and there was a question, and you read the question, you get like three quarters of the way through the question, like, I forgot the first part of the question. I feel like this one is one I’ve got to read again.
Rebie: Did you get that on the first go through?
Bo: If I receive a bonus commission November 1st in a few weeks, do I need to pay extra tax to get us in the correct tax bracket, 37% of that commission?
Brian: So it sounds like the 37% income bracket. I know what happened. They did not withhold at the correct marginal tax bracket. That’s what’s going on here. Do they need to do something differently before we get to April, since they know they’re going to owe tax on that? I bet there’s going to be some additional homework or context we’re going to need. Yeah, I’ll let Jasmine take it away.
Jasmine: Well, I mean, I’m going to assume this person somehow got the bonus without withholdings, because normally when you get a bonus through a W-2, it’ll withhold. Even, I mean, oftentimes higher than your marginal bracket.
Brian: Exactly. So normally it’s fine.
Jasmine: Don’t let them 1099 you, Kelly. By the way, the IRS hates that and they want to know about it. So you can go back to your employer and be like, oh yeah. Yeah. So, I mean, because yeah, that’s not supposed to happen. If you’re a W-2 employee getting a bonus, it would still be W-2. But yeah, I mean, probably this person’s fine because they’re probably within safe harbor for estimated tax payments. In which case they should just save the money, make the safe harbor.
Brian: Remind everybody.
Jasmine: I mean, I always describe it like everyone’s subject to the same requirement, right? So you have to pay the IRS throughout the year. Safe harbor is there because you don’t know how much you’re going to make by the end of the year. Right? And so you can either pay in 90% of your current year tax, which we don’t know what that is until the end of the year ends, or 100% or 110%, depending on your AGI, of prior year tax. This person is probably fine. If they’re W-2, they probably are paid in at least 100% or 110% of prior year, in which case hang on to your extra money, put it in a money market that’s safe or something safe that gets an interest rate, and then pay it before April 15th.
Brian: So what I’m hearing you say is it’s okay to owe money at tax time, right? Even if you have this and you’re going to have to pay $5,000, $10,000, whatever, that’s not a bad thing. That doesn’t mean you did something wrong. Kelly, here’s the homework I would do, because you gave us some context clues here. If you thought you were in the 37% bracket with this income, that’s much higher than $150,000. Go look at last year’s taxes. Make sure you’re at 110% of last year. And if you’re not, make an estimated tax payment by January 15th. If you’re over that, just make sure, exactly what Jasmine said, you have the money to pay in the remainder by April 15th.
Jasmine: Yeah, you would just compare that total tax line item on your actual 1040, not what you owed, but what you originally, total tax. And then what are my current withholdings year to date? Multiply by 1.1.
Brian: I feel like we’re dropping a ton of really good information. This is an awesome question.
Bo: Oh, you’ve got to be careful. Remember how you started being like, they’re playing an athlete in freshman year, way ahead, because somebody got sick or something.
Brian: Yeah. Pulled a muscle or something like that. Don’t sleep on Jaz. I know this is kind of fun, dropping this type of stuff. There are two and a half great tax minds right now.
Q&A: How Do You Handle Uncertainty Due to AI? (40:25)
Rebie: All right, well, this next one we’re going to speak a little more broadly. All three of you work with a lot of professionals, entrepreneurs, and a lot of different sectors. You have a lot of experience across all those things. So this person, Andrew, asks, “How do you handle uncertainty due to AI? I’m a software engineer. If I knew I could make my current salary plus inflation for 20 years, I’d be set. But fears of AI replacement keep me money stressed.” What would you say to Andrew and what are you guys seeing? Like, are you stressed about uncertainty due to AI for certain sectors? What do you think? If you had a client ask you this question, what would your response to that person be?
Jasmine: Is it a client concerned for themselves, or are you asking me if I’m concerned? And then I’m curious to know, are you concerned about it? Because I was going to say, I’m not concerned at all. I mean, a great person with AI is always going to be better than AI on its own. Right? And so it just comes down to being really good. And so there is a real fear for anyone that’s not good or not great. You know, it’s just, the AI will be great. So then you also have to add real value.
Bo: I love that. Here’s what I was going to share. I know from working with a lot of tech people that this industry is cruel. Once you’re 50 and over, I’m just going to tell you straight up because that’s not in the brochure for that industry. But I have a lot of clients who, somewhere between 50 and 58, this industry typically shows you the door, and you’re used to making great income. So just being in this industry, save like your life depends upon it. That’s because there is a chance that this industry, whether we’re talking about AI or not, you need to be saving and taking that responsibility seriously, because that industry has a tendency to shed people as they get older.
Brian: Now, bring in AI. If you’re really fearful, and I don’t know. Look, I kind of lean into what Jasmine’s saying. I think if you are talented, this thing is going to amplify you. It’s not going to necessarily replace you. But there are certain careers where you have to be careful. Are you on that bubble? You either need to take your skill to a different place or higher so you can kind of administer all these AI agents, or you need to figure something else. So I would probably use that as motivation to be aggressive with my savings behavior. And then maybe figure out how you make that army of dollars work for you just in case. Now, hopefully, that’s one of the things I’ve shared with you guys. When I was saving in my 20s, I thought I was leaving the workforce at 50. And now, as you can see, I’m over 50. I don’t like giving it away, you can see, no one look, but here I am. I love working, but I never regretted that I saved so hard in my 20s because it gave me additional flexibility and opportunities. So I think you could do the exact same thing, Andrew. Be fearful to the point that you actually change your behavior to save extra. And then if this thing turns out to be a big nothing burger, you’re not going to be hurt because of what you did for yourself.
Bo: Yeah, and I love what you said, a good person with AI is likely going to be better than AI on its own. So if you are concerned about your specific vocation or role, how am I adopting my skill set? How am I learning new things? How am I able to use this technological advancement to make me better at the very thing that I’m doing? Because I think when it comes to your work, if I can just keep myself in the top echelon, if I can be a top performer in whatever field I am, whether it’s a software engineer or fill in the blank, if I can make sure that my skill set causes me to rise to the top, I’m likely going to be positioned better to weather whatever sort of industry shifts might happen due to technological advances.
Jasmine: It’s also like, what skill set are you building? I know it’s easy to feel very niched and just do one thing repetitively over decades, but that’s where AI comes in. I mean, to me, it’s like being a great communicator, right? Being a great manager, like being very quick to learn and adaptable. There’s just always demand for that.
Brian: Absolutely. Like, good answer. Thank you for the question, Andrew. We appreciate you being here.
Q&A: How Do You Find a Good Tax Accountant or Financial Advisor? (44:41)
Rebie: Next question is from Wren. It says, “Hi, the Money Guys and Jasmine. Do you have any suggestions on how to find a good tax accountant or financial adviser? Such as good tax credentials, even for those who have not yet reached critical mass net worth yet. Thank you.”
Brian: Well, look, the best way to find… can’t wait to hear how you answer this one. The best way to find a financial advisor is go to moneyguy.com/become-a-client, obviously. But when it comes to hiring a tax accountant, when it comes to hiring a tax preparer, when it comes to a tax professional, this is probably the number one question we get asked. Do you do taxes for individuals? Like if they don’t have a business, in a full package with you, do you?
Jasmine: So we do kids’ tax returns, and we only do tax returns for business owners. And so if it was a kid of one of our business owner clients, we would do it. Yeah. But otherwise no, we don’t just do individuals without a business.
Brian: But you typically, didn’t you say $100,000 of taxation?
Jasmine: Yeah, a business, tax from a business.
Brian: Okay. And have you found in your experience that even though someone might have a designation, they might be an EA, they might be a CPA, they’re not all created equal? And so when it comes to finding a preparer specifically for individuals, because I think that’s what the question is, how do they do that? Like, how do you know if you found a good accountant, good tax preparer, or what should you look for to find someone who is sound in that industry?
Jasmine: You know, I think it’s like anything, a few things. So one is, first, I do emphasize the license. That’s not enough. But I do think someone should be licensed. It’s like a prerequisite. Yeah. It’s just, not to say there’s no one good out there that doesn’t have a license. There are, but it’s a minimum threshold. You have someone that they are held accountable to, right? Because the thing is, it’s like literally a person can get out of prison and then just call themselves an accountant. There’s just no monitoring of…
Brian: So you’re a good person because you have, like, every… you have EA, you have CPA, you have the tax attorney. What are the thresholds there to get them? No, no, no. Which ones is… so it was an EA. Is it just one of these three? Or is there a threshold?
Jasmine: You should go… I think it depends what you need, you know. So I do think if we’re talking like an individual tax return, not a complex business, definitely, I mean, probably you’re aiming for enrolled agent or a CPA.
Brian: Okay. Yeah. Yeah. So licensed.
Jasmine: And then to me, I always go back to, you should understand what’s going on. And so I think the most dangerous place that people put themselves in is they hire someone that says lots of fancy words that, if anything, makes it sound more complicated and confusing. So then they think that person knows, when really the best people are able to actually simplify it and make it understandable.
Bo: All right. We have a great resource, and a website you can go to, moneyguy.com, for anyone who’s hiring a financial advisor, no matter where you’re looking. We have these eight questions you should ask. Ask these questions and it’ll help you just kind of raise up: is this person someone who I should be talking with?
Rebie: Are there questions that our audience could ask an accountant? Not to test them, but to verify that they are someone they should talk to? It sounds like one of them is, hey, what’s your credential like? What qualifies you to be a tax preparer? Are there other questions, like tenure, client load, specialty areas? Are there other questions they should ask that would be helpful?
Jasmine: Sometimes I hesitate on those questions just because I think people lie.
Brian: Oh. So it’s like, oh, do you do lots of people? Do you lie? Question one: are you a liar? I think it’s a great one.
Jasmine: When people are like, oh, do you do lots of people in my industry, it’s like they’re just so, yeah, you know what I mean? So I just feel like those aren’t useful questions. I actually prefer, you said not to test them, but I actually prefer the test. Like, that’s what I do when I interview accountants. And we’re always hiring CPAs. It’s like, of course my threshold is very high, so I know I’m hiring. But give us a good test question. What’s the difference in tax basis between a partnership and an S corp? To me that’s a great one, obviously. And if someone couldn’t answer that question for businesses, though, obviously, you know, you could choose something relevant to, like, what’s the tax difference between a 401(k) or how do you do a mega backdoor Roth? Or, you know, you just choose a question that you can look up online that’s relevant to your situation. And then if that person can’t really speak to it at all, or like, let me think about it, they just probably don’t do your type of work as often.
Brian: I don’t mind sharing that. One of the things, because I was surprised when I sold my tax practice, I was an advisor. I was a tax preparer that was trying to always pay for my fee by looking, I would take into account every client and say, what do they do for a living? Are there things that they’re probably not utilizing that, if I did this for them or asked them about this, that we could recoup some of my fee? And I was shocked when I sold the practice. And I love the CPA firm that I sold to, but they’re more transactional, which, you know, versus a consultant, because whatever you show up with, they are going to ask you questions because they’re great at what they… I don’t want this to come off the wrong way, but it was different than probing for additional deductions and other things. And I think that’s probably the biggest shock people have when they work with tax professionals, is how many of them are more transactional. You show up with your shoebox full of stuff. They’re just going to take whatever’s in that shoebox, and they’re going to give you a tax return off of that. Whereas if you’re trying to work with somebody and you have a more complex or growing situation, find somebody who’s going to at least probe you in the right way to ask the questions, to see if they can find additional deductions that are legal. And because that’s the part I find too many CPAs are super analytical, and they don’t do the communication stuff that would actually create more deductions and opportunities for their clients.
Jasmine: Yeah, I do. Like, you find someone in between, because that’s where, to me, it’s like you’ve got your traditional CPAs and accountants, very reactive. I think part of that’s also how hard it is to run a tax practice.
Brian: Yeah. It’s so heavy. There’s also a lot of times underpriced. And so, their problem is they can’t hire enough qualified accountants to help. Not that they don’t have enough business.
Jasmine: And so what are you talking about? Everything I see on the internet is everything should be super cheap and fixed fee. You know, complexity doesn’t mean anything, is what I see all over social media. Yeah. So there’s that. And that’s kind of why people are like, oh, I hate my accountant, you know? But then what has popped up, especially with social media, is then the other alternative where it’s really just like a marketer with fancy language who’s just overcharging for something really simple. And so they’re making it sound kind of like, you were saying, well, find someone proactive, but you just got to be careful of finding someone that’s really just marketing. And it’s not really being like a true advisor. And so that sweet spot is in between. And it’s hard. You know, I think sometimes it’s like maybe CPAs are self-selecting. A lot of them maybe want to be behind the desk, like the most qualified people are like, please don’t talk to me, you know, whatever it is. But finding someone in between, where it’s like they care or they want to be a detailed advisor, but they’re not giving you BS.
Brian: Yeah, I love that. Good thoughts. I will say, you know, lastly, because a lot of firms, because of their workload, are trying to make more and more things automated. And I’ve had clients who I’ve referred to CPAs. They say, you know, I got an email from the CPA where they don’t even want to do that in-person meeting anymore. That is the nature of the industry. It is getting to where we’re going to be dumping more files into systems. And then you put in the box, output comes this way. What you put in, interview, you talk about these things with your CPA and be prepared, because all these things are going to have a cost. If you want to have that in-person meeting with your accountant, then that’s probably going to have a cost, because time is value. And I just want people to be prepared for that.
Rebie: Yeah, that could be really important.
Brian: Well, no, but it is. This is where the world is. This is where the world is going. People are trying to streamline the transaction, which makes it potentially cheaper. But if you’re counting on somebody to have a sit-down with you, there’s a cost to that.
Jasmine: Yeah. There’s a supply deficit right now with accountants. Right? It’s like they keep retiring. Honestly, a lot of people burn out with tax. A lot of people are like, I want to leave this industry. And it just goes that direction. So, yeah, I mean, figuring out what is highest value for you. I know if it is that in-person meeting, then that’s what’s high value for you. But it comes with the cost.
Rebie: Yeah, yeah. Good thoughts, good thoughts.
Q&A: Selling UTMA Holdings to Take Advantage of the Kiddie Tax (52:53)
Rebie: All right. We’re going to go to User 55717. Oh, just off that name, we probably did not read this question. It says, “Can or should I sell holdings in an account to reset the cost basis slowly over time to take advantage of the kiddie tax?”
Bo: Okay, so quick vocabulary. For those of you that aren’t familiar, a UTMA account is just a custodial account held for a minor, so you, as the parent or grandparent, serve as the owner of the account and the minor is the beneficiary. And so you might hold this account and you might invest in something like an individual stock or a low-cost index fund that does well through time. Well, one of the things the user’s thinking is, oh man, okay, this kid for whom I own this account, I could likely sell the holding that I have and that it’s done well. But because they’re in such a low tax bracket, they’re not going to pay any income tax, any capital gains on that because they’re so low. Is that a viable strategy, is that something that User 55717 could potentially carry out?
Brian: I don’t know what they mean, but take advantage of the kiddie tax like it’s a bad…
Jasmine: Yeah, I know. Yeah.
Bo: Like essentially sell a holding that’s appreciated, not have to pay capital gains tax, sell it at a capital gains rate and then just rebuy the same holding again as a way to wash and clear out that gain.
Jasmine: When you incur the kiddie tax, like that’s you’re incurring the tax bracket of the parents. Right? So this would have to be below the threshold, but where the tax will take effect…
Brian: I’m sitting here, I’m mad. We’re doing a tax show, and my normal cheat sheet, this was not one that had a draw. There’s no draw there. I don’t have any of my tax numbers that I normally do. But it’s typically, they’re talking about the zero tax capital gain. But what I don’t know is the asterisk on, because it’s back to your point, you know, paying taxes at the parents’ tax rate. What I would need is a little more context. So it sounds like in 2026 the kiddie tax thresholds for a child’s unearned income, the first $1,350 are tax-free, meaning if you sell this capital gain and it’s less than $1,350, it’s probably going to be taxed at 0% for the next $1,350. So between $1,350 and $2,700, it’s going to be taxed at the child’s own tax rate. Once you go above $2,700 of unearned income for a child, that’s where the parents’ tax rate kicks in. So if you are selling this account, you fall below those thresholds. I do think that it’s probably viable that this person would pay 0% income tax, and it would be okay to do. I would ask one more question, like, is the zero capital gains tax rate integration with the kiddie tax, is $2,700 the correct number? Because it’s just to be careful. Once again, back to the code section, reading to make sure there wasn’t some carve-out, because legislators a lot of times, the kiddie tax was enacted so that people wouldn’t manipulate. So I just want to make sure before we lay something out there. It doesn’t mean you wouldn’t get away with it, but I just want to make sure we’re on solid ground with that, that there was not an asterisk in there to carve out on the zero capital gains tax.
Jasmine: Yeah. I mean, I think, you know, some of these things I’m like, wow, we are talking some really small numbers to be beneficial. So, but yeah, I think a lot of times it’s not worth the squeeze. But sure, I mean, if you were super detailed, you made sure you’re not going to run into some problem, then it sounds like there could be a very small tax benefit.
Brian: This is why you’ve got to be careful bringing on Jasmine, who deals with clients who only have at least $100,000 of taxes. She’s going to totally pop around our audience, and they’re trying to squeeze a little extra juice out of that. I think we talk about the hassle factor too, like, you have to think through that. Like, is this actually… neither one is wrong, by the way. I love our financial mutants, but Jasmine’s not wrong either.
Jasmine: I just fundamentally, obviously, I think about things from a business owner perspective, but fundamentally it’s like my money’s my money, but my time is my money and my energy is my money.
Bo: And so a lot of people want to destroy their time and energy to try to save very little money, you know, like, I know this guy. He used to shop online. Whenever you shop online, he would spend an hour, hour and a half on coupon codes, like Nike coupon code, coupon mountain, coupon, like all this. And he would literally spend an hour to try to save $4 on shipping.
Brian: There is actual content out there called Triple Stack, I mean Triple Deal Saving Ninja or something like that, where I was talking about how you could layer your coupon codes with your shopping portal with… Do you know the guy that he’s got about me?
Bo: Of course. Yes.
Brian: I used to be so tight with every dollar. Now I will say middle age has changed me in some ways. I don’t know if it’s kids, success, whatever it is, but I will pay for convenience any day of the week. It’s like the highest value thing for me.
Bo: You have figured this out much earlier than I have. I kept these tightwad ways way too long, probably. I think you’ve moved past it now. You’re in a better place.
Brian: You’re still sitting out there, about to pick on me. And you can go find something. Ninja. Just so, if you look for Ninja, we don’t do it. Show archive. You’ve got to search the content for Ninja. You’ll probably find it right up, for sure.
Closing (57:54)
Brian: Jasmine, thanks so much for hanging out with us. This was awesome. You did not disappoint. We came in expecting you to be a tax wizard and you were, in fact, a tax wizard.
Jasmine: Thank you.
Brian: If folks want to know more about what you have going on, how to connect with you, how to follow your content, where can they go to learn more?
Jasmine: Yeah, a great place, Jasmine DeLucci, that’s our website. And then slash roadmap. You can get the free tax planning roadmap.
Brian: Love that. What about if they want to follow you on social, keep up with all that stuff?
Jasmine: Tax Leverage. At Tax Leverage.
Brian: Love it. This was a blast. Thank you, thank you, thank you. And look, I will say Bo’s hung out with me enough. I mean, if I could deem him an enrolled agent or CPA, an actual CPA, he’s going to find that, like a knight with a sword. And, you know, I would put him on both shoulders because, I mean, he’s gotten good. But I love your content. I really do, because I feel like you cut through the noise because there’s so much noise out there in the content sphere. And I appreciate what you’re doing because I think it’s educating people and it’s helping people. So if y’all aren’t familiar with Jasmine’s content, go check it out, especially if you’re a business owner. I think you will leave either being scared to death or at least, you know, knowing a little bit more.
Jasmine: Yeah. Thank you. Yeah. No, I love it. I mean, when I dreamt about being a tax attorney back in eighth grade, I thought, you know, I’d be behind a desk and all of that, and I enjoyed that as well. But I’m like, there’s nothing more fun than actually sharing with people on the camera.
Brian: Yeah. That’s awesome. Guys, we gave away tons of advice today. If you also want to go, just take advantage of our free stuff. Bo gave it out a few times. Go to moneyguy.com/resources. If you’ve reached the level of success, not only from the tax, but from financial planning and knowing how to do things, don’t let this be a novel thing where you’re trying to do everything yourself. We’ve literally done this thousands upon thousands of times for our wealthy clients. We work with clients all across the country. Reach out to us, take the relationship to the next level. I’m your host, Brian, joined by Bo and Jasmine. Money Guy out.
Free Resources

Free Resources
Financial Order of Operations®: Maximize Your Army of Dollar Bills!
Here are the 9 steps you’ve been waiting for Building wealth is simple when you know what to do and the order in which to...
Free Resources
Wealth Multiplier By Age
If you want to set yourself up for future success, find out how much you need to save every month to become a millionaire.
Free Resources
Car Buying Checklist
Here’s how you can buy a dependable car that won’t break the bank. Our free checklist walks you through the 20/3/8 rule and strategies to...
Articles

Articles
How To Win With Money in Your 20s (and Set Yourself Up for Life)
The first decade of adulthood is one of the most important periods of your life. The course your life takes when you are younger can...
Articles
The Best Tools for Filing Your Taxes in 2026
Have you filed your taxes yet? You still have ample time left until the April 15th deadline, but it’s probably best not to procrastinate too...
Articles
6 Financial Changes To Make in 2026
There is no need to wait until an arbitrary date on a calendar to make positive changes in your financial life, but if you are...
Financial FAQs
Courses & Tools

How about more sense and more money?
Check for blindspots and shift into the financial fast-lane. Join a community of like minded Financial Mutants as we accelerate our wealth building process and have fun while doing it.
Free Resources
Financial Order of Operations®: Maximize Your Army of Dollar Bills!
Here are the 9 steps you’ve been waiting for Building wealth is simple when you know what to do and the order in which to...
Free Resources
Wealth Multiplier By Age
If you want to set yourself up for future success, find out how much you need to save every month to become a millionaire.
Free Resources
Car Buying Checklist
Here’s how you can buy a dependable car that won’t break the bank. Our free checklist walks you through the 20/3/8 rule and strategies to...
Recent Episodes

It's like finding some change in the couch cushions.
Watch or listen every week to learn and apply financial strategies to grow your wealth and live your best life.
Episodes
Financial Advisors Versus the Internet
Can you write off every family vacation as a business trip? Should you cash out your 401(k) to buy a rental property? Is paying a...
Episodes
Top 10 Mind-Blowing Money Stats (2026 Edition)
Are you on the right side of the data? In this annual classic, we reveal 10 mind-blowing 2026 money stats and personal finance strategies to...
Episodes
Here’s How Much Income Puts You In The Top 10%
What income puts you in the top 10% of Americans? We break down the numbers, bust common myths, and answer your biggest personal finance questions...