-
▼
-
▼
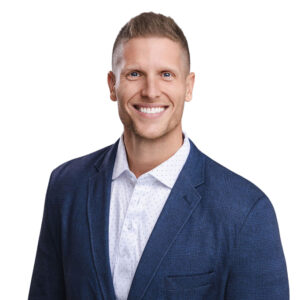
Joe is 28 years old, earning around $107,000 a year, and has gone from $120,000 in student loan debt straight out of college to a positive $70,000 net worth. That alone puts him ahead of most people his age. But what makes his story so compelling is how he got there. A few unconventional choices, including a sneaker collection he treats as a hobby investment and a Bitcoin position he calls a hedge, sit right alongside real discipline around budgeting, living at home to accelerate his debt payoff, and consistently maxing out a Roth IRA even while carrying five separate student loans. In this episode of Making a Millionaire, we dig into his full financial picture and help him figure out whether to aggressively pay off debt or keep funding his Roth IRA at the same time.
Using nothing more than his current savings rate and the power of compounding, we break down what his portfolio could look like by 50 and again by 65, and the results make a strong case for why starting early, staying consistent, and following the Financial Order of Operations matter more than the size of your paycheck. If you’re paying off student loans while trying to build wealth in your 20s, this episode offers practical personal finance lessons you can use to build smart habits and master your money mindset.
Enjoy the Show?
Where You Can Watch and Listen:
Subscribe on these platforms or wherever you listen to podcasts! Turn on notifications to keep up with our new content, including:
- Episodes of The Money Guy Show every Friday
- Episodes of Making a Millionaire every other Monday
- Mini-shows every Wednesday
- Ask Money Guy Livestreams every Tuesday
- Tons of other fun content!
$120K in Student Loans to Positive Net Worth (0:00)
Brian: You start at negative $120,000 six years ago and here you are with a net worth of $70,000. When you came out of school, what was your plan after you took out these loans?
Joe: I never touched them. I didn’t know what was going on with them.
Brian: If you went from $120,000 down to $76,000, minimum payment…
Joe: I didn’t want to start paying down debt with nothing to my name.
Brian: I can’t remember how much your shoe collection was last year. Do you remember?
Joe: I don’t necessarily use it in an arbitrage way where I’m trying to make money off of it. It’s a collection.
Brian: You know, what are you going to do with them if you don’t wear them? What about the crypto?
Joe: If there is an opportunity to change the way that we do money, I’d like to at least have exposure to it.
Brian: Are you really changing the world with a Coinbase account?
Joe: Not changing the world, it’s a hedge.
How Joe Ended Up $120K in Debt (0:47)
Bo: All right, Joe, so give us the background. Who are you, man? What’s the background? Where do you come from? And why are we sitting down here today?
Joe: I applied because I think that what you guys do is absolutely amazing, first of all, so thank you for that. My story basically goes back to the good old get a college degree. The college degree that I got was something in like graphic design.
Bo: Where did you go to school at?
Joe: I went to Wentworth in Boston, right next to Fenway.
Bo: What’s funny is I went, a couple years ago I’m in this entrepreneur group, we went to Boston and got to do Fenway, we actually got to take batting practice in the cages, not on the field but in the background whatever. That’s a cool area, I had never been there before, had never walked around, seen all that, it was awesome.
Joe: So I ended up going there and not really understanding what it is to take out a bunch of debt at the end of the day.
Brian: You’re not alone in that, a lot of folks that’s their story. Hey, give me the mindset, because you’re not that far removed, we’ll get what your age is here in a second. What does a student feel like, so that young people who watch this can kind of watch out for the trap?
Joe: The thing that I did was I just went to school and had fun. I mean, and listen, I didn’t do anything bad in terms of, like, I got really good grades, but…
Brian: Did you use student loans for lifestyle?
Joe: No, I actually didn’t really use it for, I mean, a little bit maybe. I wanted to live off campus one year, so because of that I took out a little bit of debt to go ahead and get an apartment with some of my friends and stuff like that. But that wasn’t super major, I don’t think. More it was just like the degree that I got itself was way outside of like some of the stuff that you guys preach today with being inside a certain amount of range of money, so that you’re not spending this incredible amount of money and then the job that you get out straight out of school is not covering the amount of money that you had.
Bo: How much does one worth cost? Like how expensive of a school is that?
Joe: I feel like it just kind of depends on obviously what degree.
Brian: How much it cost for you?
Joe: In total, all in, it was $120,000.
Brian: 120 grand. How much student loan debt did you run up? That was it, that was the whole thing?
Joe: Run up 100. So no scholarships, no outside money, just student loans. And that’s another thing that I would say that people really need to do and take part in, is, like, I just didn’t care. You know what I mean, I was like, hey, my mom, we’re taking out the loans, starting salary coming out of college around 65. So way outside of the guidelines that we would have liked to be in just in the beginning.
Brian: Going back in time, would you have changed colleges, changed majors, what would you have done differently?
Joe: I don’t think I would have changed the major. I think a lot of the people that I met, the experiences that you get, that’s, once you experience it once you really wouldn’t trade it. So it’s hard to say that you wouldn’t do that again, right? But in terms of how much I would have paid, the scholarships that I would have applied for, the off-campus housing that I would have gotten, I would have definitely stripped a lot.
Brian: Would you have considered going to community college for two years and then transferring in, or would that not be feasible?
Joe: I honestly don’t know, I feel like I don’t think that I really took away anything from the experience if I did that.
Brian: And by the way, we’re not here to go back and redo, we don’t have the DeLorean, so we’re going to get you out of whatever situation you’re currently facing. I’m just curious because I think it’s truly something that all young people are facing right now. So if we can put a light to something that somebody can watch and be like, hey, or maybe you got kids that are close to going to college, I just want to shed a light on that. Because college is so noble, but it’s so noble that we’ve all fallen into its kind of alluring trap of not thinking that you have to pay attention to what the end goal is. We think it’s all noble, just go to school and it’ll all work out and get that degree, just like you said. But if you don’t know what you’re actually going to be making for a living and what the debt is at, you can find yourself in a bad situation.
Joe: Exactly. And my dad, my mom’s first generation here and my dad moved here from Italy when he was 21, he didn’t know the language. So for me to have the opportunity to go to college, it was like, oh my god, this is, I want my son to go through this and experience that. So I went straight into it, I was like, this is exactly what I have to do regardless of the job that I was going to get outside of college and whatnot. And that put me in a pickle straight out the gate. And then that’s kind of when I found you guys. Like literally at that exact moment I was like, I have to figure this out, I have to do something, there’s got to be a better way to do it. And started watching you guys back in 2020, because I graduated August 2020.
Brian: Okay. And how old are you now?
Joe: 28.
Bo: 28 years old now, and you graduated in 2020, and when you graduated you had $120,000 in student loan debt right out the gate.
From Negative Net Worth to $70K (5:10)
Brian: If you did a net worth statement in 2020, were you like negative $120,000, do you have anything else going on, or was that…
Joe: I probably had around $10,000.
Bo: Okay, so it was like you’re starting from a hole. And again, I think a lot of young people find themselves in that position. What I think is really awesome though, you’re 28 years old, so we’re 6 years removed, you were kind enough to share a net worth statement with us. When we look at it right now, 6 years in the future, you are not at $120,000 anymore. I mean, I was already impressed to take $120,000 down to $76,000 in a short period of time, pretty impressive already. And then to see that you actually have stacked on top above and beyond the debt. Dude, you’re painting like a sad story here and I’m trying to figure out how we can throw some rays of sunshine, and then you’ve already done it. I mean, this is already kind of a redemption story in the making right now.
Joe: Yeah, definitely. And it was just through everything that you guys preach and also a lot of hard work at the end of the day.
Bo: Well, I want to know more about that. Right, so you start at negative $120,000 six years ago and here you are with a net worth of $70,000. What did you start doing when you came out of school, what was your plan? You said you’re making $65,000 a year, how did you even find money to start chiseling away at this? Walk us through what you did.
Joe: So one of the blessings that I did have was being able to live with my family.
Bo: Okay, that is like after school?
Joe: After school, yeah, I stayed at home. So that definitely did wonders in terms of the ability to save some money, and then also just heavy budgeting at the same time. A mixture of those two things created enough margin for me to be able to go ahead and start the Roth. And that was the beginning of my journey.
Bo: I think it’s so great for young people to hear that you made the decision. Do you still live at home now, or are you out on your own?
Joe: I move out the 28th of this month.
Bo: You’ve been living with your parents, do you regret that decision? Because you know a lot of people, they graduate like, oh, I can’t go back home, and not recognizing that it could be this wonderful opportunity if your parents are in a situation where that’s a possibility, to let you really start stacking cash and changing your future financial trajectory. If you were talking to a graduate right now that’s trying to decide, okay, do I go back and live at home or do I just go huff it on my own, what would you tell them?
Joe: I would tell them that obviously personal finance is personal, that’s number one for me.
Brian: Where’d you get that from?
Bo: I don’t know, somewhere, that’s an echo.
Joe: That’s exactly what I would tell them though, because it was like for me there, that was the option. It was like if I want to be able to move forward in my life post this, that was the sacrifice that I had to make and I just wanted to be smart about it. Did I want to do it? No, not necessarily, but we all do a bunch of things that we don’t want to do at the end of the day. Looking at it from a holistic view and not trying to sugarcoat it, I think is the best way to go about it.
Bo: So you’re living at home, you’re saving money on rent, you said you started budgeting. How did you set up your budget? How did you know how much to pay towards student loans? How did you know how much to spend eating out? How did you decide categorically where to put your money?
Joe: I think I kind of worked backwards from it a little bit. I was more of just like, I really want to knock down this debt, and what’s the best way for me to do that is to say, hey, I want to put this amount towards the debt to get rid of it in this amount of time, and then whatever was left over was the thing that I kind of played with.
Saving 40% While Paying Off Debt (8:13)
Brian: So what is that plan right now, because it must be pretty aggressive to go from $120,000 down to $76,000?
Joe: Yeah, I was probably saving for a long time, close to 40% of my income.
Brian: That’s awesome.
Joe: Now part of the reason why I also wanted to come on the show was to get your advice on some of the things that I can do moving forward now, because I am moving out, right, I am moving out next month. That is another expense that we see that’s going to be on the list. And the savings rate is dropping dramatically to around 11%, even though I found, I’m living with someone, so the price would be a little bit cheaper. And 11% is just not going to cut it for me though, so it’s like building a plan around that and figuring that out would be awesome as well.
Bo: Well, walk us through your current saving. When you think about where your dollars are going right now, how much are you putting on student loans and how much are you putting into your other investment accounts? How are you navigating that?
Joe: I just max out the Roth every month, religiously, in preparation for the show as well. I stopped doing all of the excessive investing that I was doing and I kind of pulled back and said, based on what kind of recommendations I get here, at least I’ll have a little pot of money to go ahead and make some decisions with. Other than that, the debt is also something that I have to tackle. So the only thing that’s set up automatically currently is just your Roth IRA being fully funded, and then basically everything else that’s outside of the budget just goes towards a savings account and then I delegate that where I think it should be that month.
Bo: About how much is going into that savings account? What’s the excess capacity with which you have to work every month?
Joe: It was all of the rent basically that I’m going to start paying now.
Bo: So about $1,700 a month is what you did have in excess, but now that’s about to get consumed by rent?
Joe: Exactly.
Bo: And when we look at your student loans, you have a number of different student loans, number of different interest rates. How have you prioritized paying them down? If you have a bunch of different ones, a bunch of different rates, what strategy have you employed?
Should He Pay Off Student Loans Faster? (10:04)
Joe: So I have done something that I think is kind of a sin over here.
Brian: What is this?
Joe: I basically just make minimum monthly payments on everything, and I didn’t prioritize any of that stuff to begin with. And the reason why I say that’s kind of like a sin based on what we’re doing now, is because some of these interest rates are really high. I didn’t want to start paying down debt with nothing to my name, and I understand that that may be a little bit out of order depending on the way that we look at things, but that was really what I wanted, I wanted inflation to eat everything away.
Brian: But if you went from $120,000 down to $76,000, you obviously have been paying more, right? That’s not the minimum.
Joe: Well, that’s the payment that we see there, the $1,500 is what I’ve been paying, it’s been 5 years now.
Brian: So it’s not interest only, this does have, what’s the repayment window that you’ve elected?
Joe: I don’t know necessarily, it’s probably a shorter window pay, but I didn’t, after we took out these loans I never touched them. I didn’t know what was going on with them, I was not informed with anything, I didn’t make any good decisions behind it. I kind of just let whatever happened happen at the end of the day.
Bo: And so my guess is if we’re six years into this and it’s gone from there to there, we’re probably on a 10-year amortizing note paying $1,500. Do you know how much is going towards each loan? Like if I ask you how much is going towards parent plus one, parent plus two, do you know those numbers, or you just know $1,500 total is going?
Joe: I could probably break it up a little bit. I mean, I know that there’s like $700 for the private student loans or something like that. I honestly couldn’t give you exact details, I have it in the slide sheet, but not necessarily.
Brian: Yeah, we’ll probably make that part of the homework, because I can imagine we’re going to have you have competing goals here. So we’re going to need to prioritize your goals, and we will use the interest rate, because you have about $42,000 that we would probably want to be somewhat aggressive on. And then some of these others, they don’t panic me as much. If you’re balancing between funding a Roth versus paying down a low interest rate student loan, I’m going to want you still keeping that Roth going, so we’ll have to work through the priority on that.
Bo: And I want to give you, you said, okay, well, it’s probably going to be a sin over here that you paid some of these down, we would argue at your age, in your 20s, not all of these would qualify as high interest. I think when we look at this, maybe perhaps one of them would fall into high interest, maybe two of them, but the others don’t give us a lot of anxiety, because we do think that your money could likely be deployed better elsewhere.
Sneakers, Gold, and His Investments (12:36)
Bo: But I need to understand about what you’ve been doing from an investment standpoint, because I see two asset categories on here that I was, or three asset categories on here that I was not expecting to see from an investment standpoint. Now, Brian, you and I every year we do our net worth statements and we’re buddies, right, so we’re super close, we kind of share them with each other. I can’t remember how much your shoe collection was last year, do you remember? I don’t remember what that was.
Brian: And full disclosure, Joe’s profile photo that kind of put him to the top of the heap. But I’m sure there’s a fancy name for them, but they looked like Elmo shoes. I mean, so some of these shoes are eclectic, is that a fair way to say?
Joe: Yeah, 100%. Some of them are like a little bit of an investment, some of them are just personal stuff. A lot of the things that I collect now are like 1990s Jordan retros that have never been worn, with the original box and stuff like that. And that’s just something that’s fun for me.
Bo: So you don’t wear them, this is not, you’re not showing these shoes off, you buy these shoes, hold them, it’s a collectible type investment.
Joe: Yes, exactly.
Brian: Have you made, like, you’re saying this is worth four grand, what do you have in this?
Joe: Probably close to that.
Brian: The reason I ask is, look, we know people, and I’ve used this example before, we had a Disney pin collector who was incredibly good. We always hear the saying, the two best days to own a boat is the day you buy it and the day you sell it, but I got to tell you, we had a client who knew the boat market so well that he was flipping them for profit left and right, because there’s a lot of inefficiency in the boat market, there’s a lot of inefficiency in the Disney pin market I come to find out. I would be curious the shoe market. I have no problem if you want to do this, if you’ve created an expertise that lets you be the shark versus the lamb, but right now, are you shark or are you more lamb?
Joe: I don’t necessarily use it in an arbitrage way where I’m trying to make money off of it, it’s just a collection.
Brian: What are you gonna do with them if you don’t wear them?
Joe: Glass display cases, maybe that works at the end of the day.
Brian: And honestly, how big is your apartment?
Joe: I will say that this collection that I’ve been building has been since high school, it’s not like something that I’ve just recently started dumping a bunch of money into.
Brian: Will this be displayed in your apartment?
Joe: Depends, if you come over.
Brian: At this point, how many shoes does it take in a shoe collection to equal $4,000?
Joe: It probably wouldn’t be much if I had really really high-end stuff, but 30 to 40 shoes.
Brian: 30 to 40 pairs, enough to take up a whole wall. Okay, so maybe that’s not really an investment, maybe that’s more of sort of a use, this is a thing that you enjoy that you perhaps could sell, but it’s not so much an investment.
Joe: That’s exactly what I would refer to it as.
Brian: Okay, so what about the $10,000 in gold, what’s going on there?
Joe: That is 100% just all jewelry, it’s all handed down.
Brian: Okay, like family, something that’s passed down, you didn’t go out there trying to buy gold?
Joe: No, definitely not.
Brian: Okay, okay, okay. So we got a use asset on here, the shoes, not really use asset, but like a hobby enjoyment asset, it’s like home decor.
Should Bitcoin Be Part of His Portfolio? (15:35)
Bo: Gold is more of like a family heirloom.
Brian: Okay, I’m feeling better, I thought I had visions that you’re out there buying ounces of gold or something. So, all right, so then what about the crypto, that’s the third one that I’m like, all right, when I see these other things, what’s going on there?
Joe: A little different. The crypto is strictly just Bitcoin at the moment, and the reason why I gravitated towards having a percentage of my portfolio being in crypto is, if there is an opportunity to change the way that we do money in that sense, I’d like to at least have exposure to it.
Brian: At the end of the storage, or do you have an account?
Joe: It’s just an account.
Brian: Like a Coinbase?
Joe: Yeah.
Brian: Are you really changing the world with a Coinbase account?
Joe: Not changing the world, it’s a hedge, that’s all, it’s just a little hedge.
Brian: Because this is the thing I always talk to crypto people about, if you had cold storage, I get it, because you’re kind of independent, you just don’t lose passcodes or whatever else, but when you’re part of Coinbase and other things, are you really changing the financial system? Because I don’t know if you saw the big stress test, I’ve seen it with the Iran war that they’re doing, you see it with the Canadian protesters, they went in and took wallets. So it seems like we have the illusion that we’ve created a new system, but it’s not as independent as what’s in the brochure. Sure does seem like the governments have no problem navigating around these systems.
Joe: Yeah, and I won’t argue that point at all. It was more of just like, this is something that I’ve always just kind of bought and never sold, there was no gambling.
Brian: I’ve even dabbled. I dabbled in Bitcoin, I was just always curious, because I dabbled and then I got out, because what got me was just the volatility of it. I just couldn’t believe how much we were ripping and roting on this thing all over the place. And as a matter of fact, the last time I talked about this, I was picked on because, you know, Bitcoin has gone where it went all the way up to what, 128 something something crazy. Yeah, 128,000, and then now we’re back in the 60s, it’s been a long ride. And that’s the thing, is that before we actually can treat it as, it’s not a currency I don’t think, because the pricing is going way up, because if you’re dealing, if you imagine if you’re buying pizza, using Humphrey Yang’s example, and the pizza one day is going to cost you 10 bucks, but then the next time it’s $64, you’d be like, this isn’t a good thing to pay for pizza with. So it’s more of a speculative play, of course, and as long as it’s a hobby I’m okay, but the problem I’m worried about with you, Joe, you don’t really have room, if you think about the pyramid of investing, speculating is kind of at the tippy top, after you’re at the fun stage of, hey, what do we do with all this money we got laying around, you’re kind of still at the fundamental, let’s make sure this army of dollar bills has a purpose so it can hopefully help me quit working so hard, or at least extinguish some of this debt over here, I think it’s the wrong time to be jumping on the speculation train.
Bo: And with the crypto, are you allocating to it still, still allocating to it, or do you have this position and you’re just holding it?
Joe: Yep, just a position that is holding.
How He’s Using His HSA (18:47)
Bo: Okay. What about the HSA, is that something you’re actively contributing to and letting invest and grow, or are you using those dollars for current medical expenses?
Joe: I actually got access to that this year, so I’ve been contributing to that and investing it, just per usual, I think it’s about $100, $80.
Bo: If you had a medical expense pop up, would you use that to pay for it, would you pay for it with outside resources?
Joe: Probably outside resources, a lot of the money that can be invested is invested, so I’d rather not touch it at the moment.
Brian: What’s your deductible, do you know what your deductible is on your plan?
Joe: No, I don’t.
Brian: Because that’s what I typically like, people, if you’re going to start investing the HSA, let’s at least put the deductible kind of in a cash equivalent and then we can go above and beyond, and I bet your deductible is going to be higher than $1,600.
Bo: When I’m thinking about what’s about to change in your life right now, you were kind of sharing your budget with us. Right now, once your rent starts, you’re going to have about $5,000 a month flowing out for expenses. How much extra, because you’re trying to figure out how do I prioritize paying off the student loans, saving, building, how much extra margin are you going to have on a monthly basis to fund some of these goals?
Joe: That’s the tough part.
Brian: What’s your take home? Because we see your salary was around $107,000, $9,000 gross a month.
Brian: Yeah, so what’s your take-home after your health insurance? And do you have a retirement plan?
Joe: I do not, no, I don’t have one.
Brian: Your employer doesn’t offer one, or you chose not to be part of it?
Joe: Doesn’t offer one at the moment.
Brian: You got to go out there and lobby them. Are you an independent contractor or are you a W2 employee?
Joe: A W2.
Brian: How many employees does your company have?
Joe: 13.
Brian: I think they don’t have a 401(k)?
Joe: No, not at the moment.
Brian: Come on guys, get this going, send this video to your boss and be like, hey, do you realize, especially boss man, do you realize how much money you can hide from the government legally with a 401(k) and do good work for your employees?
Joe: I’ll have to be the initiative on that one.
Brian: Sure. All right, all right, we can keep it going. So $9,000 gross income, what hits your checking account every month?
Joe: So I do a little bit of side work, so that kind of muddies the water in terms of what I actually get.
Brian: Is that in the 107?
Joe: Yes, it’s not a lot, it’s probably close to around $10,000 a year of just side income. So deducting that and whatnot, I probably have around $5,200 to work with every month.
Bo: Oh wow, okay. So if you have $5,200 net coming in somewhere around there, we got $4,800 going out, we really got 400 bucks access to work with, is that right?
Joe: Yeah.
Bo: And is that what you’ve experienced?
Brian: Wait a minute, you’re letting him off way too easy. Well, I’m just doing math, $4,800. I have a screen here that says your income is $107,500 and your net’s $5,200, there’s a spread there. How much is this side hustle?
Abound Wealth (21:53)
Bo: But one of my favorite things about recording Making a Millionaire is every one of our guests has a different situation.
Brian: That’s so true. One couple needs help getting out of debt, another person is trying to figure out retirement, and there’s the guy who’s just spending way too much on horse massages.
Bo: Yeah, that’s true. Each person has different goals, different opportunities, and different blind spots. And it reminds me a lot of what we get to do every day here at Abound Wealth.
Brian: Yeah, we sit down with our clients, we learn what’s important to them, and we build a plan that’s tailored to their life and their specific situation. If you’ve been watching this conversation and thinking to yourself, hey, I wish someone would help me figure out my situation, we’d love to have that conversation with you. We’re fee-only fiduciary advisors and we’re here to help.
Bo: That’s right, just head over to aboundwealth.com or click the link below, we’d love to connect and see if we’re a good fit for you.
Brian: How much is this side hustle? It’s more than 10 grand then?
Joe: No, no, it’s not. Well, maybe my income is a little bit higher, maybe 56 or something like that.
Bo: It’s not that different, because it’s just too much of a spread here. Well, so if we take $108,000 and you take $10,000 off of that, now we’re going to be at $98,000. If you take $98,000, you divide that by 12, that’d be a gross monthly income of about $8,100. So we got $8,100 gross coming in, and you’re saying that you’re netting about $5,200 of that $8,100.
Joe: Yeah.
Brian: that would be a 36% health insurance coming out of that.
Bo: Okay, so health insurance, how much is health insurance?
Joe: That’s a great question, I don’t know.
Brian: Joe, give me a guesstimate, because this is the accountability side of things.
Joe: Yeah, I really don’t.?
Brian: $500, $400?
Joe: Probably close to 400.
Bo: He’s on a high deductible plan, so you’re going to assume it’s going to be one of the less expensive plans, so maybe it’s like probably $4 to $500 individual for high deductible plan. Anything else come out of your paycheck, other than your health insurance?
Joe: Well, the HSA of course, and that’s, you said about $100, $80 a month.
Bo: Yeah, $80 bucks. Okay, keep going.
Joe: That should be it really.
Bo: All right, so the math that we’re doing is, if you take $8,100 minus $80 for HSA, that takes it down to $8,020, minus another $400 or so for health insurance, that takes it down to $7,600. You got to help us, $7,600 is what we’ve calculated should be hitting your checking account, but you say you only have $5,200 to $5,600. Where are we missing?
Joe: Yeah, it’s got to be in the side hustle income at that point. Maybe I’ve overestimated the amount that I kind of get from that on a month-to-month basis.
Brian: Because the reason we’re squeezing on this is we want to know how much money do we have to work with. I don’t want to give you false perspective that we’re going to be able to pay these student loans off in 18 months, and then we find out no, I mean, you couldn’t even eat ramen and make that work. That’s why the important part of personal finance is the quality of the data that we put into the system, because especially for young people, I mean, we changed the variable on your rate of return from 8% to 12% and it looks like, oh, you’re great, you can make it with 26 cents a month and you’d be all right. But in reality, I’m being facetious, of course, but that’s why we have to get the data points right, otherwise we’re going to give you a false sense of security, and that wouldn’t be doing you right either.
Joe: Yeah, so the net that’s coming into my account on a month-to-month basis from my job, from my W2, is closer to around $5,600.
Using a Side Hustle to Build Wealth (25:14)
Joe: That’s the number that I want to work with. And then the side hustle income is sporadic, but I can make extra money on the side.
Brian: And what do you do with that side hustle?
Joe: So I’m a graphic designer and like a brand identity person, so I do a lot of logos, colorways, fonts, advertising, stuff like that for people.
Brian: Would it be okay if we earmark that for specific purposes?
Bo: If we build a budget or if we build a plan off of $5,600 based off of what you have going on automatically going out, then essentially we assume the side hustle money doesn’t exist, and then when it does exist, that’s what we want to go deploy towards student loans or towards building assets or towards these other goals, just because you’re pretty lean with your inflow and your outflow. So your side hustle is going to be where all the margin exists, does that make sense?
Joe: Yep. I love that.
Bo: And so realistically, if we’re going to operate on how much can you make side hustling, how difficult would it be to make $10,000 a year side hustling?
Joe: I would say not very difficult.
Bo: How about $20,000 a year side hustling?
Joe: Way more difficult.
Bo: How about $15,000 a year side hustling?
Joe: Still probably cutting it closer.
Bo: So 10,000 is, and that’s given it all you got, if we were really motivated to try to get this debt and other stuff out of here?
Joe: Given it all I got, it’s probably not, no, I probably could go a little bit harder, but I would say let’s keep it at that.
Brian: Well, the reason, here’s the reason from a mindset standpoint, you’re young and single right now, so you have this whole trade-off with how you use your time. You’re going to be, one day you’re going to blink and you’re going to turn around and be my age, and you’re going to find out, oh my gosh, I don’t have this abundance of time. It’s not only because you’re getting older, but it’s also because the older you get, it feels like there’s more commitments, whether it’s family and other, your business responsibilities or whatever, you just don’t have as much control as you’d hoped. But that’s okay, if you’ve built up enough income and assets, you can start buying back your time, but only if you’ve made really good decisions when you’re in your 20s and you turned your time that was in excess at that point into assets that you own.
Bo: Yeah. But that’s why we have to figure out how much capacity you have, so we can get aggressive, because the only way this all works, we got to get the debt paid off and we got to start owning stuff. And now you’ve done a good job, the fact that you have $70,000 of net worth above and beyond even this debt means you understood that, but you also had a tailwind with the living at home. Now that we’re going to be out on our own, it gets a little more raw and you’ve got to be even more disciplined and purposeful with everything you do.
Brian: Is the lease already signed, like the apartment, is this happening?
Joe: This is happening, we’re making it happen.
Bo: How did you decide now was the right time for that?
Joe: Partially just because I felt like I was at a point in looking at the numbers for myself, 28 years old.
Bo: First of all, I get it, but I didn’t ask you, Brian, why are you moving out.
Joe: But I also felt like, I don’t know, I had done the dirty work, I had made a lot of sacrifices and decisions for the past five, six years, that if I don’t push myself a little bit more and put myself in a situation where, hey, I just have to make things happen, I have to go find a better job that makes a little bit more income, or I have to continue with the side hustle a little bit more, in order to create that margin and that aggression that got me to do these things in the first place, right? Because the debt’s dwindling down, it’s almost like the tiger that’s chasing you is dwindling. Can we get a new tiger to chase you?
Bo: A new tiger, yeah. All right, so okay, we’ve talked a lot about where you are today and what you want to see change in the near future. What about ultimately where you’re heading, when you think about, and I don’t necessarily, you’re 28, so I don’t want to go all the way to 65, but when you think about life at 40 for you, how does life at 40 look differently than it does today, and what do you want to say at 40 that’s true of your life from a financial standpoint?
Joe: Yeah, from a financial standpoint I’d say obviously we want to get the debt knocked out, that’s 100% the number one thing that’s been with me for so long, that I’m like, we just got to get rid of this. Now whether or not that’s the best thing to do in terms of cumulative money that I could make over time, that would be where, why I’m on the show and what I want information from you guys for. And then besides that, I know you said you didn’t want to push it all the way out to retirement, but figuring out my numbers for some Coast FIRE, or a type of retirement plan in that sense.
Bo: When you think about Coast FIRE, since you brought that up, when is the coast part and when is the full retire part? You got to give us those two numbers.
Joe: Yeah, I think it would be landing close to that 45, 50 year mark. It doesn’t have to be, I enjoy working, I really did find a passion and something that I like to do, so that’s not a problem for me. It’s more of just like, what can we do to kind of make it so that I can live my best life as early as possible with the decisions that I’ve made so far.
Bo: So get to age 45, age 50, be able to coast then out until a full retirement age of 65?
Joe: That would be awesome.
Bo: Talk to us about inside the graphic design world, what does income opportunity look like? Are you, is the income you’re making right now probably going to be the same thing you’re going to make for the next 10 or 15 years, or does it scale up, is there a range? How does that work, how does your side hustle play into that?
Joe: Yeah, so from my actual W2 I’m probably in the $92,000 a year range, or whatever that math, 97 or wherever I’m at now. Senior graphic designers in my area can make $120,000 to $140,000, so there’s definitely a little bit of room to grow there. And then you get up to art director and other titles that are much more substantial.
Bo: So is your desire to move into one of those roles, do you want to be an art director and that sort of thing?
Joe: The thing that I would say I’m debating at the moment is, hey, do you really go off and do something on your own? I know that you had this experience going off on your own and really taking, 28 when he did it, taking that gamble.
Brian: I was 28. Well, you might have some answers, you got, but full disclosure now, look, I had a big life element and I lost my father, I wasn’t really thinking rationally when I did it, because I went from making right at six figures to, I think my first year I made $17,000 to $18,000. So not exactly a blowout success in the first year, right out of the gates.
Joe: But it is a decision that you had to make and that you made, and it actually worked out for you.So even if we do it in a somewhat better way than you did, which could or could not be possible, I wonder if that’s feasible for something like me, because obviously there’s th-
Brian: If you want to do it yourself, if you want to be a business owner, is this a serious thing or just an aspirational thing?
Joe: I would say that it’s more aspirational at the moment, and that’s why I gave you the information on the actual job.
Brian: If you’re serious, you’ve heard us talk about putting on your 3D glasses, where you have to actually lay out a business plan for what the next three to five years looks like, and then run it in three different scenarios. There’s the dream of, man, I can’t believe all these people, these prospects just keep showing up all over the place. There’s the down-to-earth, is hey, this is probably going to be hard to go get clients, because that’s what a lot of people, a lot of people have passion. I can remember when I started my first company, I just thought everybody, because I was always a likable guy, I think I was perceived as a pretty smart guy growing up, so I thought as soon as I started my first company, all my childhood friends, parents, and everybody would want to come and hire Brian, either do let him do our taxes or manage our assets or so forth, this was what the daydream was. And then when I went out on my own, the phone doesn’t ring. And it was, I was shocked, I was like, obviously I have a false sense of myself, because nobody, I should take that back, I had a neighbor who called me, one of my parents’ neighbors, Mr. Ronnie Stewart, he actually reached out, and then one of the mothers of one of my childhood friends, old Franny Fran. Those were the only two that showed up, I mean my in-laws didn’t even show up at first. Well, they’re supposed to love me no matter what. Now, am I, my mother-in-law is going to see this and she’s going to be upset about it. But that’s why I tell you, you have to put on your 3D glasses, because there’s the dream of what you hope will happen, there’s the down-to-earth plan, and then truthfully mine went more like the doo-doo plan, and I think you have to kind of account for that. Now the good news for me was I had saved up three years of what I thought I needed pretty much in cash, so that I had a little room for the doo-doo to get cleaned up, and that’s what it took for me to figure out how to do this. Well, so if you are serious about doing the entrepreneurship side, you’ve got to create that cash flow plan and then figure out how you’re going to get business, because that’s the hard part. You can be the most talented person in the world, but if people aren’t going to be able to find you, or you’re not going to be able to go sell that passion or that talent to somebody, it doesn’t matter how skilled you are. And that’s the hard part that I found, is that you can be smart, you can be talented, but if nobody knows you’re out there with the sign on the door, it’s a dream.
Joe: I agree completely.
Bo: When you hear that and you think about entrepreneurship, this is something you said this may be a little more aspirational, this isn’t something you’re trying to do in the next year, next two years, next three years, this is like maybe down the road one day I might want to do my own thing?
Joe: Yes.
Bo: But more if the stars align, not that’s something I’m going to hard-charge and drive towards, am I hearing you correct on that? We got some plans here. Our plan is we got to figure out how do we get the debt knocked out, what’s the strategy for that, how do we get to a good place in the near term, and then ultimately how do we get to a good place maybe by the time we’re in our mid-40s in order to be able to do some sort of Coast FIRE and figure out what that looks like.
When Is Lifestyle Inflation Okay? (34:57)
Bo: What other questions can we answer for you? What other things can we speak to that might be valuable?
Joe: Being a saver and being someone who’s been diligent for a really long time, my question would be, how do you know when your lifestyle is inflating versus you’re actually making progress and you can actually start to afford some of the things, the life luxuries, that you can kind of bear the fruit of what your work is?
Bo: At your age, I think it’s a function of savings rate. If you can get to the point where you’re saving 25% of your gross income, you don’t have to worry about lifestyle inflating beyond that, right? Like if you have money left over after saving where you need to be saving, putting money in your retirement accounts, putting money in your Roth, doing your HSA, building your taxable account, having your emergency fund where it needs to be, and you’re doing that on a systematic and automatic basis, getting that debt knocked out, if you want to move into the nicer apartment or buy the automobile or go on the trips, you get to do that and do it guilt-free. You don’t have to worry, oh, is it okay if I’m doing this. If I’m paying all the stuff I need to be paying first, I get to spend freely and guilt-freely and enjoy what I’m doing, I don’t have to second-guess and have remorse over the decisions I’m making.
Brian: Yeah, we’ve got, by the time this episode airs, we actually, so you’re going to get some behind the scenes here, because the day we’re recording it, our Know Your Number course that we sell for $100, we’re actually converting that into a free calculator that’s going to be on our website. So that way anybody who wants to know if they’re ahead of the curve, behind the curve, right where they’re supposed to be, I think it really pays respect to what Bo was talking about, if you use that tool and you can see that you’re ahead of the curve with having a good savings rate and being disciplined, it should free you to start living your better life, because the problem is a lot of people, they base it off of their cash flow, it’s the same thing when you show up at a car dealership, they don’t try to help you figure out how much car you can afford, they say, how much is your monthly car payment. And that’s the opposite way of how you’re supposed to live your life. I think you’re supposed to figure out what your income is, what your goals are, figure out how you build the lifestyle to where it matches that income and the future goals, so then you can bolt together the plan that actually fits within all those things. I mean, I already feel pretty good, because I think I’ve got your numbers figured out a little bit better, and we’ll go into it when we get into the full planning phase of it. I bet you’re going to find that you have just on a monthly cash flow wise about $9,600 a year. So if you think about that $9,600 a year, that’s going to work out to be about $800 a month. We’re going to be able to create some automatic plan whether it’s debt, whether it’s savings or investments, and this might tweak up or down a little bit depending upon what the planning team comes up with. And then I think probably of that side hustle, even accounting for taxes and so forth, hopefully you can come up with $9,000, if you were pulling $10,000 to $11,000 we can come up with another $800 a month or $750 a month. And if you do that, and I think if you really looked at where your income really is, I think it’s probably a little overstated at $107,000, but where if we’re closer to $100,000, if you’re saving 18% of that, that’s pretty close to, and that’s a really good thing for somebody who’s under 30 years of age, because a lot of times when Bo says 25%, that’s somewhat aspirational for people in their 20s, because you just haven’t had enough time for your natural talent to reach the level of experience where you have mastery, and then you reach those peak earning years. Most people’s peak earning years is in their 40s and 50s. But you’re well on that path, it’s just a matter of being patient. That’s the only thing that I see from looking at this, is yes, your student loans are there, but I think if you’re patient and we create a plan, you have the elements to be very successful here.
Joe: That’s awesome, thank you guys so much.
Bo: Well, I think I know what we need to put together, I’ve got some, I think we’ve got some good thoughts, I think we can do some good planning here.
Joe: Thank you guys so much.
Brian: Awesome, thanks Joe, appreciate it.
Bo: Joe, thanks for coming on, this has been great.
Joe: Thank you.
Post-Session Analysis: An Inspiration to Young People (38:55)
Bo: All right, Brian, I’m gonna say it, Joe, I think Joe should be an inspiration to young people out there.
Brian: I mean, how do you start with in the hole $120,000, and then you come out, and by the way, he’s still in his 20s, come out the other side with a net worth positive by $70,000.
Bo: It’s wild, it shows that he was willing to make some difficult decisions, move towards his goals. I think he has a bright future, but there’s some stuff that needs to be triaged today.
The Plan to Eliminate His Student Loans (39:21)
Bo: Obviously the big thing that came up, we looked at his net worth statement, he has debt on his balance sheet that we need to get off. Right now he has these five different student loans, and some of them, I’m going to say, qualify as high interest, 6.75, over 6% certainly high interest in the 20s. I’m going to argue even that one at 5.5% because it’s his biggest loan, since he’s about to be 30 the next couple years, I think those are for sure high interest.
Brian: How much of, how conflicted were you in the fact that a big part of Joe’s success has been he lived at home, so that allowed him to be really go hog wild with paying down the debt. Now I get it, he’s at that threshold, he goes, no more, I’m moving out, he had a roommate and they’re going to go live their best life, but I was sitting there going, wouldn’t it be cool if we just had a little bit more, live at home, so we could completely extinguish those student loans, because now it does require us to make bigger, harder decisions.
Bo: That’s right, and I definitely think that maybe if he could have just done it for a little bit longer, he would be able to get further along, but again, I think he’s in a great spot, and at 28, Joe does have a big shovel. We discovered that his take-home pay is somewhere right around $5,600 a month, and that doesn’t even include the $10,000 a year in side hustle income he has coming in. And so when we think about his living expenses and where he’s going to be, he’s going to be spending about $4,800 a month, so he has about $800 of margin available, that’s what’s there.
Brian: And don’t forget that $4,800 includes, I think, a little under $1,600 a month, it’s like $1,550, that’s going towards paying down debt payments, so he has a pretty small footprint.
Bo: Yeah, when you add those two up, he’s got about $2,350 he can throw towards debt on a monthly basis. So when we model it out, it’s pretty incredible what he’s going to be able to do if he just takes that $2,350 and begins applying it to the debt. And we just said, let’s go with the avalanche method, let’s pick the highest interest rate and knock that down, and let’s go to the next highest and next highest and next highest. He’s going to have the parent plus loan paid off in 11 months. The parent plus number, uh, first loan paid off in 20 months. Private student loan paid off in 32. The direct subsidized paid off in 35. And the direct unsubsidized paid in 37. Now I know some people are saying, guys, you said only three of them were high interest, why do you have him paying off all five? Well, I just think that behaviorally he’s done such a good job of building assets, he’s in a great spot, even when you look at his net worth on the asset column, that I think he’s afforded himself the ability to give himself this behavioral win of just getting all of this debt knocked off of his balance sheet in the next couple years.
Brian: Well, personal finance is very personal, and the good news for Joe is he did build up some wealth and some investable assets even as he was paying down these student loans while he was living at home. Look, there’s a part of me, I felt a little conflicted, and we ran it both ways where we were like, hey, there is a path here where he is knocking out the student loans aggressively, but he’s also funding his Roth IRAs, because I love the tax-free growth, but man, it did look compelling when you looked at, hey, if we just went with debt crazy, just call it a debt crusader, if you will, to pay off the debt, and then still when you’re in your early 30s be able to then go ham on the saving and investing, it’s pretty exciting stuff.
Bo: Yeah, we said that, okay, originally if he just sticks to our plan of using that $2,300 of margin to pay off the debt, he’s going to have it paid off in around 37 months. But if he took that side hustle income, and instead of doing the Roth IRA, instead of doing that, he just applied all of that, and he had about $3,000 a month going towards his loans, he could have every single one of his loans paid off in 27 months.
Brian: So we’re only talking about, we’re foregoing essentially a year, maybe an addition between the two that we’re talking about, one Roth contribution difference between these two.
Bo: That’s exactly right. So he’s going to have to look at this and figure out, what do I want to do? Do I want to live more in the present by using my side income for lifestyle? Do I want to take my side income money and max out my Roths, I’m still building assets? Or do I want to buckle down and eliminate the debt? He’s going to have to choose based on where he is which one of those paths he’s going to go down.
Could He Coast FIRE With Millions? (43:41)
Bo: So I want to know more about the Coast FIRE thing, because it sounds, being so young, conquering so much debt, how does this start stacking up, and how much momentum does it build, and how quickly?
Brian: Well, here’s what we said. He’s already done the hard work at his age of building up $100,000 in assets. So he said, okay, what if we jump forward, have all the debt, all the student loans knocked out, and let’s get him to a 25% savings rate starting at age 31?
Bo: Which will actually be less than what he’s throwing at the debt. That’s exactly right, he’s actually going to get a free lifestyle upgrade once those are gone. So if he just hits 25%, he’ll be saving about $2,200 a month. Starting at $100,000 at 28, saving $2,200 a month, by the time he gets to age 50, he will have amassed a portfolio, assuming a 9% rate of return, of about $2 million. That’s pretty wild. And so then we said, okay, well, if the idea is to coast, if he stops saving at 50 and he just lets that $2 million grow from age 50 out to age 65 without saving another dime, $2 million turns into almost $8 million.
Brian: Even in the content meeting, we had to pull out the financial calculators and make sure it really does show the power of compounding growth, because to see that $2 million with just a little bit of momentum and consistent growth can grow to that level was just, it was kind of shocking, they were like, let’s check those numbers one more time to make sure we’re telling everybody the right thing.
Bo: Look, Joe has a big shovel, but he’s not this guy that’s making hundreds and hundreds of thousands of dollars, and he’s not doing anything unbelievably remarkable. And I think that if he’ll recognize, man, I’m in this situation, if I can knock out this debt, not carry it through the next decade with me, if I can focus on keeping my footprint small and building for the future, because he’s so young, because he’s already done a lot of the hard work, he’s going to have options later down the road to live the life that he wants to live on his terms, the way that he wants to live it, if he can prioritize knocking some of this stuff out.
Brian: He should definitely feel encouraged and realize that he’s looking in a really good place from really hard decisions in the beginning, but now it’s just kind of building upon itself, the essential definition of compounding growth.
Bo: That’s right, he’s a financial mutant and going to continue to be a financial mutant.
Brian: Joe, we loved having you on. Bo, if more people like Joe wanted to come on and show how they can conquer their finances, where do they need to apply?
Closing (45:53)
Bo: Yeah, if you want to be a guest on Making a Millionaire, you can go to moneyguy.com/apply. Or if you want to check out any of our free tools and calculators, go to moneyguy.com/resources.
Brian: Joe, thanks again. And for the rest of you, remember, small decisions can have huge results and help you live your great big beautiful tomorrow. I’m your host, Brian, joined by Mr. Bo. Money Guy Team, out.
Free Resources

Free Resources
Financial Order of Operations®: Maximize Your Army of Dollar Bills!
Here are the 9 steps you’ve been waiting for Building wealth is simple when you know what to do and the order in which to...
Free Resources
Wealth Multiplier By Age
If you want to set yourself up for future success, find out how much you need to save every month to become a millionaire.
Free Resources
Car Buying Checklist
Here’s how you can buy a dependable car that won’t break the bank. Our free checklist walks you through the 20/3/8 rule and strategies to...
Articles

Articles
How To Win With Money in Your 20s (and Set Yourself Up for Life)
The first decade of adulthood is one of the most important periods of your life. The course your life takes when you are younger can...
Articles
How To Prepare for Student Loan Payments Increasing
About 43 million Americans have federal student loans, and many borrowers face financial difficulties due to their loans. Student loan debt has significantly impacted the...

Articles
Top College Degrees in 2026
The median college graduate makes 68% more than the median high school graduate, but that doesn’t mean it’s a good idea for everyone to go...
Financial FAQs
Courses & Tools

How about more sense and more money?
Check for blindspots and shift into the financial fast-lane. Join a community of like minded Financial Mutants as we accelerate our wealth building process and have fun while doing it.
Free Resources
Financial Order of Operations®: Maximize Your Army of Dollar Bills!
Here are the 9 steps you’ve been waiting for Building wealth is simple when you know what to do and the order in which to...
Free Resources
Wealth Multiplier By Age
If you want to set yourself up for future success, find out how much you need to save every month to become a millionaire.
Free Resources
Car Buying Checklist
Here’s how you can buy a dependable car that won’t break the bank. Our free checklist walks you through the 20/3/8 rule and strategies to...
Recent Episodes

It's like finding some change in the couch cushions.
Watch or listen every week to learn and apply financial strategies to grow your wealth and live your best life.

Episodes
How to Retire at $1M, $2M, $3M, and $5M
Wondering if your retirement savings are enough? In this insightful episode, we walk through four portfolio benchmarks - from $1M to $5M - and the...
Episodes
How To Actually Make Money Sports Betting
Sports betting is exploding, but 96% of bettors lose money - so are you in that 4%? We break down the real cost of sports...
Episodes
Financial Advisors Debunk TikTok Money Advice
Is TikTok's financial advice doing more harm than good? From popular rules to getting lucky in the stock market, we react to viral money clips...