-
▼
-
▼
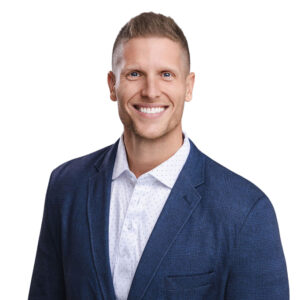
Christy Carlson Romano built a career most kids only dream about, but what happened behind the scenes with her money is a story most people never hear. In this special episode, we sit down with the actress, content creator, and author best known for Even Stevens, Kim Possible, and Cadet Kelly to talk about what it really looks like to be a first-generation Disney star, make a million dollars in a single year at 21, and still end up broke.
From the $40,000 she gave to two different psychics to rebuilding her brand from scratch through social media, Christy’s story is both a cautionary tale and a reminder that high income and true financial independence are two very different things. You will hear how an income fantasy kept her from facing reality, how the adults in her corner gave her questionable financial guidance, and what finally pushed her to turn things around after more than a decade of financial chaos.
We also discuss how to recover from financial mistakes, build wealth after starting over, teach kids about money, use a Roth IRA, avoid lifestyle creep, and create a healthier relationship with money. Whether you grew up watching Kim Possible or you just want a genuinely honest conversation about money mistakes and second chances, this episode is one you will not want to miss!
Order Christy Carlson’s Romano’s new book Once Upon a Train Wreck today!
Enjoy the Show?
Where You Can Watch and Listen:
Subscribe on these platforms or wherever you listen to podcasts! Turn on notifications to keep up with our new content, including:
- Episodes of The Money Guy Show every Friday
- Episodes of Making a Millionaire every other Monday
- Mini-shows every Wednesday
- Ask Money Guy Livestreams every Tuesday
- Tons of other fun content!
Christy Carlson Romano’s Wild Money Story (0:00)
Brian: If you’re a big Disney fan like I am, man, do we have a treat for you today. Today we have Christy Carlson Romano.
Bo: Brian, I am so excited because it’s so interesting. You’ve lived a life that a lot of us have seen but very few of us have experienced and so I’m just excited to hear your story, what you learned, and specifically how it shaped and formed how you think about personal finance.
Christy: Absolutely.
Brian: By the way, you seem so normal from our conversation so far. I’m waiting to see where all the chaos is. So, you do a good job of covering your crazy right now.
Christy: Well, they do say once upon a train wreck, so hopefully there’s been some redemption.
Bo: Yes. Absolutely. For folks who aren’t familiar with who you are, give a quick rundown like you had to give the elevator pitch. Who are you?
Christy: Gosh, that’s a really deep question. Who am I? My name is Christy Carlson Romano. I’m an actress now. I’m an author that has a book coming out October 6th. And I’ve been acting all my life since I was about six and a half. I started working with Disney when I was around 14 years old and had a lot of successful TV shows and animated shows. I was Emmy nominated. I starred on Broadway when I was 19. I was the youngest Belle on Broadway for about an eight-month run, and then just kind of transitioned from child star to regular Hollywood person and then kind of dealt with a lot of the financial upheaval that a lot of child actors deal with.
Brian: You know, we’re a financial show, but there is still so much curiosity because we’ve seen all the headlines of people who’ve fallen into the trap as child stars. And that’s one of the things I had a general curiosity about when I found out we had you booked. I’m assuming you all made a lot of money. I mean, these were popular shows, so you had good money coming in. We want to hear kind of how it all went down and then also give you the hero’s journey of how did you kind of realize, I’ve got to change some things and we’ve got to fix this.
The Financial Reality of Being a Disney Star (2:47)
Christy: Yeah, absolutely. I think the assumption number one is that I made a lot of money. So Disney when I was on it, I’m the first generation of Disney stars. Now we see Selena Gomez and we know her net worth, whatever. And I was the first generation, which meant that it was experimental. They didn’t have a lot of programming on the channel at the time. It was mostly just concerts that were live from Magic Kingdom with the Backstreet Boys, Christina Aguilera, and it was sort of just an untapped resource that the Walt Disney Company did not know how to utilize yet. And so around 1999, they shot the pilot for my show called Even Stevens. And they were kind of like gearing up to launch a new era, which they most definitely did, as we can see. It was successful, too.
Christy: Yeah. So, I’m sort of like the first class of X-Men. And it was really a wonderful thing to be a part of. I never would have thought that here we would be today with still such reverence for the productions that I was a part of. And so, I did not make a lot of money. Part of being in the first class, they didn’t know how to pay appropriately. They didn’t need to because there was nothing to compare it to. Actually, the only thing to compare it to was whatever the kids were making on Nickelodeon. And Nickelodeon was infamous and still is pretty infamous for paying scale, and scale is like $800, and they don’t even do residuals for their children actors. So they actually were really poorly paid over there on Nickelodeon and we were getting modest amounts of money. So like for my first season, I was getting paid, and I found out this was half of what my co-star Shia LaBeouf was making, and that was $6,000 an episode. And when we think about how much is taken out of that, it’s pretty staggering. You get 10% to your agent, 15% to your manager, 5% to a business manager, 30 to 35% taxes. You’re making less than half of whatever it is. And then you’re left to settle and live a life in Los Angeles just to be able to, because I was displaced. I went from my home in Connecticut with my three other siblings to live in Los Angeles with my mom. And so, you know, you have to live there, you have to be there, and then it gets more complicated as you get more successful because you need a stylist or you need a publicist. We were really scrappy. My mom was actually audited. This was before I got a business manager. My mom had been audited about two years into the first series that I did for Disney. And I think that’s why she was so scared that she was like, “We need a business manager.”
Bo: She got audited for managing your finances and acting as your business manager?
Christy: Correct. Yeah. And I come from a very middle-class Italian-American family from the east coast and my parents had been in bankruptcy in the past and they really didn’t have financial literacy in a traditional sense. I think that my father was a consultant and so he would go from job to job and money was pretty inconsistent. But when we had it, we had it and what my parents chose to do was to educate my siblings and they all had private schools and the best of the best and they were really just a working-class family. So enter me. I had already been sort of acting in New York City because that’s what you did if you were from the east coast and within a train’s distance to the city. That’s how you got your start. So I had been doing a lot of theater work, and theater work doesn’t pay anything, but it was stepping stones to when I eventually ended up in Los Angeles and booked for Disney.
Christy: So when I was working, what I found really interesting in discovering when I was writing my book and I had to interview my mom a bunch, was that everything that I made, in order to justify me being able to take time away from my siblings, I actually paid for my own way. So I paid for my own private school education in New York City and I paid for the trains and I paid for any outfits that I bought for auditions. So from the jump I was already a little bit in a deficit because I wasn’t really making anything or saving anything until the Coogan account sort of activated for me.
How Child Actor Money Actually Works (7:26)
Bo: For those who don’t know, can you explain what a Coogan was?
Christy: Jackie Coogan was a child actor whose parents took everything from him and then he became destitute, so in his name they created these accounts for underage actors to have a portion of all of their paychecks put away.
Brian: But it’s not in every state either.
Christy: It is not in every state. I would hope that it would be, but it’s not.
Brian: I don’t think it is either.
Christy: I wouldn’t be surprised, unfortunately. So, you know, I feel like I view it as a deficit because I wasn’t earning anything that I wasn’t using to go back into my career. It was coming in, but then I was paying for private school and all of this.
Brian: So there’s nothing being left for the future as a teenager. This was before Disney. The big break came around 14 years. And how did that happen?
Christy: So I was let go early from a Broadway show called Parade. Live went bankrupt, which was a big theater production company, and we were at Lincoln Center. And they said, “We’re going to give you your severance pay and you’ve got about a month worth of money.” And when we chose to take that money and go out to Los Angeles for what they called pilot season, now because of streaming pilot season doesn’t exist anymore, but pilot season used to be from about February to May, and it was when all of the new shows were being cast. So it was like a gold rush for casting opportunities. And so my mom said, “We’re taking this money.” We allocated the money and we had about a month in Los Angeles. And then I had about 10 auditions and one of the last auditions I had was for Even Stevens for Disney.
When Your Childhood Becomes a Job (9:22)
Christy: So it was really a lottery and it was a lottery mentality that I was existing in.
Brian: And you’re like 13 years old when this is all going on.
Christy: Yeah, for sure. Yeah.
Brian: That’d be a lot of pressure just, you know, family future and opportunities. You’ve got to make something happen.
Christy: For sure. I think it kind of takes your childhood and it monetizes it, right? When people ask me if I would put my kids in the business, that’s a no for various reasons. But also too, I think that when you put your kids in the arts, it’s one thing. You can put your kids in the arts and enjoy the arts and they can learn to love it and they need it. We need the arts. But at the same time, once you put the money part of it into it, the earning and all of that, I think it kind of changes your childhood like forever. It turns into a job. The only reason I learned how to ride a bike was because I had a callback for a commercial and it was a skill you had to have. It was a special skill on my resume. And rollerblading and other things like that. And so everything that you sort of learn to do is because you’re like a multi-trick pony.
Bo: So obviously you were acting in New York and I imagine it’s a big break. You go down to LA, you have this audition, you land this huge role. That sounds super exciting. A lot of people are going to be in there like I made it. But your book is Once Upon a Train Wreck. It sounds like it was not like, oh, everything was great and wonderful. There has to be a left turn here somewhere. Walk us through the train wreck part. I’ve got to believe that’s a high of all highs when you land a role.
Christy: Yeah, absolutely. Look, I think I have a lot of gratitude for the opportunities that came my way that I had worked for for many years, but then there’s no telling if you could actually book the job. And then if you book the job, does the pilot actually go to series? And then if it goes to series, does it get picked up for what we had, which was 65 episodes? And that was so that we could get into syndication. And Disney kind of had this rule back then because they were trying to diversify their programming to only have series go 65 episodes. So we were kind of told like, look, this is what you’re going to get and after that the show would be over. Throughout the course of my career with Disney I got other opportunities. So I was the voice, and still am, of Kim Possible, and that created a new income lane. And it was something that we learned to negotiate even more aggressively, although it was still paid pretty low. We re-upped in the second season because we knew how popular it would be. We started sniffing that like there was McDonald’s toys and all these things. So we started to get a little bit more aggressive. But my mom was a team player. She was not one of those that would say, “Well, Christy’s just not going to report to set unless you do this.” Which had happened with people like Hillary Duff. Even my co-star, there were rumors that that would be the way to play hardball, just tell them you’re not going to show up. So, we were very different and we said yes to everything.
Christy: And so, I got Kim Possible. Then there was another movie that was very popular for the world of Disney because it starred me and Hillary Duff, who were the two major stars besides Shia on the network. And so that like blew through ratings. It was this big thing called Cadet Kelly, set in a military school. And so I sort of became this fixture of this first generation of Disney stars. And that wasn’t quite monetizable yet. There was no Instagram. There was no, oh wow, I can take this and make myself have my own platform and sort of control my brand, control my name, whatnot. So, you kind of just waited for the phone to ring from Disney to see what they would ask you to do next.
Bo: When you said you signed off for 65 episodes, did you commit that all 65 of those paid at $6,000 an episode?
Christy: No.
Bo: So, you’re able to increase and change that throughout the course of recording, right?
Christy: Yeah, absolutely. And then you had residuals that were paid to you after the fact, but I did look up the residual structure, which is not explained to you by SAG or anybody else when you’re exiting the series world. But basically, you go from getting a very sizable residual to in like the reruns that we had going from like 17% to about 1.5% in like a 10-year period. Now, that’s really good because you had some leeway, but if you didn’t know any better and you were somebody who was financially illiterate, you would be like, “Well, I have this money and this money is going to always keep coming, and like this show is just going to keep paying me.” And so, you start to live in this fantasy world of like false security. So, I think that has a lot to do with why you see a lot of child actors sort of spinning out of control, having debts, and just starting to lean on other facets of security like drugs and alcohol.
Making Seven Figures Without a Financial Plan (14:34)
Brian: You did have some seven-figure years where you actually crossed into seven figures, one in particular when it came to Disney. Where did the money go?
Christy: Well, what I will say is that my business manager was not the best. I was about 18 at the time and he tried to sit me down and explain things to me in a way that felt like a different language and I was just glazed over. I could not understand a thing he was saying but I sat there and I acted like I knew what he was talking about.
Brian: So no Roth IRAs were happening.
Christy: There was a Roth IRA. There was, like I said, there was the Coogan, which was set up for me to go to college, which I did go to. I went to Barnard College at Columbia University, which has a hefty price tag. So, everything that was in my Coogan was like the exact amount. There were several hundred thousands of dollars so that I could not take loans out to go to college. So, that was what I was set up for. And my family, to their credit, was always big on education. But in terms of any future assets or anything like that, nothing was being saved for that. There was no savings outside of the Coogan account that was considered that.
Bo: So did anyone talk to you as you were having the success from a very young age, now you’re like 18 years old, like parents, business managers, no one’s talking to you about saving and deferring and building for the future?
Christy: There was no baseline education around that from anyone. No, there was much more like how do we show a loss, and there was the S corporation tax planning. It was all that. There was no future assets. And that’s one of my greatest shames, my greatest regrets, and really one of my biggest things that I’ve had to get over with my mom, who I still help financially now, but I just wish that she would have had the foresight to say, “Hey, let’s get you a house. Let’s get you a rental property. Let’s do something.” It wasn’t something that I guess we didn’t have a community of other child actors to talk to about this. And you know how we don’t really talk about money, which is one of the reasons I’m happy to talk about it now because it’s like, why is it so mystified? Everybody makes it. Everybody loses it. Everyone has their own relationship to it.
Brian: Did you buy a car when you were 16 or 17?
Christy: I will say that that was one of the bigger purchases. The first car that I got was when I was 16. It was a red Cabriolet Volkswagen convertible. And we paid for it outright, I remember. And it was something that I thought at the time we could afford. So, how long did that car last? The act two was after a while, I basically said goodbye to my parents after a certain amount of time. So I had the car and then I ended up getting a G500 and so that was when things started to shift, but that wasn’t until I was about 21.
Brian: I often think it’s a curse to have money too young. I mean, if we all go back and take ourselves back to high school, I can’t imagine what it’s like to be out in LA. I remember the first time I ever went to LA I had my first $25 cheeseburger, and this is before everybody else had $25 cheeseburgers. And also Range Rovers and there were Honda Accords out there. It was very unusual if you come from the Southeast where everybody drives Hondas and Toyotas and then you go out to LA and it’s a car culture. I mean, everybody is driving the cars. So, growing up around that and then being young with money, disposable money coming in, I can see how you just fall right into that trap.
Christy: Well, eventually too, what my CPA said to do was to buy a second car and that the second car could be a collectible car. And then I got a 1972 Corvette. And I never drove it. I only let my boyfriends drive it because I was terrified of it. But it was like, you know, I don’t know what I was doing. These were things that I had the wrong guy in my corner, unfortunately.
Brian: When does, because look, we all have heard the stories about Nickelodeon, you know, creepy stuff and other things. I imagine Disney’s a more curated experience. When do drugs and the creepiness, did that stuff show up on Disney sets too, or was that not at all?
Christy: Not at all.
Brian: Okay, that’s great. But obviously chemicals and drugs came in somewhere. How’d that all happen?
Christy: Well, let’s see. I think that my relationship to drinking, I mean, I started clubbing really early. Growing up in New York City and then having older siblings, I got into clubs really early, like 16. My sister got me into a few clubs when I was 16 and then I caught the bug of it, but I didn’t really start going back to clubbing until I was in my freshman year of college. And so then I was in New York City and I was like 18 and I was like, “Let’s go out.” And I had a fake ID. I drank very casually most nights like a lot of people in college do, but I think my relationship to it became progressively more of a sort of binge drinking over the years. I don’t know. I think that I’m so proud of being 10 years sober from alcohol now because just without it in my life, I’m able to have so much clarity and I can’t even imagine what it’s like even to be like a wine mom and to have a hangover and have to get up and take the kids to school. So parenting is hard enough already.
Bo: It’s hard enough without giving yourself some more hurdles to jump.
Christy: And I speak for a lot of millennials in that like mocktail culture and sobriety, like curious people there. There are a lot of people out there now that I think grew up in this millennial culture of just like shots, shots, shots, like go clubbing.
Bo: There are songs that sound like that.
Christy: So many songs, so many songs. The club culture was huge. And what I will say about club culture as well is that it was the only way to be seen. We didn’t have Instagram. So you had to go out. You had to go out to be seen. So once I was of that age after Disney, which was around 18, and I was clubbing, I got back to LA after my run as Belle and I was around 21. And the whole thing was, well, you’ve got to get on a Maxim cover. Like if you’re going to be seen as a woman, you’ve got to have a Maxim cover. And so part of me was really itching to get on Maxim to be taken seriously and so forth. Isn’t that so crazy?
Brian: And you know, being a girl dad myself, the content stream, I don’t think we’ve improved in that aspect.
Taking Control of Her Money at 21 (21:41)
Bo: From young child to 18, not a ton of like financial guidance. And then even from like 18 into young adulthood, obviously something shifted. There was a shift somewhere where you started like, “Oh, I’ve got to figure this out. I’ve got to start making better decisions.” How did you get there and when did that take place?
Christy: Well, so I had a relationship with somebody who was a trust fund baby. And he was like, “Well, how much money do you have in your bank?” And I said, “I have no idea.” And this was when I was 21. And he’s like, “I think that your family is taking from you.” And I was like, “Well, I’ve given them money for their mortgage and I pay my mom a salary and I also rent her apartment as a write-off that was counting as an office.” And so there were all these justifications for some of this poor decision-making that I thought was just beyond me. I was like, well, the adults in my life are taking care of this and I can just focus on the art and I can trust them. It sounds like it makes sense. I just didn’t want to know, really. I pushed it away and it felt wrong. It did feel like something was wrong and it caused a great amount of anxiety in me because I started to see my relationship with my mom as: you could either be my mom, my friend, or my manager, like pick one or pick two. And so it became like my relationship to her was not very friendly. And it sort of devolved through this relationship where he was pressuring me to really push back on my family. Which in some way I’m grateful for, but in other ways it was hard because I ended up going no contact with my entire family and then getting all my money and all my things and firing her.
Brian: How old were you at this point?
Christy: 21. Wow. That’s such a hard thing for a 21-year-old to navigate. I think I was a little emotionally stunted. I don’t think that I was at the same sort of emotional maturity level as kids that went through high school with normal experiences. I think that a lot of child actors are really mature in some ways and then really immature in other ways. So I acquired all my money and I still had money in the Coogan account.
Bo: Was this a substantial sum?
Christy: Yeah, there was a substantial sum. I mean, because I had a book deal and a record deal. And that was that year that I made the million.
How a Million-Dollar Year Became a Financial Train Wreck (24:20)
Christy: Right around the same time I nixed my mom out of my career. And from there was when the train wreck started to really happen. Because I started going to Chanel and I started going to Ralph Lauren.
Bo: And I you were like, “I make a million bucks.”
Brian: And did you just always have this feeling it was going to continue forever?
Christy: Strangely, what they told me, my business manager and my mom, they said, “You have to assume that you’re going to keep making money.” And gosh, I don’t know why they said that.
Brian: Well, I will say because we see it all over social media: go buy the most expensive car, put yourself under pressure because if you’re under pressure for the life you want to live, you will go make it happen. You’ll manifest the life you want to live. And that’s probably what they were getting at. But that is a recipe for disaster. Especially because I worked with a lot of professional athletes. I hate that mentality because if you statistically look at the longevity of athletes, entertainers, it is a very short window. Now it is very rich and has a premium to it. So you have to understand, you’re basically packing 25 to 30 years of earnings into five years. So you have to act accordingly. But it sounds like you got the exact opposite advice: go spend it because you can always make more, which is not the reality of the situation.
The Turning Point: From Rock Bottom to Redemption (25:49)
Bo: So give us the redemption side of this though, because like you said you’re going to this clubbing, you’re spending the money so you can be seen, but at some point you’re like, enough. This is not who I want to be or where I want to be. Where is that self-realization? Is it at the dead bottom of it or did you pull yourself out at the right time?
Christy: There was a long time before I ended up turning around, and that ends up happening when I get pregnant with my first baby.
Brian: And what age was that?
Christy: That was like 10 years ago.
Brian: Oh wow. So 32. So from 21 to 32 was just rough.
Christy: Well, not with addiction and whatnot, but I mean addiction was there.
Bo: But it wasn’t 21 you had, you made a million bucks a year. So you’re thinking you’re in good shape. Only that year.
Brian: You’ve got to believe you’re thinking off the cliff or did you just go from a million, 700, 400? I mean, how did it drop?
Christy: That’s how it drops for sure. And then I think within, and those were those residuals that kept coming in, and then you’re saying to yourself, well, I have the residuals, so that’s almost like a paycheck. Like I don’t even need to work.
Brian: Are those six figures at this point?
Christy: No, those are not six figures. They’re like, I mean, I think they tapped out at like $20,000.
Brian: Wow and so it’s not enough to sustain a lifestyle that you were basing it off of.
Christy: No, definitely not. And I think I remember calling my brother who is in finance. Shout out to him. And he also lives in Franklin.
Bo: Oh yeah, let’s go.
Running Out of Money and Starting Over (27:14)
Christy: And honestly, he was the only one that I could trust at the point at which I felt like I was about 23, 24 and I wasn’t working, because mind you, Disney wasn’t going to hire me anymore because I was too old to be a kid and I was too young to play the mom. So there was no casting lane for me. And again, I’m not getting on Maxim. I’m not getting certain roles and it was hard. There was like a very big dry spell. And it wasn’t because I wasn’t trying. It was because I was dealing with other emotional upheaval from the lifestyle that I’d lived from a young age. So yeah, I called my brother and he was like, “Okay, I’m going to help you the best I can, but you have to live on $100 a day. That’s what you can afford.” And he really tried to help me with that. And at that point, I think I was just kind of in a really dark place and I was clubbing all the time, in and out of really bad relationships. And I was just so unhappy that I decided I would go back to college. So I’m like 24 or 25 at this point and I decide I’m going to move back home. I’ve got very little money left from the Coogan account that I am now going to have to take a loan to go back to college because I’ve been living off of that Coogan money. Thank God for the Coogan money though. Because that was what helped me.
Christy: And so then I move back home for a couple months before the semester starts and I just am so beside myself. I’m like, I just don’t know what to do. Like I don’t know what my next steps are. Maybe I’ll direct. Because when you’re given this life, you’re a professional at what you do. You have a career in a very particular skill set. What are you supposed to do when that skill set says okay, we just don’t need you anymore? So you have to say to yourself, well, what is parallel to this? I guess I could direct or whatever. I’ll go back to college for a film degree because initially I was going for political science. I switched gears. I tried to rebuild from there and I did get a grant to go back to school. So shout out to Barnard for getting a grant, a private grant from somebody who was an alumni who was also in the arts and decided they saw my file and they were like, “We’re going to give this girl a grant.”
Abound Wealth Promo (29:41)
Brian: Bo, I want to make sure we’re clear about something. We’re financial advisers, but we’re not saying everyone needs to go hire a financial adviser.
Bo: Yeah. If you’re early in your financial journey, your dollars are almost always better off going toward your goals rather than paying someone like us. And there’s no shame in just using our free stuff. We literally give away calculators, courses, and this entire show is free because we actually want you to use it to build wealth. That is the foundation of the abundance cycle.
Brian: Yeah. Fact of the matter is, if we can help you be a successful do-it-yourself investor, that’s a win in our book. But we also know that success often makes things a lot more complex. Maybe you’re not feeling that complexity yet. And that’s okay. But if your financial life ever gets complicated enough that you want a second set of eyes, we’re right here to help. We’re fee-only fiduciary advisers, legally required to work in your best interest. Whenever that day comes, head to aboundwealth.com and check us out. Until then, go use all the free stuff.
Ringing the Bell (30:38)
Christy: I actually wanted to tell you a really funny story now that we’re having some levity here. September 17th, 2008. Okay, this is a little trivia for you guys. Do you remember what happened September 17th, 2008?
Bo: Was that Lehman? Was that the Lehman Brothers collapse?
Christy: Yeah. So, I was supposed to ring the New York Stock Exchange bell.
Brian: On that day? Wow!
Christy: And I missed it. I missed it. Yes. I ended up getting stuck in traffic in Midtown and missing ringing the stock exchange bell. But God saved me from that one because that was the day the Dow, the entire thing, was down almost 50 something.
Brian: No, you know, that was the year the market at its lowest during 2008 was down like 52% for the year. It was catastrophic for people.
Christy: I show up and I go, “I’m so sorry I’m late. Oh my god, what can I do?” And they are so not worried about the bell. In a normal day, we would be very nervous about this, but today, and I was going to bring the coin. They still gave me the coin. I still got the coin.
Bo: Send us a picture of it. That’ll be awesome.
The $40,000 Psychic Mistake (31:49)
Christy: So, I think like I learned a lot. I learned a lot of what not to do, of course, but unfortunately there were other things that happened. I tell my story about how I gave money to a psychic and that was throughout all of this.
Brian: I saw that actually. That was on your social media in the last day or two.
Christy: It was big.
Brian: It was like $25, $30,000 you gave to the psychic.
Christy: The first time.
Brian: Okay.
Christy: The first time. Yeah. And you know when we talk about addictions, I think there was also an addiction to spending money and my relationship to money was like how does it make me feel? And there was that first time that I had a woman approach me at the stage door and say, “I know your future and you’re cursed.” She was ready to go with that card. Full solicitation. She knew what to do and she targeted me and I just ate that up. Because I was again sort of addicted to people, places, and things and I was going through a breakup. I gave that woman $20,000 for an amethyst stone that never came. And I sobered up before it and was like, “Well, what was I thinking?” And I went to my dad and he’s like, “This is my fault and I should have been in control of your career.” And all these things kind of created infighting within my family about this money that was spent. And then cut to like a year later and I was like, I need to get this crystal. So I found another psychic. A lot of people don’t know this, but I found another psychic and I march in and I go, “I’m going to give you $20,000 and you’re going to give me an amethyst that’s blessed and that’s all that we’re going to do here.” And I sobered up again after giving the money and I was like, what is wrong with me?
Bo: Oh, so you actually did it again.
Christy: I actually did it again.
Bo: But did you get the rock?
Christy: I didn’t even get a rock.
Bo: You paid $40,000 for two rocks that you never got.
Christy: I mean, I should have gone to church and called a therapist.
Brian: The power is the act of persuasion to get somebody to give you or perceive their value for $40 grand. I’d at least like to have had the rock. If I’m going to go through that, I’d rather have this stone.
Rebuilding Her Career and $200,000 of Debt (34:07)
Bo: All right. Okay. So again, you’re going through these bouts. Up, down, up, down. But at some point it clicks and you’re like, “Okay, I’m going to figure this out.” Well, at that point, like when your brother said live on $100 a day, did you start living on $100 a day?
Christy: I did. I did what I could, but I think that came with a lot of shame and it came from a place of like, well, what am I worth anymore? And so I think that kind of sent me in a spiral, which led me to just go back to school. And so I met my husband there and my husband is a Marine veteran and he had his own relationship to money as a lot of veterans do with debt and stuff like that. And he was sort of on loans getting his degree on the GI Bill. And we kind of both met in a place where we were both like, well, what do we do with money? Like, how would we make it? Okay, we’re going to graduate. We’re older now because we’re both in our undergrads. But we had stars in our eyes to be able to produce films and to go back out into LA together, even if we needed roommates. We were going to be really scrappy. And then that was really a rough time for us before we discovered this world of social media that I really am working in now. And so there was a program called Voc Rehab, vocational rehabilitation. For any veterans listening to this, I strongly encourage you to look into it to get your master’s degree. And he was able to qualify for that. And so he went for screenwriting and was getting his master’s degree. Meanwhile, I was doing all these odd jobs. I was teaching acting classes to kids in hotels. There are these little popup shops that I would highly suggest not doing because if you ever are getting scouted in the mall, you’re not actually going to get cast in anything. And then there was Comic-Cons.
Christy: And there was a program called Voc Rehab, vocational rehabilitation. For any veterans listening to this, I strongly encourage you to look into it to get your master’s degree. And my husband was able to qualify for that. And so he went for screenwriting and was getting his master’s degree. Meanwhile, I was doing all these odd jobs. I was teaching acting classes to kids in hotels. There were these little popup shops. And then there were Comic-Cons. Comic-Cons have always been sort of something that people now are doing, but back then it was looked down upon. And Disney initially was very anti-comic until D23. And then they realized there’s nothing they can do. So comic cons are just something that you could do. But initially it was looked down upon. And I was wondering if I printed out the Kim Possible pictures and pictures from all these Disney shows to sign if I was going to get a call from them, right? Like I didn’t know. But Comic-Cons were something that I also did. And then yeah, it wasn’t until I got pregnant that a friend of mine was like, “Well, you know, you can get free baby stuff if you post about the baby stuff.”
Christy: And it wasn’t until then that my life completely changed and now this is 10 years ago, and Instagram is becoming like, there were definitely influencers but we didn’t know how much they were making, but they were making a lot. And old school YouTubers were also making quite a lot of money. And we decided that I was going to post for free baby stuff but then we got a call from a company called Llama. They were like, “We’re going to pay you $100,000 for 12 months of content.” And my husband negotiated that and he was like, “I can’t believe I just closed this deal. I think I’m actually good at this.” And I go, “Well, we should have you continue to do that. There are no commissions paid out.” So I was like, “This is really something we’ve just stumbled on. Let’s start to make content.”
Bo: So you land this deal. And I’m assuming this was the first of a number of deals that are likely going to come through. What did you guys do? Okay, now we’re going to every check that comes in, we’re going to put some money over here.
Brian: So you land this deal. And I’m assuming this was the first of a number of deals that are likely going to come through. What did you guys do? Okay, now we’re going to, every check that comes in, we’re going to put some money over here. And mentally, how did you say, we’ve made money in the past, we did not save any of it. We’re finally after this drought, after the season of odd jobs, we’re finally going to start making money again. Behaviorally, what did you all do different?
Christy: We had a lot of debt that we had to pay down. So that’s when we started to prioritize all of that and we were like, “Okay, let’s get on payment plans and like car payments and credit cards.” We had lived off the AmEx until we figured this out that we actually had a way to.
Bo: Like, how big and scary was the number?
Christy: It was a couple, it was like $200,000.
Brian: Woah.
Christy: Yes. And we had a lot of debt that we had to pay down. So that’s when we started to prioritize all of that and we were like, “Okay, let’s get on payment plans and like car payments and credit cards.” We had lived off the AmEx until we figured this out. How big and scary was the number? It was like $200,000.
Brian: Wow.
Bo: So did you go into the marriage budgeting?
Christy: We didn’t talk about money. Yeah. We were just in love and we both had these pasts.
Bo: Are you budgeting now?
Christy: Oh yeah, absolutely. That’s what I mean. I promise you. Yeah, we are budgeting. We are so much more savvy. There’s index funds and there’s, you know, my husband’s acumen for financial literacy has grown so much and he just dedicated himself to reading so many books so that we don’t ever go back to where we were. And it’s really amazing to see that my husband is just so protective of us. And I learned so much from him because there’s no decision that’s made that’s not explained to me now in layman’s terms. And we make, you know, a really good living doing what we do. And you know, like I said, there’s no commissions paid out and it’s just money in and you get to choose how you spend it and where it goes.
Brian: And social media is the wild wild west. I mean, we know a lot of other content creators.
Christy: And what we were able to do was to create a new brand for myself. So when I decided to start posting on YouTube, that’s when people started to find me again. And I created this value where there was none for so many years, because of nostalgia. We tapped into this frequency of what people would want from me. We just got really scrappy and in the weeds. And of course, when you have kids, things totally shift for you financially. Your priorities change. Especially for my husband, he was just like, “Nope, this is where we’re going.” And God makes a way, I guess, because it just started to hit and hit and hit. And then I grew my platform over time. And now I don’t have crazy numbers compared to other Disney stars, but what I have is a dedicated fan base of folks that are engaging with me and a very high retention rate in that regard. And so I can go viral, whereas a lot of influencers can’t go viral. So my husband’s pitch is we do a lot of cold calling, cold contacting, like you do the reach outs for the products. We do the reach outs directly, which is not something that I think people expect of us, and we have an individual who will find people on LinkedIn and be like really aggressive and just be like, hey, Christy’s really interested in setting up a call. Are you interested? And for as many as are out there, they are millennials that grew up with me. And so they’re excited to see that. Then I go and follow them on wherever they are.
Brian: When we reached out to you, I mean, we even had this conversation. We were like, I think Christy’s actually talking to us directly in the messaging.
Christy: That was me.
Brian: Yeah. That’s what we were curious about. I mean, it shows a commitment to kind of making this happen. Because it’s one thing to talk to somebody’s people and nothing wrong with that. We do that sometimes too. But there is something when you actually connect with somebody directly. It just feels a little different.
Christy: And you hear these nightmare stories about influencers who really just think that they’re the biggest things in the world and we’re not doing that. We’re coming at it from a place of true collaboration and like how can we make the best content for the product? And there are a lot of ways to do that. So whitelisting is a really added bonus that I get for brands because I have the traditional name of Hollywood and people know my name and likeness, but they’re also getting a person who’s acting as an influencer. So we sell that as a package and it’s very beneficial.
The Life-Changing Moment Behind Her New Book (42:22)
Brian: We talked before the cameras turned on. This book was a two-year endeavor. Talk to us about it. Why did you write it? What was the thing that lit the fire in you to want to throw two years of your life into something?
Christy: I think it was when I got shot in the face.
Bo: That’s the first time that’s ever come up on our show.
Brian: I was just over in Scotland with a few other couples and I had never shot sporting clays before, but I did that like probably three weeks ago for the first time. And then when I heard and I saw some of the pictures up on the monitors… How in the world did that even happen? Because like the shooting range I was at, safety was, now this was over in Europe so they’re even at another level because they don’t even like guns over there. So how does that even happen?
Christy: Well, it’s Texas, so they are a little bit looser on someone’s property. And you know, you drive out there to wherever it was, Dime Box, and it’s kind of like it is the wild west. I got peppered by birdshot about 250 feet away. I’ve got birdshot still in the back of my eye, a millimeter, a pencil tip away from anything critical to blind me. And I also have it in my forehead still. So, I’ve completely done a medical miracle from what my ophthalmologist said. He was like, “Usually, if a kid gets hit with a Nerf gun, I’m taking out their eye.” I got shot and it was so close that it was cauterized. So it’s cleanly in there and it’s just staying in there. And it’s a really wild story unrelated to finances.
Bo: You’re like the 50 Cent of Disney childhood stars.
Christy: I have been told that I need to have a rap album. I mean, seriously.
Bo: Let’s get this book launched out there in the world somewhere else down the line.
Brian: Because if it was that far, was somebody was shooting and you were just indirectly in the path when they followed the target?
Christy: They flagged it and it was irresponsibly discharged. Yeah. It was unfortunate.
Bo: Wow. As you said, that had a lot to do with you doing the book. Is that right?
Christy: I think so. I think that certain life crises like that happen and I had already been in talks for the book proposal, but at the same time it felt like more than ever a time for me to leave something behind for my daughters. So a big part of this book after every chapter is a letter to my daughters. It is chronological and in the first person voice, but the voice changes as I get older and it becomes a very different person throughout. So, you’re almost rooting for me, but you’re also kind of screaming at the pages. And every chapter that has the “Dear Girls” kind of creates this lighter side to show that I’m okay now. And there’s a lot that I’ve learned from each chapter of this book. I think that this is just a legacy book for me. This isn’t just about a celebrity memoir tell-all. This is much more about breaking cycles and what I can leave to my daughters.
Teaching Kids About Money Differently (45:34)
Bo: So, obviously you guys have young children in the home and you think about your money story. When you think about how you’re going to teach them about money and how you’re going to share lessons with them, what’s that going to look like? Like when are you going to start those conversations?
Christy: Yeah, I mean, I think the first thing we’ve got to do is get them to earn some money. I think they need an allowance. They’re nine and seven and I think they’re at the perfect age to start doing chores for money. And from there we’ll probably open up some sort of an ATM card for them and discuss spending. And I think there are some really great systems out there where it’s like the piggy bank, save, spend. We talk about that a lot.
Brian: Yeah. And I think it’s also important to teach them to give back always. Now, look, you’re the extreme side because you were actually out there supporting your family. What if we went more conventional? I’ll go ahead and help you with something that I’ve shared with my oldest daughter. We talk to a lot of our clients’ kids because sometimes growing up with resources can be just as much of a curse as somebody who grew up dirt poor, because you don’t know what you don’t know and you get to adulthood and you’re in the shadow of the success that your parents might have had. So, your kids might have some of those struggles. The best thing I can say: put your kids to work at something public-facing as soon as they’re like 16. Whether it’s fast food, food service, grocery stores, something that serves the public. Because you want them to get access to the public so they can realize how crazy the people of the world are. And you learn how to develop the skills to deal with that. I think working at Hardee’s all through high school, dealing with the crazy people in the drive-through and at the front counter was so good. If you can make this person happy, you’re probably setting yourself up with a skill set that’s going to serve you whether you’re in accounting or engineering or teaching or in entertainment, because you will be a student of how people are.
Christy: Wow.
Brian: And then as soon as they’re making that money, prime the pump as the parent and help them fund that custodial Roth IRA or a savings account because if we could have whispered in your ear back when you got cast at 14, imagine if not only did you have the Coogan account but then you were funding 15 to 20% of this for the future. It’s a completely different conversation. I mean, you’ve created your own success outside of that, but would a, should a, could a for the next generation to pay it forward. That’s pretty powerful stuff.
Christy: Absolutely. And I think it also really speaks to giving your children a sense of value, a confidence that you can’t really teach them. I mean, you can show them love, but you’re showing them financial love, which is a very different relationship.
Brian: What age do you want your girls to read the book?
Christy: 15 or 16. Let them get a little bit older and then have them read it.
Bo: When someone picks up the book and they read it for the very first time, what’s the thing you hope they walk away with?
Christy: The feedback I’ve gotten so far is that it’s very relatable, which is ironic because there’s a lot of really random stories. So few people have actually experienced that. But I’ve gotten a lot of women who have told me that it’s a very relatable story for them. But I think even if it’s a man reading it, I hope that they learn something about humanity and how everybody has their own journey and that you shouldn’t give up on them and that people change.
Brian: Well, storytelling can be a very valuable teaching method and that’s why I know you’ve loaded it up with stories. And that’s a very approachable way because it’s a natural human nature we all do comparison where we’re like, would I do that? Would I have fallen into that trap? So I think you being so honest is probably going to be disarming but also invite people to hopefully learn something from it as well.
Christy’s Biggest Money Lessons (49:57)
Brian: And you probably have. And look, your book is coming out. What is it? October 8th?
Christy: October 6th.
Brian: October 6th. I’m sorry. But you’re probably, because we are so close now. How’s the insecurity? I mean, are you feeling like, are people going to like this?
Christy: Well, you know, I’m looking at those pre-order numbers. I’m doing this full, as you know, like the book marketing is its own thing. And I’m here and I’m having these conversations for the first time. This is my first financial podcast I’ve ever been on. So hopefully I’m not…
Bo: You’ve done wonderful.
Christy: Did I really?
Brian: Oh yeah. Wonderful.
Christy: Okay, good. I said numbers and you’re saying numbers.
Bo: I mean, you’re so honest about it though. I love the transparency.
Christy: Good. I mean, look, I think that I’m just too old to not be honest about stuff. That’s how I feel and that’s maybe why I ended up doing the book, because you know, people aren’t talking about money. They’re not necessarily talking about the gritty parts of their journeys, especially folks that have been in my shoes. And so I’m proud of the journey and I’m proud of the authenticity that the book represents.
Bo: All right. You’ve got so much experience and you’ve lived such a wild life and seen all these things. We thought it’d be fun to play a little game. And what we’re going to do is I’m going to read a sentence. I just want you to finish the sentence, whatever comes to mind, whatever you think about. This isn’t super hard. But it’s just some interesting insight I think that you have. Are you okay with that? Is that fair?
Christy: I’ll give it a shot.
Bo: All right. Here’s an easy one that I think won’t be too hard. The biggest money mistake that people in Hollywood make is…
Christy: Not investing wisely.
Bo: Not investing wisely. Do they invest poorly or do they not invest at all?
Christy: They don’t invest at all.
Bo: Would you say that’s pretty common? Even these people out there that are making gazillions of dollars and spending, most of those folks that look like Lifestyles of the Rich and Famous are actually broke as a joke. Is that probably a true statement for Hollywood?
Christy: Yes.
Bo: When it comes to money and all of the experience you’ve had from being a very young child actor all the way till now, what’s been your proudest money moment?
Christy: I would say that Llama deal that I got was my first social media deal.
Brian: I would say even more than the year that you made a million. And I think that’s so poignant. It’s not the year that you made the most money. It’s not the year that you were shopping on Rodeo. It’s not the year that you went and bought the fancy car. It was, hey, we hustled and we did this thing and we created this opportunity and we saw this opportunity and we seized it. And that one thing has now led to what’s a pretty exciting place right now.
Christy: Yes.
Bo: I love that. All right. One thing I hope my kids understand about money is blank.
Christy: That it’s unrelated to their self-worth.
Brian: Oh, that money is nothing more than a tool. We love saying that. I love that. That’s also, just kind of adding to that, I always try to encourage people: don’t let your kids’ best days financially be while they’re living with you. Leave some room for them to have some success in their own life. That’s why I’m always amazed in my neighborhood at how many people buy their kids really nice cars when they turn 16. I think that’s a disaster.
Christy: Our neighborhood too, by the way.
Brian: It’s a disaster. I’d much rather, I made my daughter, and I think it’s been, she did the whole buy half of the car. So it was a 14-year-old used car. She bought half the car and then you bought that car. And then she drove that all the way through. She was probably halfway through college before we helped upgrade. It got to the point where the front headlights no longer worked that well. I was like, “Okay, probably time for us to work on upgrading.”
Bo: Well, since you asked and our kids are the same age, I’m going to tell you what I plan on doing for my kids’ car because I think the buy half is great, but I have a better idea. Just a little one-up. And I think you should do this. We’re going to do a third, a third, a third. So my kids are going to put up a third of the cost. Me and my wife will put up a third of the cost. And I’m actually going to loan my kid the final third and have them make payments to me. And it’ll be something reasonable. So if the car payment’s $100 a month, if you want to be able to drive your car and have your keys this month, you’ve got to go out there and babysit or work your job or whatever the thing is to get that $100, because I want them to recognize that’s the way the real world works. If you want to be able to do things, you have to be willing to sacrifice your time, go earn a wage, and be able to do that. So, that’s another take.
Christy: Where do they get the first third from?
Bo: Well, right now they’re saving. My oldest daughter, she’s 11, she just started her own little business. It’s a trash can valet business. So she went and knocked on doors and I gave her this little sales pitch to do and she has seven neighbors in the neighborhood. Every Thursday she goes and gets their trash can, pulls it out of the street, trash comes Friday morning and then she pulls it back so they never have to think about it again. It’s pretty good business every month.
Brian: I might be able especially a cute little girl comes up and asks me, I’d probably be willing.
Bo: I even gave her a joke. It was a tight little set that she did and she crushed it. And so that’s where she’s building up her money right now.
Christy: Oh, is it my turn to ask you questions?
Brian: Yeah, you’re welcome to put us on the spot.
Christy: If someone suddenly made an extra million dollars, they should…
Brian: I mean, look, I think we all have to have a little fun. So I think you should probably take 10% and go do something fun with that. But then the rest of the money, create a plan for it that will actually last beyond just this moment in time. We actually have a great resource and system we built called the Financial Order of Operations where there’s like a nine-step process of what do I do with my next dollar? And I think if someone came into a million bucks, obviously you want to chisel off some fun money, but then I would have them do an assessment of where am I in the financial order and how can I use this to go begin filling in the rest of those pieces.
Christy: I’m like good time uncle and you just actually gave the real answer.
Brian: I just thought it’d be helpful to answer the question.
Christy: I liked it. It was a spectrum. Okay, let’s see. The biggest sign someone is actually wealthy is…
Bo: They don’t try to look wealthy.
Brian: Well, here’s my thing though. If you can be at the gym at 2 or 3 in the afternoon, that’s probably somebody who owns their time. I mean, seriously, that’s a flex because owning your time is the biggest flex. It’s not the car you drive. It’s not the watch. It’s when people are doing things because they want to do them.
Bo: I think one of the best ways to tell somebody actually has money in my experience is they tend to be the people that aren’t trying to show you how much money they have. The people who are talking about the beach house they just bought or talking about the car they just bought or wearing fancy watches or whatever that thing may be, oftentimes I find that those are the hardest fakers. They may look really good. All of those things are not signs that they have money. They’re signs that they spent money. Those two are not the same.
Christy: Yeah. Okay, I love that. The financial hill I will die on is…
Bo: I’ll die on the hill that you cannot borrow your way to wealth. I think so many people think, I’m just going to debt, debt, debt. I’ll worry about it later. The hill I’ll die on is that if you cannot control yourself on living on less than you make, you’ll have a hard time ever being wealthy.
Brian: My hill to die on is that anybody, I mean literally anybody, who figures it out before the age of 40 can be successful. I mean, you’ve written a book of mistakes. I’ve written a book of mistakes. And you don’t have to be perfect. But if you’ll just take a little bit of today and start making good decisions, you can build the ripple effect of what it can do for you in the future. It’s huge. And that’s why I know we live in a society right now where there’s a lot of telling you you can’t, you can’t, you can’t. And I just I’m on the other side of that. I think that we need to be a positive voice telling young people, yes, there are negatives, things are more expensive, but just a little bit of something will build something pretty tremendous in the future.
Bo: Christy, if people want to find you, if they want to stay up to date with what you do, obviously they need to go pick up a copy of the book, but in addition to that, how can they stay connected to you?
Christy: I am everywhere. I’m on Instagram, I’m on TikTok, I’m on YouTube. It’s Christy Carlson Romano on Instagram, Christy Carlson Romano on TikTok, and as well as YouTube.
Brian: Christy, we’ve had a blast. You said we’re your first financial show. So thank you for coming on. Hopefully we weren’t too nerdy. We’re a little nerdy, but not too nerdy.
Christy: Not at all.
Brian: And that’s what I hope, because we’re hoping also this cross-pollination of when we release your show that some of your people will see our stuff, our people obviously see your stuff, and we can show how just back to the point of optimism, everybody makes mistakes, but man oh man is there a redemption story waiting to just burst out like a butterfly. And you have shared yours with us today and we feel inspired. I just thank you for coming on. Thanks for the opportunity. You were so polite when we reached out to even see if you were interested in this opportunity while we were traveling in Austin. So thank you for being so generous with your time with us today.
Christy: Absolutely. Thank you.
Brian: Money Guy Team, out!
Free Resources

Free Resources
Financial Order of Operations®: Maximize Your Army of Dollar Bills!
Here are the 9 steps you’ve been waiting for Building wealth is simple when you know what to do and the order in which to...
Free Resources
Wealth Multiplier By Age
If you want to set yourself up for future success, find out how much you need to save every month to become a millionaire.
Free Resources
Car Buying Checklist
Here’s how you can buy a dependable car that won’t break the bank. Our free checklist walks you through the 20/3/8 rule and strategies to...
Articles

Articles
How To Win With Money in Your 20s (and Set Yourself Up for Life)
The first decade of adulthood is one of the most important periods of your life. The course your life takes when you are younger can...
Articles
6 Financial Changes To Make in 2026
There is no need to wait until an arbitrary date on a calendar to make positive changes in your financial life, but if you are...
Articles
How To Build Wealth With an Average Income
Americans aren’t feeling good about their finances. Last year, 16% of Americans said they believed their financial situation would be worse in a year. Now,...
Financial FAQs
Courses & Tools

How about more sense and more money?
Check for blindspots and shift into the financial fast-lane. Join a community of like minded Financial Mutants as we accelerate our wealth building process and have fun while doing it.
Free Resources
Financial Order of Operations®: Maximize Your Army of Dollar Bills!
Here are the 9 steps you’ve been waiting for Building wealth is simple when you know what to do and the order in which to...
Free Resources
Wealth Multiplier By Age
If you want to set yourself up for future success, find out how much you need to save every month to become a millionaire.
Free Resources
Car Buying Checklist
Here’s how you can buy a dependable car that won’t break the bank. Our free checklist walks you through the 20/3/8 rule and strategies to...
Recent Episodes

It's like finding some change in the couch cushions.
Watch or listen every week to learn and apply financial strategies to grow your wealth and live your best life.
Episodes
Don’t Make This Huge Roth Mistake
When is a Roth conversion a mistake? We break down 5 situations, the 4 questions to ask first, and a case study saving one couple...
Episodes
Financial Advisors React to Actually Hilarious Money Clips
Sports betting as investing, a bank robbery math hack, and lime juice Cheetos. We are back and ready to react to the internet's wildest and...
Episodes
The Biggest DIY Investing Mistakes (And How To Avoid Them)
Are your investments as efficient as you think? From asset location between Roth IRAs and 401ks to outdated beneficiaries and market timing, we cover the...