-
▼
-
▼
Roth conversions can be an incredible retirement tax-planning tool, but one at the wrong time could leave you paying more in taxes than necessary. In this episode, we break down five situations where a Roth conversion may actually hurt you, walk through the four questions you should ask yourself before pulling the trigger, and show you exactly how strategic Roth conversion planning can shape your more beautiful tomorrow. If you’re wondering when to do a Roth conversion, whether Roth or traditional is better, or how Roth conversions affect retirement taxes and RMDs, watch the full episode before making your next move.
We also answer finance questions directly from you! We cover topics ranging from why advisors suggest bonds for retirees, knowing if $300k is too much for a house down payment, and how to make the mindset shift to enjoys spending money guilt-free. Plus our rapid fire segment covers splitting the 25% savings rate between retirement and a house down payment, using Trump accounts to fund a Roth IRA for young kids, ERISA protection when rolling a 401k to a Fidelity IRA, and the great debate: is an HSA actually more valuable than a Roth IRA?
Remember to pre-order your paperback of Millionaire Mission before the store closes TONIGHT, October 7th at 11 p.m. CT!
Enjoy the Show?
Where You Can Watch and Listen:
Subscribe on these platforms or wherever you listen to podcasts! Turn on notifications to keep up with our new content, including:
- Episodes of The Money Guy Show every Friday
- Episodes of Making a Millionaire every other Monday
- Mini-shows every Wednesday
- Ask Money Guy Livestreams every Tuesday
- Tons of other fun content!
Don’t Make This Huge Roth Mistake (0:06)
Brian: Don’t make this huge mistake.
Bo: Brian, I am so excited because we love Roth dollars, or some of the most valuable dollars that end up in our entire army of dollar bills. So if there’s a mistake that one might be able to make with these dollars and with these accounts, we want to make sure that you do not make that mistake.
Brian: Yeah. And look, we don’t make any secret about it. We are big fans of Roth dollars. I mean, think about what you get with a Roth IRA. You get contributions. Yes, you don’t get a deduction. That’s the negative side of it, but it grows completely tax-free. So this whole thing of compounding growth, this is giving you the best of it. Not only does it grow completely tax-free for your lifetime, the other great thing is it grows completely tax-free for up to ten years of your beneficiaries’ lifetimes. And it’s not subject to things like required minimum distributions and other things that regular 401ks or traditional IRAs are subject to. So it really, really is a remarkable, amazing, and wonderful thing.
Bo: And the reason why we like them so much, the reason why we talk about them so much, is because they are so good. Oftentimes the federal government limits who can even put money in there. So a lot of people, as their incomes rise and as they make more money, they can’t even contribute directly to Roth. And so they start trying to figure out what are some other ways, what are some other strategies, what are some other mechanisms that I could begin to beef up my Roth balance. And that’s where Roth conversions, this is a cool little tool that really got opened up with, if you think about 2010, they took away the income limits on doing Roth conversions.
Brian: So a lot of people get really excited about it. And that’s why we want to make sure that we share the good, but also all the negatives so you don’t fall into some traps. And what a Roth conversion is: the textbook dictionary definition of a Roth conversion is we take pre-tax dollars, money that sits in a 401k, sits in an IRA, and we actually convert, pay tax to turn those into Roth dollars. And they’re so valuable that we actually did a wonderful episode with Bigger Pockets Money where we walked through just how valuable a Roth conversion strategy can be. If you remember, we had Mindy and Carl who had this huge portfolio and a lot of it in pre-tax retirement accounts. What we showed them is because they had so much in assets when they retired, when they actually left the workforce, they were going to be in this little tax desert where essentially from about the year 2030 all the way out until the early 2040s, they were going to have a very, very low tax situation.
Bo: But if they waited and just let their pre-tax money continue to grow, when they got hit with the required minimum distributions at the age of 75, they were going to go from being below the 22% federal tax bracket to all of a sudden jumping into the 32 and even the 35% tax bracket, which is a bit of a tax bomb that exists for folks who have big pre-tax IRA balances. Well, we were able to show them: look, if you do good financial planning, you can manage those tax bombs. Because if you just during those low income years take advantage of doing some Roth conversion planning, we were able to show that we could actually increase their assets in value by almost $3 million, and then save them a little over $1.1 million of taxes paid to the federal government by just doing a little bit of prep.
Brian: So Roth conversions: very powerful tool in your financial planning arsenal. However, there are times you’ve got to be careful and there is a checklist you ought to go through to figure out should I pay the taxes now or pay it later. And that’s why we wanted to cover today’s show, because there was actually an article that came out, this was in Kiplinger’s, and it was five times that you should not do a Roth conversion. And as we’re reading through it, we were like, okay, yeah, that sounds right. Yeah, that sounds, I don’t know about this one. So we thought we’d go through these five and kind of give you our take on it.
Five Times You Should NOT Do a Roth Conversion (5:47)
Bo: So the first one is exactly what we just described. If you’re someone who’s in a high income year or a high income season, you’re someone earning in the 37% marginal tax bracket or the 35% marginal tax bracket. There’s a really good chance that at some other point in your life, when you leave the workforce, when you shift careers, when you downshift on what you’re doing, you may be able to convert in a lower tax situation. So if you’re able to have a lower tax situation in the future than you have right now, that probably is a sign that it might not make sense for you to do the conversions. Now for a moment, we are talking about taxable Roth conversions. Don’t mishear here. If you’re someone who’s in a very high income tax situation and you’re doing non-taxable, tax-free backdoor Roth conversions, we love those zero-tax cuts. These are the ones where you’re going to trigger taxes. If you’re someone that’s in a high income year or high income season, you might not want to do Roth conversions.
Brian: The second time that it’s not a good idea to do Roth conversions: I had a dear friend in the publishing world who reached out to me, and he got hopped up on this whole Roth conversion thing, and he’s like, “I think I ought to do more Roth conversions.” And we started talking about it and I was like, “Wait a minute, you’re going to have to use the IRA itself to pay the taxes.” That is less than ideal. That is not what you want to be doing with the Roth conversion strategy here, because you’re going to eat up. Yes, you’re going to get tax-free growth. But if you’re eating up the principal to pay the taxes, you’re creating not only an accelerating loss of the value through the taxes, but you’re also it’s just not a good use of those resources. And you can think of it kind of like this circular reference: I’ve got to pull money out of the pre-tax IRA to then pay the tax. So I’m pulling money out that’s going to incur more tax to pay the tax. And it just turns into this vicious cycle where you end up wasting a lot of dollars. So we think that folks who ought to be considering Roth conversions need to have outside resources, after-tax assets, or liquid cash available in order to pay taxes on the Roth conversions. We agree with Kiplinger’s on that.
Brian: Number three says if you’re someone who expects your tax rate to fall in retirement, meaning you’re again in a high tax bracket now, but you’re going to be in a lower tax bracket when you retire, it probably doesn’t make sense to do Roth conversion, unless for some reason you’re thinking through legacy planning or passing this on as part of your estate plan. If you’re going to be in a lower tax bracket, it might make sense to wait and do Roth conversions at that point in time.
Bo: Now, this next one, number four, you’re going to have to explain this because I read it all through the show prep meeting and I was like, what is this saying? The number four was: the money will pass to heirs who get a step-up anyway. And I was like, wait a minute. Now, if you have traditional IRAs, they don’t qualify for step-up in basis. It’s only after-tax assets that get step-up in basis when you pass away and people inherit it. So what the heck is number four saying?
Brian: Yeah. What this is saying is, it’s not exactly an apples-to-apples comparison, but it’s saying if you’re going to do Roth conversions, and the way that you have to do Roth conversions is you convert the pre-tax assets to Roth, but you burn down all of your after-tax assets to pay the taxes, what you’ve done is you’ve burnt down assets that would have otherwise been available to have a step-up in basis when they pass on. But I’m going to argue: if you’re in the situation and you have the choice between passing on after-tax dollars to your beneficiaries or passing on Roth dollars, while they’re both fantastic and they’re both great for legacy planning, I’m going to argue Roth dollars are just slightly better because not only do they grow tax-free for your entire life, they also grow tax-free for up to ten years of your beneficiaries’ lives. And when your beneficiary goes to pull that money out, it is still tax-free. So I’m going to disagree with this one. It’s not purely apples to apples. I guess if you have highly appreciated holdings that you have to pay taxes on, it at least should go into your analysis.
Bo: Number five: state taxes erase the federal benefit. Yeah. If you’re someone who lives in a high tax state, you’re someone who perhaps lives in a state like California in the very highest tax bracket, but you’re thinking, “Okay, when I retire, I might move to a state like Washington or Tennessee or Texas or Florida where there’s going to be a much lower state tax benefit,” it might not make sense for me to convert in the state that I live now because I’m going to pay a substantial tax when I convert. I might be better off waiting until I’m in one of those tax-free states. Or maybe Roth conversions don’t make sense in my situation at all. If that’s true for you, perhaps taxable Roth conversions don’t make sense for you right now.
Brian: So Kiplinger’s did this article and four out of five we agreed with. On the fourth I didn’t even give it a full four, because you should take into account the tax considerations of your after-tax holdings. So now that we’ve kind of gone through this checklist of the article, we want to take it a step further and actually give you what are the things you should consider. So if you’re in this mindset of, hey, I love the benefit of Roth accounts in general, whether it’s 401ks, whether it’s IRAs, I love the tax-free growth. What mindset or what questions should I ask to make the right decision?
Bo: Yeah. And as we were kind of walking through all of these, these are the things that sort of came up. Number one, you want to think about your income: my income now, what tax bracket, what tax rate does that put me in, and then what do I think my income tax bracket and income tax rate is going to be later? And I want to make sure that if I’m going to convert either now or later, it’s a positive arbitrage and I’m converting when I have a low tax year, so I’m not forced to have higher tax years later. The next point: do you have enough cash or access to cash to actually pay the taxes to go through the Roth conversion? Don’t skip out on this step to make sure you can actually pay to do the Roth conversions. When it comes to Roth conversions, we also want you to answer the why: is this part of an estate plan, meaning the reason that I’m doing these Roth conversions is so that I can leave assets to my beneficiaries when I’m no longer here? Or am I converting to Roth because those are going to be tax-free dollars that I’m going to use at some point during my retirement lifetime? You want to define how and when you’re actually going to use those dollars. And then of course, state taxes: a lot of you, the easy button is you say, well, I’m just moving to Tennessee where the Money Guy Show is filmed. But there’s a lot of others out there, Nevada, Washington, Florida, Texas, all these are lots of opportunities to get some tax-free growth in retirement.
Brian: Awesome. This, as you can tell, is a big decision and the decisions you make can have a huge impact. I think Mindy and Carl are a great example. They were no longer at the pass-fail situation in their financial story. They had done very well. They were financially independent. But this decision had huge implications in terms of how much tax they were going to pay and what legacy they were going to leave behind. Perhaps you’re not at that decamillionaire level and you’re trying to figure out, do I have enough? Am I at the place? Are the decisions I’m making today going to impact what kind of life that I live in retirement? These are big decisions, and most people when they face that, it’s the first time they’ve tried to make that decision, the first time that they’ve navigated it. And so if you are someone who’s there thinking about that or trying to navigate that, this might be a great time to consider taking the relationship to the next level. We often say, look, we love giving away free advice. Keep hitting the easy button as long as you can. But one day when you reach enough level of success, complexity will find you. And that’s when we love for listeners to become clients. Because when you start strapping in tax liability, Social Security, your IRMAA calculations for Medicare and the surcharges that are out there, you quickly see how all these things are stacked on top of each other. So what seems like it was just a simple decision to do a Roth conversion has a lot of waterfall elements of additional things that are impacted.
Bo: Brian, I love that we get to do this. I love we get to see these articles and give you our take, let you know what we think about them. And I love even more that we can answer your specific questions and speak to the things that you guys care about. It’s why we have the team every Tuesday out in the wings collecting your questions. So if you have a question you want to get us to weigh in on, make sure that you get it in the chat right now. So with that, creative director, I’m going to throw it over to you.
Rebie: I’m excited. I have Andrew S’s question at first, but before that, a very important piece to everyone listening. Tomorrow night, the Millionaire Mission merch store will be closing. To get access to your very own Money Guy and Millionaire Mission mugs, tumblers, paraphernalia, you need to preorder Brian’s paperback. We’re very excited. In November, Brian’s updated and revised version of Millionaire Mission, now on paperback, is releasing, and we’re excited because this means it’s just the next iteration of getting these great financial ideas out to the masses. So to say thank you for helping us with that mission, we have a ton of preorder perks all lined up for you, one of which being an exclusive Millionaire Mission merch store for preorders. To get access to that, go to moneyguy.com/millionairemission. Preorder your book from wherever you want to get your book. It’s on all the major retailers. And then go back to that page because there’s a preorder perks button where you can fill out a form showing you ordered the book, and we’ll email you with all the perks, including a secret link to the store. But the store closes tomorrow night. There are still some other awesome perks like Brian’s Book Club that we’re going to be talking more about soon. And then also a special role in a secret channel on our Moneyverse Discord. So lots of reasons to preorder, but the big one today is to get access before the store closes tomorrow night.
Brian: If you’re listening to this on podcast, it might be tonight. It’s October 7th. It’s going to close. And I think this book would make a wonderful Christmas gift. A wonderful stocking stuffer. A wonderful thing to pass along to someone so that you can spread the good news of sound financial decision making. If you have someone in your life, maybe you’ve read the book, but you want to figure out how you can pass it on, it’s a great gift. I mean, it’s not a completely different book, but I got to go deeper on some things. It still has all the same awesome stuff that Millionaire Mission is known and loved for. So if you’re gifting it, they’re getting that same awesome book that is Millionaire Mission, but with new stories, updated numbers for 2026. I also didn’t feel like I scared the kids enough. So I was like, we’ve got to up this a little bit, you know, Halloween right around the corner. It’s a great gift for Halloween to really, really scare the kids into making better financial decisions.
Q&A: If the Trinity Study Showed 100% Stocks Win, Why Do Advisors Suggest Bonds? (19:37)
Rebie: All right, let’s get to Andrew’s question. Andrew S says, “If the Trinity study showed the best portfolios had 100% stocks, why do advisors suggest bonds for retirees if mathematically stocks are always better in terms of both growth potential and long-term success?”
Bo: Well, okay. First, what was the Trinity study? For those of you who aren’t familiar, it was a study that was done that determined: looking at a standard 30-year retirement time horizon over all the different 30-year periods that we’ve had over some period of time, what probability of these specific allocations of portfolios made it to the end of the plan and were not depleted before the end? And then it came out to figure out: what was the most likely, highest probability, long-term sustainable withdrawal rate across the vast majority of those periods that existed? And what they determined originally was it was somewhere around a 4% withdrawal rate would allow that. But what was interesting is that the Trinity study did it based on portfolio allocation, and they asked: what’s the rate of success for a 100% equities portfolio? What’s the rate of success for a 60/40 portfolio? What’s the rate of success for a cash only portfolio? And they calculated where that existed across those. And what Andrew was alluding to is that all-stock portfolio, the 100% equities, seemed to be the best. And his question is, well, if that’s the case, why wouldn’t I just do that?
Brian: Well, because you actually have to start using the money. And that’s the problem. Look, there’s a difference between risk tolerance and risk capacity. And there’s also sequence of returns risk that you’ve got to pay attention to. Because if you think about the fact that if you retired in 2007, you would probably be petrified if you then experienced 2008 in your first year. If you retired in 2021, 2022 would have been a shock-and-awe moment on your retirement. Because if you’re consuming assets when markets are down 20 to 30%, it can be devastating to your long-term success. So that’s why you always have to be careful and have the context of what does this study actually show me and what do you do? And then also, I would be careful every time you listen to anything about investments: there’s usually an asterisk or a little voice that comes in at the end and says past performance is not indicative of future performance. So be careful. And like right now, right this second, bonds are absolutely getting crushed. If you look at what’s happened to the ten-year Treasury, it’s reaching highs. Which if you’re an existing bondholder, that actually hurts you because why would they want your bond portfolio when they can go get newer bonds at a higher rate? But if you’re a person who’s adding, a retiree now, if you’re adding now, bonds are actually probably going to have a little wind at their back coming in the next ten years. So that’s why you have to be careful just reading a research study like this and saying, well, I never want to have bonds in my portfolio. You might need bonds not only to give you stability, but they might actually be a decent asset class based upon just what is going on in the wonderful world of finance right now.
Bo: And look, we know that personal finance is 80% behavioral. A lot of times people diversify because there’s a mental, psychological thing that happens when you go from using your back and your brain and your hands to create wealth, and now you’re counting on your army of dollar bills to do it for you. It messes with your mind. And what you don’t want to do is reach that 2008 or that dot-com bubble burst and go through that heart-wrenching thing, and because you’re in an all-equity portfolio you reach that capitulation point where you’re like, I can’t do it, I can’t take it, I can’t handle it. I had the worst luck, the absolutely most awful sequence of returns right at my retirement. And you end up making a very bad decision. So that’s why most people diversify. But I would argue this for people who have been building and saving: the question I’d ask is, why risk it? And this is what I mean by that. Even if you look at the 100% portfolio, the probability of success that existed there wasn’t 100%. There were still some failure rates based on bad sequences of returns. And I would liken it to this: in a revolver there are six chambers. If you were going to play Russian roulette, it’s one out of six, a 16.6% chance of a bad outcome. There’s a much higher percentage chance of a good outcome. Is it worth risking it? Would you play the game if the one bad outcome, the 16% chance, could be so bad that it was devastating, that it was an outcome that was unrecoverable? Your portfolio is no different. Would you be okay with a 100% equity portfolio? Maybe. But if there’s a chance that you could fail, if there’s a chance it could derail, if there’s a chance that you could go from financially independent to very much financially dependent, is it worth it? Why not focus not only on your risk tolerance, how much you think you can handle, but shift and think about your risk capacity: how much risk should you take based on where you are and based on your financial situation?
Rebie: All right, get your rapid fire questions in if you’re watching live on YouTube. Put RF at the beginning of your question and enter it into the chat. And we’ll see later in the show if Brian and Bo can answer them in 30 seconds or less.
Q&A: Is $300k Too Much to Put Down on a $400-500k Home? (27:05)
Rebie: All right. Chris says, “My wife, 31, and I, 36, have $300k saved to put down on a home we’re looking to buy in the $400 to $500k range. Is $300k too much to put down? We have $440k in retirement and we’re saving 25%.”
Bo: Oh wow, gracious. I wish I knew their income. Man, it would be super cool to know their income. Chris, if you’re out there, share your income if you’re willing. That would help us with the question. Let’s talk about your trying to figure out if he’s ahead of the curve. Because at 31 and 36, your early to mid-30s, we know that by the time you get to 30 you should have one times your annual salary saved up in liquid investments. By the time you get to 40, you should have three times your annual salary. So my question would be: how close is $440,000 in retirement savings to being three times your annual salary? Because that’s like the direction you’re training towards. If you are saving 25%, which it says, that tells me that you’re in step seven or eight of the Financial Order of Operations. And if you decide at that level that one of your goals is to be debt-free and have a lot of equity in your home, I think that you get to choose if you want to put $300,000 down on a $500,000 home. Now for me, income is $200,000. So I’m going to do some quick math: are you on track to hit $600,000 by the time that you get to 40? It sounds like you are. They have $440,000 in retirement. So that’s a little over two times. They’re on track to probably be at three easily in four years.
Brian: Here’s my advice for Chris: I think you can absolutely do that if you want. Is it the most optimal financial decision mathematically? I would say perhaps not at your age. Because you know what’s cooler, or just as cool as being debt-free, is having the ability to be debt-free. So I might think about, based on my income, what if we put $100,000, $150,000, whatever the number is, and had that money working for us? Might that create the mechanism by which we could actually be debt-free sooner than if we put all the money down on the mortgage? Even though I know rates are rough right now at like 7.5%, I’m going to give you the pass to do it. I don’t know if it’s what I would do as mathematically optimal. But definitely, Chris, go do the Know Your Number tool. It’s free at moneyguy.com/resources, just to ensure. Because that lets you put in your true goals, what you think you want to do at retirement with based on living expenses and everything else, so that we’re not having to guesstimate if you’re ahead of the curve, behind the curve, or right where you’re supposed to be. Go do that exercise first. The second thing I’d have you do is create a ten-year spending and goals list, because what I don’t want you to do is put down this huge sum of money on this house, but then you tell me next year, because you’re growing your family, you need to go buy a minivan for the family. Because if you think mortgage rates are rough, wait until you see what car rates are right now. Make sure that going in there’s no big goal coming up that would require capital. Because once the money goes into the house down payment, it’s hard to get it back out unless you refinance or sell the property, and both of those can be an expensive endeavor.
Q&A: How Do You Make the Mindset Shift to Start Spending on Lifestyle? (32:23)
Rebie: Next question is from Mega Veggie Burger. “How do you make the mindset shift into spending on lifestyle even if you can comfortably afford it? P.S. We have used your online calculator and know what we can afford.” Meaning they’re on a healthy curve.
Brian: I think you will get to a point, and this is something I had to do: it wasn’t until I was probably 42, 43 that I actually started feeling, okay, I don’t have to be so rigid, because I started noticing when we had good quarters in the investment marketplace, this thing was literally replacing months, if not even a year, of what I spend, because we just didn’t spend crazy. And then I started thinking about the time. I mean, when you look at your children and you realize, holy cow, they’re only going to be in the house for another 6 or 7 years before they go off to college, and I want to make sure that they look at this place with excitement to where they might actually come back down the road. It’s those type of things. And if you start feeling that your tightwad tendencies are impacting relationships, this is probably the time to reevaluate. Because look, we’re not here to tell you go hog wild and start spending lavishly, but if you’re way ahead of the curve, you do need to balance it. Because I know the typical American typically is not saving enough, but there are a lot of you financial mutants that kind of drift into financial miser territory. If you don’t ever update the mindset shift as you start building enough traction with your army of dollar bills, that you can start enjoying these resources, because you’re only going to be in your 30s once, you’re only going to be in your 40s once, you need to plan accordingly.
Bo: Yeah. So often in the financial world, we talk about regret that people have: man, I wish I would have started earlier, I wish I would have saved more. There’s another kind of regret that we don’t talk about too often, but it’s very real. And I don’t mind sharing: I was so tight in my 20s and so focused on building and achieving and growing. I wish I would have gone to more Tuesday night movies. I wish I would have gone to more coffee dates with my wife, because now we’ve got kids, messy middle, all this stuff. We don’t get to do that stuff as frequently. And had I done that and had I spent that money, it would not have changed our financial circumstance. And so what I would do, the way that I would shift your mindset, Mega Veggie Burger, is I’d begin asking: hey, what are the things we truly care about? And it doesn’t have to be spending on things like nice cars, nice homes, whatever. Maybe for you it’s memories. It’s traveling. It’s going to have experiences. It’s seeing different parts of the world. Maybe it’s convenience: I loathe cutting my grass. I want to let someone else cut my grass, or I want to have someone else clean my home, or I want to have someone else change my oil. Start figuring out: if money didn’t matter, if tomorrow I had $100 million, what would I spend my money on? And if you make your list long enough, you’ll get down to some stuff. You’ll be like, well, man, I don’t have to have $100 million to do that. I could probably do that today. And you’ll start recognizing that if you’re doing all the things you’re supposed to do, saving the way you’re supposed to be saving, building the way you’re supposed to be building, and you’re out ahead of the curve, there’s nothing wrong with increasing your lifestyle because you can’t go back and redo it. Brian just said, you don’t get your 20s back, you don’t get your 30s back, you don’t get your kids’ youth back. So if there are things that you could do now and it will not sacrifice the ability of your future self to live the life that you want to live, I think getting to that point and regretting it later would be super sad.
Brian: You just said something that triggered a thought in my head. So much in your 20s, that latte effect that we tell everybody: hey, watch how often you’re going to get the coffees and those type of things. It does matter because that’s why we talk about budgeting. When you’re at the beginning of the journey, the latte effect matters. Maybe the first thing you want to do on trying to go from this miser to the full mutant where you can unleash more is you throw out the latte effect first, because those are things that probably in your 20s you were rewarded for tightening up. But now that you’ve had a little success, throw those out first. Because I went on a trip recently, and one of the gentlemen said, “Hey, you know what, if you don’t mind, just to make things simple for dinners and when we go to restaurants and bars and other things, I’m just going to pay for everything and then I’m going to send you a bill at the end so we can all Venmo.” I was horrified at first. But when he sent the bill with a spreadsheet, it really wasn’t that bad. When you looked at the total price of the trip that we spent and then the cost of the food for the restaurants, it was so small comparatively. It was kind of an opening thing for me. I was like, if I would have done this trip the way I was planning, I probably would have ordered a glass of water at dinner. And I probably had a mindset shift even in my state now that that experience gave me, because the cost of what he was asking for reimbursement compared to the total trip was just not relevant but it was a better experience. So maybe throw out the latte effect first and see how you enjoy going on those Tuesday nights or doing vacations or nicer restaurants. It might be something there.
It Does Not Depend Rapid Fire Segment (39:16)
Rebie: Good stuff. All right, thanks for the questions. And now we’re going to move into our rapid fire segment, where Brian and Bo will answer your questions in 30 seconds or less, and they cannot say the words “it depends.” At the end of rapid fire, we will make sure we clear up anything that doesn’t get to be said in those 30 to 15 seconds. But with that, let’s get 30 seconds on the clock. Let’s start with 30. Here we go. First question: how much of the 25% savings rate rule should go towards retirement versus a down payment for a first home purchase?
Brian: I mean, I think it’s not. It’s just a savings rate and then you’re putting it towards the Financial Order of Operations. So you have to be careful thinking about compartmentalizing instead of thinking about each dollar in the plan. You have to define your goals: your whole goal for homeownership and your goal for financial independence and the timeline around those goals. And you want to construct your savings behavior based on those. So for some people, 100% of the 25% might go towards the home. For other people, it might be 5%.
Rebie: Next question: if a person is middle age and has a good mind for business and a great business idea, would you guys oppose investing into a business over a 401k, but still maxing out a Roth IRA?
Bo: Investing in a business like you’re going to start it yourself? Or like a buddy has a business? I think this is a private investment into a friend. So here’s my question: would I do that instead of a 401k? I do not think it’s an either or. I think it could likely be a both and, assuming you’re saving 25%, assuming you’re ahead, and assuming the place in your financial journey where a private type investment would make sense. Not early on in the journey. Private investment is a step eight endeavor. If this is entrepreneurial where you work in the business, it’s before that, but you better make sure you have enough cash and your passion has enough capital to make it through the first 3 to 5 years.
Rebie: Next question: what are your thoughts on using Trump accounts as a way to fund a Roth IRA for my kids? He would start with the Trump account, then move that to a traditional IRA, then do a Roth IRA conversion during low income years. It’s for my one and three-year-old. Does that make sense?
Brian: Do the Trump accounts. We even want to do a Q&A show on Trump accounts versus 529s so that we can take the free money. But I think the federal government is actually stepping in and making these accounts. They go pre-fund them whether you sign up or not. But do the Trump accounts for the free money.
Bo: I think there are distribution limitations. So the ability to have money in a Trump account, take it out, fund a traditional IRA, your kid has to have earned income in order to be able to do that. So if they don’t have income, they can’t do an IRA. I think that strategy won’t work as described.
Rebie: Next question: at what level does a giving account make sense?
Brian: Two different options here. One, if you have a lot of highly appreciated securities, it doesn’t matter your level of giving: a donor-advised fund or charitable giving account makes sense because you can gift the securities to avoid the capital gains tax. The second consideration is do you want to keep it really simple and just have this centralized place where you’re deciding when to give? For those that are just starting out, we usually say the Roth IRA and other accounts take priority. Once you get beyond and you have more success, that’s when the donor-advised fund really makes sense. So stacking on taxes if you’re early on: Roth IRA first.
Rebie: Next question: why not use the medical out-of-pocket limit for FOO step one instead of the deductible? I just got billed more than my deductible because of my out-of-pocket limit being higher.
Bo: I mean, look, it’s a fair question. But the thing is we’re basing this off the realistic risk versus you actually having the ability to start saving and investing. If we did full out-of-pocket, I’m worried that you never start your journey because it’s just a much higher threshold. Step two is so valuable. Employer match is like a 100% rate of return. Out-of-pocket maxes can be huge, they can be $8,000 to $10,000. For a lot of folks starting out, it takes forever to get there. I don’t want you missing out on the employer match for that long. That’s why I picked the deductible.
Rebie: Well said. Let’s get 15 seconds on the clock for these last few. Next question says I’m on step seven or eight of the FOO. He has a Subaru that’s 14 years old with 250,000 miles and needs a new one soon. $7k per month is going to brokerage to catch up after a very late start. Should I pause for a few months to pay cash for the new car, split 50/50 to save slow, or finance part of the car?
Brian: That’s the very reason 20/3/8 was invented. I would consider 20/3/8 in this situation. If for nicer cars, pay it off in 12 months. Do a balance. If you’re saving $7,000 a month, you can get a lot done and still fund your Roth IRA.
Rebie: Next question: I’m thinking of moving my Merrill Lynch 401k into a Fidelity IRA. Wondering if losing ERISA protection in the IRA is something to be concerned about.
Bo: I mean, it’s definitely something to consider, but I would go through the fund choices and the expenses first. There have been some recent legal things that have suggested that the ERISA protection will follow from the 401k to the IRA, so it’s not for sure.
Rebie: Next: our income is low enough that we cannot max out both our HSA and Roth IRA. Should we max our HSA, then every year reimburse myself for medical expenses and put that money into our Roth?
Brian: If you do that, you’re kind of essentially turning your Roth into an HSA. But I don’t know that I would actually reimburse the medical expenses. I think I’d leave it inside the HSA.
Bo: We’re coming back to that one. We’re coming back.
Rebie: And last but not least: how does Brian get so much aura?
Brian: I don’t even know what that is. What do you think you’re talking about? What is the color that exudes from me?
Bo: The fact that he doesn’t know what aura is, is how he gets so much aura. That’s actually how. Being oblivious to it is how. Your vibe, kind of like Riz. Their charm. How is Brian so charming? How does he come off?
Brian: I had a great father. My dad, if you thought I was funny, my dad was hilarious. I mean, I just grew up with a kind of goofball father who was also very kind, so I get to attribute a lot of that to him.
Bo: Can I tell you another thing that helps with aura in general? Health. And I will say, as someone who’s had a front row seat to Brian’s life journey for the last 20 years, he started taking his health super seriously. He’s gotten serious about eating right, exercising, all those sorts of things. I think that’s a big thing. You’re kind of Benjamin Button, your aging in reverse. Go look at some of our clips from ten years ago and look at our clips now. It is like a different thing. And I think it has a lot to do with it.
Maybe It Does Depend Segment (48:53)
Rebie: All right, let’s go back to our questions that we didn’t quite get to. There was a lot of information on the car question. He is saving $7k per month to a brokerage to catch up after very late savings. So shutting it down to zero to pay for a car seems ridiculous. But also, how much does a Subaru cost?
Brian: I think it’s a balance. This is where the it depends at that threshold: you might feel pressure to buy a really nice car, but I would buy a reasonable car, a Subaru or something like that. Maybe it still needs to be used. It depends on how far behind you are. A new Subaru typically ranges from $25,000 to $51,000. In my mind, that’s not crazy. If you could do $35,000 to $40,000, you could still keep funding some of the brokerage and, hopefully through your great savings rate, you could balance those things. So it’s not an either or.
Rebie: Great. Glad you got to clarify. Can we do the HSA versus Roth one?
Bo: Yes. That was the one where the question was about maxing out the HSA and then every year reimbursing himself for medical expenses and putting that money into their Roth. So I’m getting the front-end tax deduction from the HSA, and then I’m taking the distribution and reinvesting it into another tax-free account, basically making the Roth deductible in a little bit of a tax hack way. But why not just leave it in the HSA?
Brian: Because if they’re already maxing out their savings rate with just doing a Roth IRA, essentially, think about, we always say if they’re in their 20s or early 30s and they haven’t reached their full maximum earning potential yet, sometimes these are decisions you make because you don’t have money laying around everywhere. I’ll say it: I think HSAs are more valuable than the Roth. Oh, I said it. There it is. Agree, disagree, want to fight? I mean, technically with the triple tax advantage, quadruple actually, but you can access basis and earnings before 59.5 through the Roth. I love Roth IRAs too. That’s why it’s not either or. But if you told me, Bo, you can only do one, I’m probably doing the HSA. But here’s the thing, and maybe I have a bias on this: in Millionaire Mission I described the $10,000 I missed out on in Roth IRA contributions and it still pains me. So just realize you don’t get those tax-free dollars back on years that you missed funding a Roth IRA. HSA might not have good investment options everywhere, but you can open them up at Fidelity now, like you can do an HSA at major custodians with the entire investment universe. That’s a good point, HSA. Still, I’m going to argue here’s where I think the Roth is much better: from a legacy planning standpoint. If I’m thinking more about legacy planning and less about funding during my lifetime, that would push it over the edge to Roth for me.
Rebie: Did we answer the Trump account to Roth IRA question?
Bo: With the Trump accounts, you can roll those to an IRA. You can roll them to an IRA. Not until after 18. So like if I get $1,000 and my baby was born in the last year, I can leave it in the Trump account and then at 18 potentially move it to do some Roth conversions essentially. That’s way way in the future. So that’s why I always tell people, and that’s why I think we ought to do a Q&A on 529 and Trump accounts, because those are probably the two options because most kids don’t have earned income to be doing Roth anyway. And I want people, and I’m glad to hear the federal government is going to just start opening these accounts for kids because it broke my heart that people were not opening Trump accounts for their kids. Don’t be pennywise and pound foolish. It’s just free money. And look, it’s not just for babies. It’s kids all the way up to ten years of age now, because of what Michael Dell and some of these other billionaires are dumping billions of dollars into these things. And I’m even hearing there’s potential for opening this thing up to where some of these wealthy people can start putting in shares of stock and other things. So get in there and get this money for your kids. Take the politics out of it. Because you know what, politics are not red, they’re not blue, they’re green when it comes to what’s going on with these Trump accounts. And we want to make sure your kids get the best of what they have and the potential for the future.
Rebie: Did you want to clarify anything about the ERISA protection question?
Bo: Yeah. There have been some cases recently where they’re arguing that even though assets were rolled from a 401k into an IRA, because the source of those funds were originally retirement ERISA accounts, that perhaps the ERISA protection actually follows it. Now, I don’t think that’s set in stone. I think this is more like revenue rulings type things, but it’s something worth investigating. But you do want to think about that. If you’re someone who’s highly litigious and there’s a really good chance you’re going to be sued, there’s a really good chance you would lose and be responsible, a 401k probably makes sense to keep your assets protected. Either way, go to moneyguy.com/resources. We have a decision matrix. Because it’s also worth considering: you could roll into your current 401k. There are a whole group of things you ought to consider, including the fact that it might be the internal expense ratio or the fees associated with each of these accounts. He said it was a Merrill Lynch account. If you’re comparing Merrill Lynch to Vanguard or Fidelity, I mean, there’s typically probably some cost savings in there. The phrase pennywise and pound foolish comes from 16th century England, refers to the old British currency system where a large British pound was worth 240 small pennies. Don’t be pennywise and pound foolish.
Q&A: Why Is FOO Step Five Specifically Roth and Not Just IRA? (58:02)
Rebie: Cool Nation says, “Hi, Money Guy team. Why is FOO step five specifically Roth and not just IRA? What if I’m in a state with income tax and don’t plan to retire in that state?”
Brian: Specifically, IRA is the account type. We like the Roth version because it’s tax-free. What we’re trying to get you to realize is that step five is all about tax-free growth. Roth IRA, health savings accounts. I can’t even think of a reason why you would do a traditional IRA, because I guess maybe if you don’t have an employer-sponsored retirement plan. Because even if you’re a young person and you do want the tax benefit, you want the compounding growth. That’s the only place where we are one of the people who actually put tax rates on when you should consider pre-tax versus Roth on your 401k. And we always say that 25 to 30% is the gray zone. And part of what goes into that 25 to 30% is your age. Because if you’re a young person, we want you to be getting the power of that compounding growth. So I would be disappointed if I find out people are just funding traditional IRAs versus doing a Roth IRA. To answer your question: it’s because it’s about tax-free growth. Step five is a tax-free growth step. We’re trying to get you in the mindset of that. There is just like there’s an order of operations with math, there’s an order of operations with finances.
Bo: Look, you don’t have to guess about this. Deductibles covered: what’s the risk that if life is something bad happens, you need to have money to cover it. Free money: 50 to 100% guaranteed rate of return, you don’t want to sleep on that. You’re never going to get wealthy if you’re paying 20-plus percent to a bank. And then you’ve got to have emergency reserves in case life happens, which it will. It might not be this year, but it might be next year or the following year. Be prepared. And then you’ve got to start thinking about tax-favored investments. The government has created a tax code. You’ve got to get in there and take advantage of it. Don’t let it just be something that benefits tax-savvy corporations and others. You get in there and do it too, through the Roth IRA. And of course maxing out your employer retirement account because they’re also tax-favored. Happy accident: I just took $7,500, which is the current Roth IRA maximum, and asked what percentage of 7,500 is of the 401k salary deferral, which is currently $24,500. It comes out to exactly 30.6%. What that suggests to me is in your situation, if you’re in a high tax state and you add up your marginal federal rate and your marginal state rate, and it’s 30%, just maxing out your pre-tax 401k will save you enough in taxes that you can then go fund a Roth IRA or fund a backdoor Roth IRA. So I don’t think it’s an either or, Cool Nation. I think it’s a both and, and they can work very, very nicely together.
Closing (1:01:28)
Rebie: Don’t forget to preorder your Millionaire Mission paperback and access your Money Guy Millionaire Mission merch store. Go to moneyguy.com/millionairemission to get all that taken care of. We can’t wait to see you there as part of the mission crew. You do anything on Prime Day?
Brian: You know, I actually, you showed me something you spent a few hundred dollars on and it’s like $120 cheaper today. I bought a new pair of shoes on Amazon yesterday and I’m like, gosh, I need to go check and see if I should have delayed that purchase until today. My new tennis shoes. I don’t really need anything else. I might go see if all the supplements like creatine and things like that are cheaper. I might go ahead and buy some of those things in supplements that I buy anyway.
Bo: Health is wealth. More to come on that. Not really, but maybe.
Brian: Anyway, guys, I woke up this morning, I said I was traveling this weekend and got in late last night, but I woke up excited because guess what? It’s Tuesday. We don’t take for granted that live streams are an important part of our life, to the point that we actually schedule trips and things to make sure we’re here on Tuesday. We don’t take for granted that you’re here on a Tuesday. We appreciate you being financial mutants, working through the wonderful world of finance. We will continue to keep the porch light on and keep making great content. Thank you, thank you, thank you. I’m your host Brian, joined by Mr. Bo and the rest of the content crew. Money Guy out.
Free Resources

Free Resources
Financial Order of Operations®: Maximize Your Army of Dollar Bills!
Here are the 9 steps you’ve been waiting for Building wealth is simple when you know what to do and the order in which to...
Free Resources
Wealth Multiplier By Age
If you want to set yourself up for future success, find out how much you need to save every month to become a millionaire.
Free Resources
Car Buying Checklist
Here’s how you can buy a dependable car that won’t break the bank. Our free checklist walks you through the 20/3/8 rule and strategies to...
Articles

Articles
Where To Invest After You Max Out Your Retirement Accounts
If you have a higher income, maxing out your Roth IRA, HSA, and 401(k) might not seem that daunting - and it may not even...
Articles
How To Win With Money in Your 20s (and Set Yourself Up for Life)
The first decade of adulthood is one of the most important periods of your life. The course your life takes when you are younger can...
Articles
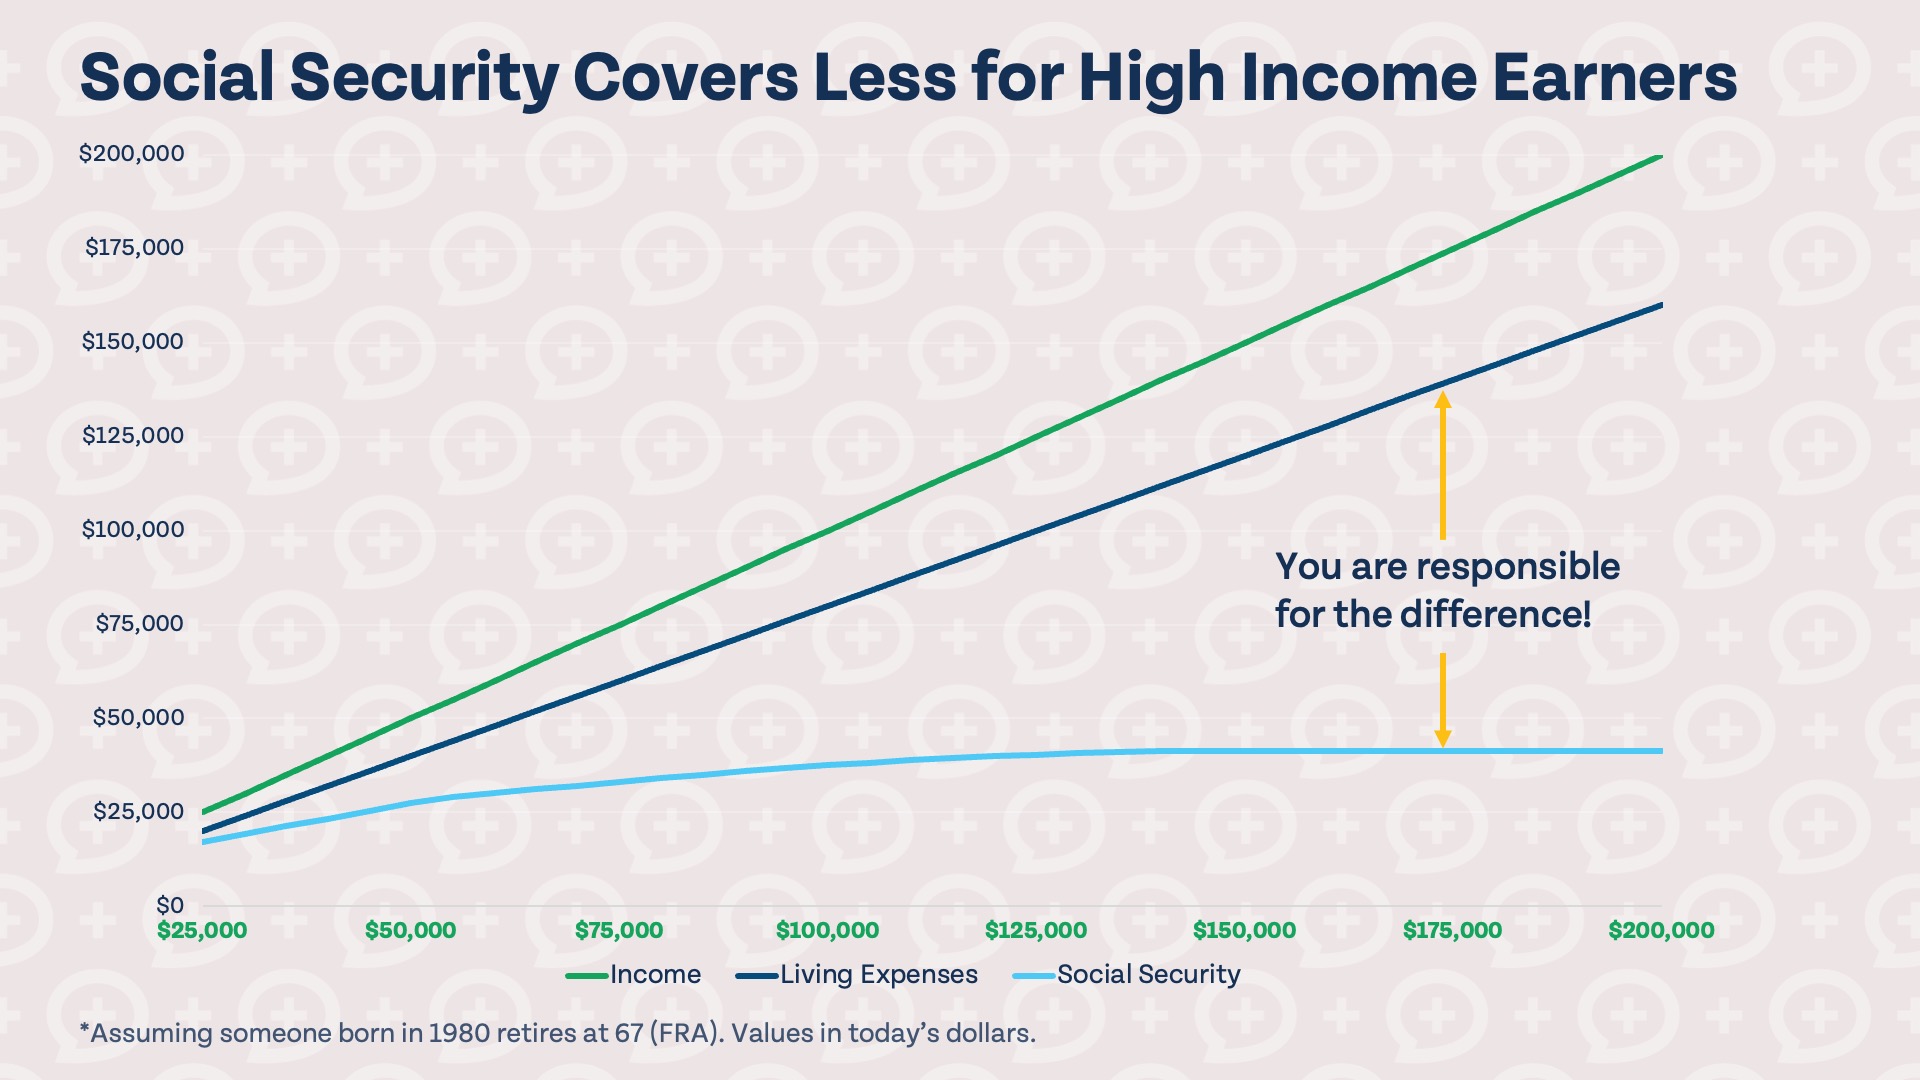
How Much Do You Need To Retire With an Average Income?
It’s easy to become discouraged if you have an average or below average income. Saving for retirement is normally more difficult with a lower income;...
Financial FAQs
Courses & Tools

How about more sense and more money?
Check for blindspots and shift into the financial fast-lane. Join a community of like minded Financial Mutants as we accelerate our wealth building process and have fun while doing it.
Free Resources
Financial Order of Operations®: Maximize Your Army of Dollar Bills!
Here are the 9 steps you’ve been waiting for Building wealth is simple when you know what to do and the order in which to...
Free Resources
Wealth Multiplier By Age
If you want to set yourself up for future success, find out how much you need to save every month to become a millionaire.
Free Resources
Car Buying Checklist
Here’s how you can buy a dependable car that won’t break the bank. Our free checklist walks you through the 20/3/8 rule and strategies to...
Recent Episodes

It's like finding some change in the couch cushions.
Watch or listen every week to learn and apply financial strategies to grow your wealth and live your best life.
Episodes
Financial Advisors React to Actually Hilarious Money Clips
Sports betting as investing, a bank robbery math hack, and lime juice Cheetos. We are back and ready to react to the internet's wildest and...
Episodes
The Biggest DIY Investing Mistakes (And How To Avoid Them)
Are your investments as efficient as you think? From asset location between Roth IRAs and 401ks to outdated beneficiaries and market timing, we cover the...
Episodes
Are You a Wealth Builder Or Buster?
We don't want no scrubs! In this special livestream, we break down 7 habits of wealth builders and everyday millionaires - from living below your...